
Newz: GSEs Create Exception for UAD 3.6 Deadline for Approved Lenders Through May 19, 2027, Weather Impact on Appraisals
October 2, 2026
ARTICLE LIST – Scroll down the page to read
- LIA AD: Weather Impact
- GSEs Create Exception for UAD 3.6 Deadline for Approved Lenders Through May 19, 2027, Plus ACI Update, By Frank Andorka, Managing Editor, WorkingRE
- Palm Beach’s Landmark ‘Ham and Cheese House’ Is Listed for an $105 Million
- MY AD: Disciplinary Proceedings: What Conduct Leads to Discipline? By Claudia Gaglione
- The Mathematics of Judgment By Dustin Harris
- Fewer Appraisers. Better Appraisers. Which One Are You Going to Be? By Dustin Harris
- MY UAD 3.6 UPDATE – ACI NEWS:Only the desk top version is withdrawn. The cloud base program still works.
- 18th Annual Appraisal Summit in Las Vegas – Oct. 31-Nov. 3, 2026.
Hear what the GSEs say about Nov. 3. All the software vendors will be there – demos, questions. Network with appraisers.
HAVE FUN! OCTOBER 31 IS HALLOWEEN!!
- MBA stats: Mortgage applications decreased 6.0 percent from one week earlier
———————————————————————
GSEs New Exception for UAD 3.6 Deadline for Approved Sellers : Runs through May 19, 2027
PLUS ACI UPDATE
By Frank Andorka, Managing Editor, WorkingRE
Approved sellers who are unable to fully implement UAD 3.6 before the formal Nov. 2, 2026, deadline will be allowed to continue submitting legacy UAD 2.6 appraisal reports through May 19, 2027, according to Fannie Mae and Freddie Mac.
The GSEs will also allow resubmissions of UAD 2.6 appraisal reports through June 27, 2027. As of March 1, 2027, UAD 2.6 appraisals will no longer qualify for certain appraisal-related representations and warranties relief.
From March 1 through May 19, 2027, UAD 2.6 reports will receive a Collateral Underwriter® (CU) risk score of 999 when submitted to Fannie Mae, and their functionality will be reduced in both CU and Loan Collateral Advisor®. The GSEs encourage sellers to fully adopt UAD 3.6 as soon as possible, as this is a one-time policy exception that will not be extended.
“Many lenders are submitting UAD 3.6 appraisal reports; however, some lenders may need more time to adopt,” the GSEs said in the release announcing the exception.
Submitting a UAD 2.6 report after Nov. 2 will require explicit approval from the GSEs. To request a policy exception, a representative of the seller who is authorized to enter into a binding contract must complete the online UAD 3.6 Policy Exception Request for each GSE to which it sells loans.
To read the GSE UAD 3.6 Policy Exception documents, Click Here
====================================
ACI Update
In a perhaps unrelated announcement the day before (September 29, 2026) the GSEs announcement, ACI, an appraisal software that has been serving appraisers for decades, signaled that they were scrapping ACI Sky™ Workbench, it’s UAD 3.6-compliant appraisal report.
ACI wrote on its Facebook page:
“After careful consideration, we’ve made the decision to stop the current version of ACI Sky™ Workbench and focus our efforts on developing a significantly improved Workbench 2.0 experience, targeted for release in Spring 2027…. Access to the current ACI Sky Workbench platform will end October 9, 2026.”
Appraisers in the comments on ACI’s post reported they had been in communication with ACI and were told that “there was no interim solution in place for current ACI subscribers for completing UAD 3.6 assignments,” according to one appraiser. That same appraiser quoted an email he received as saying: “At this time, the information provided to us confirms that ACI Desktop will remain available for existing UAD 2.6 and legacy workflows, but it does not provide a confirmed interim ACI workflow for completing UAD 3.6 reports after Workbench is removed.”
To read the full WorkingRE article, Click Here
My comments on Exceptions:
THIS DOES NOT CHANGE THE NOVEMBER 2, 2026 DATE FOR ALL SELLERS/ LENDERS (WITHOUT APPROVED EXCEPTIONS) TO ONLY SUBMIT UAD 3.6 APPRAISALS.
I read an online post from an appraiser about using prediction markets like Kalshi and Polymarket for The UAD 3.6 deadline of November 2. The post had several interesting comments posted.
My opinion has been No Change for November 2 for awhile. The GSEs have seen successful appraisal and lender submissions for awhile. Now they have a way to keep the deadline with one exception.
I am not surprised. I have known for a long time that the “weak link” is the lenders not the appraisers. Appraisers just have to learn how to do the changes in reporting. Lenders have to redo their computer systems for all the changes.
I attended two event sessions where GSE representatives were speaking. I asked them about what was happening with lenders. They did not say much.
I was available to find very little help for lenders online.
What appraisers need to do – a few ideas
Learn about the new Exceptions and what is required. It is complicated.
To read the GSE UAD 3.6 Policy Exception documents, Click Here
When a lender requests an appraisal be sure you both agree on what type of appraisal will be needed: UAD 3.6 or 2.6. Get the request in writing.
To be sure, you could ask if they have an approved Exception. Then you will know they will be submitting a UAD 2.6 appraisal.
A few ideas from Doug Smith
1. Keep training on 3.6. The exception postpones the deadline for some lenders. It doesn’t retire the format.
2. Get the format in writing. On every order after Nov 2, confirm 2.6 or 3.6 in the engagement letter, especially for FHA and VA.
3. Ask lender clients whether they’ve requested the exception from one GSE, both, or neither.
4. Expect a dual-track transition. Some clients will still order 2.6 into 2027. Others will move early to avoid the March 1 penalties.
Status of FHA and VA – unknown currently. Lots of rumors and comments.
In future Friday newsletters I will let you know more, as it becomes available. It is complicated. I received notification of these new exceptions on September 30, 2026. I had limited research time available before my newsletter deadline on October 2, 2026 at 6:30 AM.
Many thanks to WorkingRE for writing this article on November 2026 about the new GSE Exception changes and ACI update!
———————————————————————
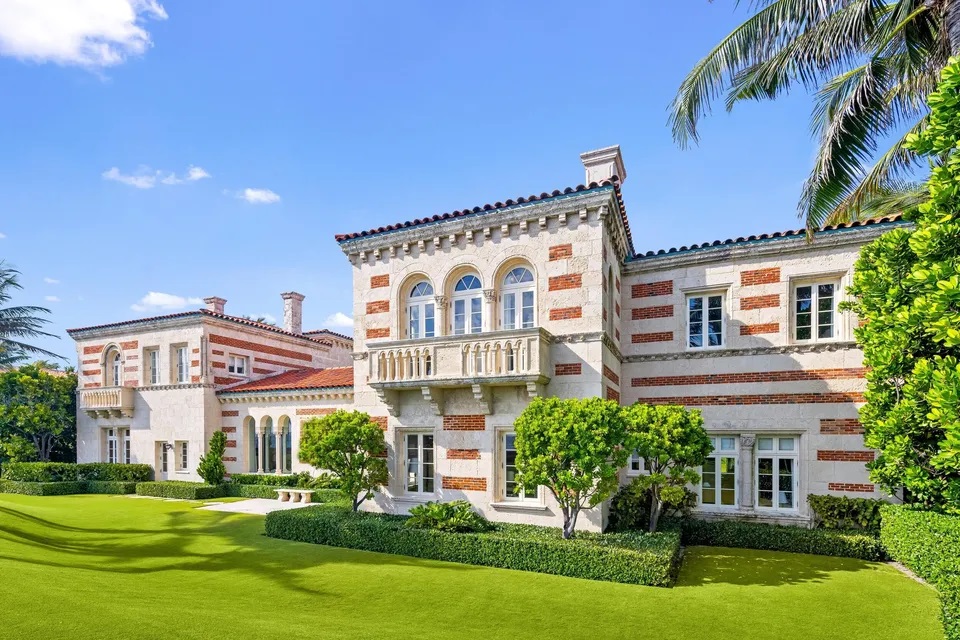
Palm Beach’s Landmark ‘Ham and Cheese House’ Is Listed for an Eye-Watering $105 Million
Excerpts: 7 bedrooms, 10.5 batha, 13,171 sq.ft., 1.05 Acre lot, Built in 1927
An historic waterfront estate, known as the “Ham and Cheese House” for its alternating brick and coquina stone designed by Maurice Fatio, has just hit the market in Palm Beach, FL, for an astonishing $105 million.
Built in 1927 for businessman Mortimer L. Schiff and his wife, Adele, the seven-bedroom megamansion is known as Casa Eleda, “a nod to Adele’s name spelled in reverse.”
Unbelievable amenities found throughout the Italian Romanesque mansion include a private tunnel leading to the beach, complete with an elevator, and a beachfront cabana with a living room, wet bar, and full bath.
Offering more than 150 feet of direct ocean frontage, the 13,171-square-foot seaside residence—which is said to be owned by Penny Antonini, wife of the late Marion H. Antonini, a former Xerox executive—has surfed to the top of the week’s most expensive homes list.
Historic highlights include arched windows, beamed cypress ceilings, multiple loggias, a formal living room with a coffered ceiling and marble fireplace, and a dining room with a beamed cathedral ceiling and marble fireplace.
Other amenities include a chef’s kitchen, a “striking” bar room, an oceanfront library, a water-facing primary sanctuary with dual baths and closets, a sitting room with a fireplace, and a balcony with expansive water views.
There’s also an exercise room, a home office, an elevator, a recreation room, and a wine cellar.
To read the listing plus Virtual tour and 34 photos Click Here
———————————————————————
Appraiser Independence
By Donna Halfpenny, an Illinois Certified Residential Real Estate Appraiser & Real Estate Broker
Excerpts: Why It Matters
Appraiser independence is mandated by state and federal laws – not a professional courtesy. Every agent, broker, loan officer, lender and AMC involved in a transaction with a lender-ordered appraisal is legally prohibited from influencing the appraiser’s value conclusion and from interfering in the appraisal process. Violations can cost you your license, trigger federal civil penalties, NAR sanctions, civil liability, and in extreme cases, criminal prosecution.1 “I didn’t know” is not a defense.
You may not contact the appraiser to advocate for a specific value, communicate the contract price as a floor or target, influence appraiser selection, threaten or pressure the appraiser, offer future business in exchange for a favorable number, post retaliatory online reviews based solely on a value you disagree with, or coordinate with other agents, lenders, AMCs or loan officers to boycott or blacklist an appraiser – the last of which may also constitute a per se Sherman Act antitrust violation.5 The agent/Broker also cannot coerce the property seller(s), buyer’s agent or the buyer(s) into not allowing an appraiser to appraise a property. You cannot exclude appraisers by name, company, or any other identifying characteristic in a purchase contract or addenda.
What Is Permitted
A listing agent or a buyer’s agent may be present during the inspection and provide factual, documented property information – permits, receipts, Plat of survey, HOA details – and present comparable sales neutrally (including both favorable and unfavorable sales). If factual errors exist in the appraisal, submit a written Reconsideration of Value (ROV) through the lender.7 The guiding question: Am I providing objective information – or trying to steer the conclusion?
To read more, Click Here
My comments: If you ever have “pressure” from real estate agents, read this article. The article is written for real estate agents. Worth reading to understand how they relate to appraiser independence. I had never seen the issue of appraiser independence from the real estate agent’s point of view. I have been a licensed real estate broker since 1985 but had never heard about these issues. I got my brokers license it to have access to MLS at that time.
———————————————————————
Are you getting too many ad-only emails?
4 ways to get only the FREE email newsletters and NOT the ad-only emails.
1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters
2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.
3. Email Archives: https://appraisaltoday.com/archives
(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.
4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.
To read more about the 4 ways, plus information on why I take ads, etc. Click here
———————————————————————
Disciplinary Proceedings: What Conduct Leads to Discipline?
By Claudia Gaglione, National Claims Counsel
LIA Administrators & Insurance Services
In the October, 2026 issue of Appraisal Today
Over the past several years, State Board investigations have made up most of the new matters reported. In 2025 alone, new complaints and investigations were reported from 39 different states.
Most of these investigations do resolve with the complaint being dismissed.
In some cases, however, that dismissal may include conditions, such as a
requirement that the appraiser complete specific education hours.
A dismissal may also be accompanied by a Letter of Warning, Caution, or
Instruction. In those letters, the investigator identifies practices observed in the report or work file that could-and often should-be improved or corrected.
Unfortunately, some investigations uncover conduct and practices serious
enough to warrant discipline.
Although discipline has been imposed in fewer than 10 percent of the matters we have supervised, the conduct behind those outcomes is significant and worth discussing.
Over the past year, the conduct and scenarios that most often led to
discipline generally fell into three categories:
- an appraiser appearing before the Board multiple times,
- multiple reports containing repeated errors,
- and an appraiser being caught in a lie
To read more about this topic, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.
If this article helped you understand State Boards Discipline, it is worth the subscription price! We are all afraid of losing our appraisal licenses or other Board problems.
—————————————————————-
Not sure if you want to subscribe?
Sign up for monthly auto renewal for $8.25!
Cancel at any time for any reason!
You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
To purchase the Monthly Appraisal Today newsletter:
www.appraisaltoday.com/order or call 510-865-8041
What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info
Cancel at any time for any reason!
You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
To purchase the Monthly Appraisal Today newsletter:
www.appraisaltoday.com/order or call 510-865-8041
The Mathematics of Judgment
By Dustin Harris
Excerpts: Judgment.
This is an important word for appraisers…even a polarizing word. That polarization often circles around a subtle tension between two types of analysis: qualitative and quantitative.
Qualitative analysis, it is often thought, is the realm of judgment. It lies at one end of the analytical spectrum, and at the other end lies quantitative analysis. Quantitative analysis is often associated with mathematics, which can feel miles away from ‘judgment’.
That polarization, as it turns out, is only a form of cognitive bias. It can feel true, but the actual truth is that qualitative and quantitative analysis cannot exist apart from one another in the formation of any value conclusion.
The Idea of Judgment
The Old French and Latin roots of the noun ‘judge’ mean essentially ‘one who declares what is right’. So, to judge as a verb is simply the act of deciding.
Appraisers make hundreds of judgments during the process of an appraisal. From the moment we walk to the front door, we are collecting and filtering immense quantities of data. Appraisers have often honed those skills of observation to such a fine point that we are barely conscious of many of those observations. Our brain simply catalogues the important and discards the unimportant. If you have ever trained another appraiser, your trainee probably surfaced many of those subconscious judgments. “Why did you take that photo? What did you see that I didn’t?” or “Why did you discard that sale, it looks similar to me?” In that case, the trainee is trying to understand how you are forming judgments about what you observe.
TOPICS INCLUDED:
The Models We Build
A Judgment Becomes a Specification
The Hidden Decisions in the Model
Now, with that said, think through the myriad of things an appraiser decides for any given assignment:
- Which properties are comparable?
- Which differences are meaningful?
- Which differences can be treated as essentially equal?
- How should I filter my data?
- What analysis methods are best?
Not a Divide, a Convergence
So, we can never choose between judgment and math. They constantly interact and even confront one another. Judgment always necessitates that we think about the math problem, and math is always there to challenge our judgment.
In other words, the real divide isn’t qualitative versus quantitative. Perhaps this leads us to a very useful question. How does our judgment shape the model, and how does the model test our judgment?
To read more, Click Here
My comments: I am always shocked at the number of appraisers who cannot do a percentage. Or,commercial appraisers, faced with a blank spreadsheet, have no idea what to do.
My high school first classes were in science and math. I loved both. I loved algebra and geometry and more classes. I had to stop at calculus as I did not understand it and did not take more math classes. I continued with science in college. I still follow many science topics. What I learned from science was the scientific method. Analyze the data. Tell the truth about what you found. Very similar to appraising.
About 15 years ago I stopped putting dollar adjustments on residential form reports, except for market conditions and unusual features that affected value (non-lender appraisals). I was doing qualitative adjustments comparing properties. Someone from our state appraisal regulators spoke at a local meeting of appraisers. She said adjustments must be proven. Not really possible often.
———————————————————————
Fewer Appraisers. Better Appraisers. Which One Are You Going to Be?
By Dustin Harris
Let me say something that will make some of you uncomfortable.
There will be a need for fewer appraisers in the future. But there will be a need for better appraisers in the future. The question you need to answer (right now, not next year) is which category you are going to be in.
Right now, most of the appraisal industry is consumed with one thing: UAD 3.6. The November 2, 2026 deadline is real, it matters, and yes, you should be preparing for it. But here is what concerns me. While appraisers are watching that storm roll in — a known storm, a manageable storm — there is a tsunami building offshore that most of them are not even looking at.
That tsunami is artificial intelligence.
So what does the future appraisal actually look like? Here is my prediction, and I want to be direct about it: inspections will be performed by homeowners, agents, third parties, or eventually robots. Comparable selection will be done by AI. Market analysis will be done by AI. Adjustments will be supported and explained by AI. The report will be generated by AI, and then delivered not to the client, but to you, the appraiser, who will review it, validate it, and sign it.
The appraisers who will struggle are still doing everything manually. They are competing on price and speed alone. They have no local brand. They are waiting for someone else to figure it out first.
Here is the truth: the window to position yourself is open right now. It will not stay open indefinitely.
We are not being replaced. We are being repositioned.
To read more, Click Here
My comments: Short and worth reading. I agree with what Dustin says. When I started my appraisal business in 1986 I wanted to be an expert for my small city. I always had non-lender appraisals. I am now committed to learning how to use the basics of AI. To start, I will be learning how to use ChatGPT.
———————————————————————
MY UAD 3.6 UPDATE
18th Annual Appraisal Summit in Las Vegas – Oct. 31-Nov. 3, 2026
At Planet Hollywood
For More Information, Click Here
Why attend?
- Hear what GSEs say and ask questions
- All the UAD 3.6 software vendors will be there – live demos, as questions, see what other appraisers say about the software
- Get some CE
- Network with other appraisers from all over the U.S.
- Have some fun in Vegas ;>
- Tax Deductible, including travel.
Co‑hosts, the National Association of Appraisers and Appraiser eLearning
Over the years I have attended many national conferences all over the U.S. They were always fun! I never regretted attending them
——————————————
ACI UPDATE short summary from Doug Smith
Only the desk top version is withdrawn. The cloud base program still works so those who tried to use the desk top have to use the cloud based version so they can still send reports in.
So it is not the end of ACI yet.
—————————————————————————–
More information in the ACI article at the top of this newsletter from WorkingRE.
—————————————
THIS IS GOOD NEWS TO ME. I HAD ALMOST GIVEN UP ON ACI!
————————————–
HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.
Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.
My comments: Rates are going up and down in 2026.
Mortgage applications decreased 6.0 percent from one week earlier
WASHINGTON, D.C. (September 30, 2026) — Mortgage applications decreased 6.0 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending September 25, 2026.
The Market Composite Index, a measure of mortgage loan application volume, decreased 6.0 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 6 percent compared with the previous week. The Refinance Index decreased 9 percent from the previous week and was 56 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 4 percent from one week earlier. The unadjusted Purchase Index decreased 5 percent compared with the previous week and was 14 percent lower than the same week one year ago.
“Mortgage rates jumped to their highest level in almost three years, pushing borrowers to the sidelines. The 30-year fixed rate increased for the sixth consecutive week to 7.3 percent, the highest rate since November 2023,” said Joel Kan, CMB, MBA’s Vice President and Deputy Chief Economist. “Mortgage applications fell by 6 percent due to the recent surge in rates, with purchase and refinance applications both declining to their slowest weekly pace since 2025. Government refinances declined 13 percent, with both FHA and VA applications experiencing double digit decreases over the week.”
Added Kan, “ARM loans, with rates around 80 basis points lower than fixed rate loans, accounted for 10.3 percent of applications, the highest share since October 2025.”
The refinance share of mortgage activity decreased to 38.3 percent of total applications from 39.3 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 10.3 percent of total applications.
The FHA share of total applications remained unchanged at 16.7 percent from the week prior. The VA share of total applications decreased to 11.9 percent from 12.0 percent the week prior. The USDA share of total applications decreased to 0.5 percent from 0.6 percent the week prior.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 7.30 percent from 7.12 percent, with points increasing to 0.75 from 0.73 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) increased to 7.27 percent from 7.15 percent, with points decreasing to 0.50 from 0.53 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 6.97 percent from 6.78 percent, with points increasing to 1.18 from 0.96 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 15-year fixed-rate mortgages increased to 6.56 percent from 6.43 percent, with points decreasing to 1.02 from 1.15 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 5/1 ARMs increased to 6.47 percent from 6.10 percent, with points increasing to 1.20 from 0.76 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.
———————————————————————
 Ann O’Rourke, MAI, SRA, MBA
Appraiser and Publisher Appraisal Today
1826 Clement Ave. Suite 203 Alameda, CA 94501
Phone: 510-865-8041
Email: ann@appraisaltoday.com
Online: www.appraisaltoday.com
We want to know what you think!! Please leave a comment.