
Newz: New Fannie Highest and Best Use Playbook, UAD 3.6 Nov. 2 and Other Deadlines??
September, 25, 2026
ARTICLE LIST:
In Order, Scroll down the page to read
- LIA AD: Conflicting Assignments and Professional Ethics
- New Fannie Highest and Best Use Playbook and Q&As
- For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat
- UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!! By Doug Smith, SRA
- MY AD: Make use of your driving time by exercising
- Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI By Dustin Harris
- MBA stats: Mortgage applications decreased 1.5 percent from one week earlier
Thanks to our Sponsor!!!
Very reasonable prices and good open rates for our ads!
————————————————————
New Fannie Highest and Best Use Playbook and Q&As
By Dave Towne
For those of you doing (or will do) the New URAR/UAD 3.6 mortgage lending reports from now into the future, you need to read and understand this new policy change from FannieMae. Because this new UAD report process also applies to FreddieMac, my presumption is they will issue a policy statement of their own with similar wording.
For the time being, here is the FNMA new policy, issued on Sept. 2, 2026: Highest and best use requirements for Uniform Appraisal Dataset (UAD) 3.6
This policy updates the highest and best use requirements for appraisal reports completed using Uniform Appraisal Dataset (UAD) 3.6.
These changes apply only to UAD 3.6 appraisal assignments to support the new Uniform Residential Appraisal Report (URAR) reporting requirements and do not apply to appraisal reports completed using legacy appraisal report forms.
We updated our policy to:
• require the property’s highest and best use, as improved or as proposed, to be a residential use, rather than requiring it to be the property’s present use;
• define present use, residential use, and subordinate use in the context of highest and best use;
• require the property to be a primarily residential one- to four-unit property, with any non-residential use subordinate to the residential use, replacing the previous “residential in nature” guidance; and
• establish the eligibility criteria and reporting requirements for one- to four-unit residential properties when the present use does not satisfy one or more of the highest and best use tests.
The UAD 3.6 Policy Supplement has been updated to reflect these changes.
Effective: This policy change is effective immediately for appraisal reports completed using UAD 3.6.
Remember, to be USPAP compliant, you can’t “just check the box” on the New URAR/UAD 3.6 data base input field (or on the Legacy forms either) to indicate ‘present use,’ and then move on. You must add a written statement in that site section comment input field explaining why you decided that is the accurate use of the property. Craft your statement to comply with the above policy.
Also remember this: if you decide the property’s H&BU is not Residential use, you must check the box “No.” In most cases, when you do that, the need to complete a full appraisal report ends at that point because the lender cannot proceed with a residential mortgage loan. Your statement needs to define what the actual use is if not Residential. Stop working on the report and contact your client to fully explain the current situation. Let them determine how to proceed.
—————————————————————–
What is in Fannie’s New The Highest & Best Use 25 page Playbook (Per Fannie)
• This playbook provides key concepts and illustrative scenarios to help industry participants better understand how the results of the highest and best use (HBU) may affect loan eligibility.
• Each scenario presents a complex highest and best use question based on the specific circumstances of a subject property. While every property has its own unique characteristics and circumstances, which may lead to different conclusions, these scenarios are designed to demonstrate how you can apply Fannie Mae policy consistently across a range of situations. They are intended to provide practical guidance and support informed, policy-compliant decision-making.
• A resolution is provided for each scenario, along with the appraiser and lender responsibilities with relevant Fannie Mae Selling Guide Supplement: Uniform Appraisal Data (UAD) 3.6 Policy resources.
• The Highest and Best Use Frequently Asked Questions document addresses common questions related to present use, highest and best use, mixed-use properties, analysis of subordinate uses, comparable sales, the URAR, and loan eligibility. The document is available separately and linked throughout the Playbook for easy reference.
To read the Highest and Best Use Playbook, Click Here
To read the separate FAQ document, with 27 Q&As, Click Here
My comments: Many thanks (again) to Dave Towne for writing a summary of the 25 page document at the top of this article. To subscribe to his regular emails, send an email to dtowne@fidalgo.net . Say that you want to subscribe to his list. I have been subscribing for many years.
————————————————————————
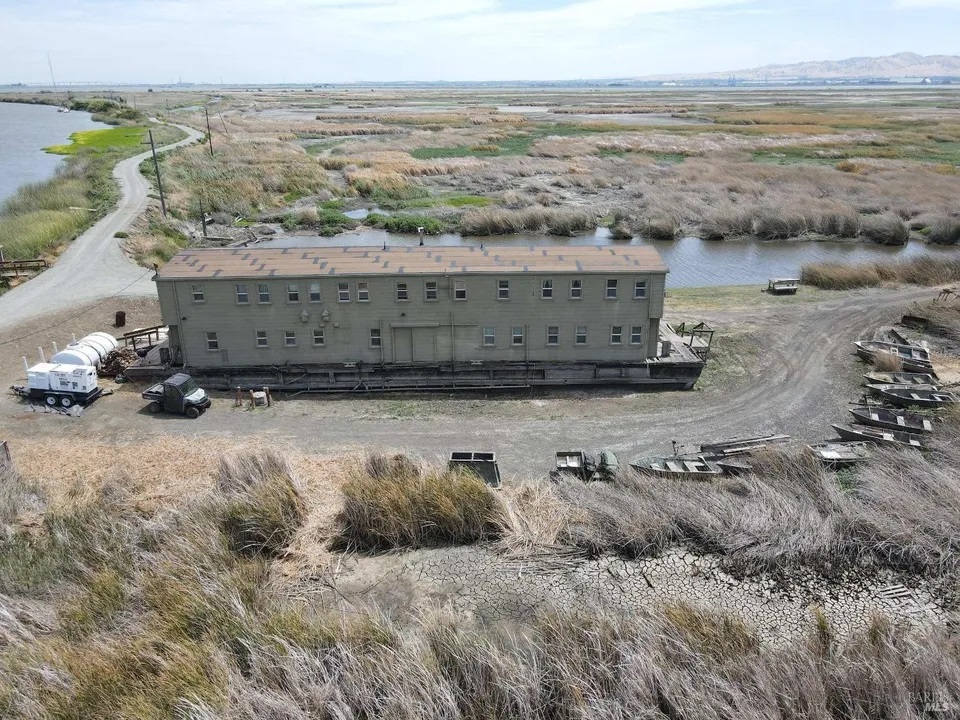
For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat
Excerpts: 16 bedrooms, 5,OOO sq.ft., 399.95 acre lot.
400-acre marsh property which has served as hunter’s have for more than a century has hit the market for $1.5 million.
Concord Farms Duck Club in Suisun City, CA consists of a 16-bedroom, three-bathroom clubhouse.
“It’s just a place where these guys can go out and shoot ducks. It’s been going on for like 100 years plus,” explains listing agent John Ward with California Outdoor Properties. He adds that the hunters take boats out to duck blinds in the marsh where they wait.
“You have your duck call and your shotgun, and you start blowing your whistle or your duck call, and hopefully some birds come in.”
Ward says there are about 160 duck clubs in the Suisun Marsh area, with many of them dating back more than a hundred years. Hunters buy memberships in the clubs.
“There’s just kind of a changing of the guard a little bit now with some of the older guys just getting older,” Ward says.
“[With] this particular club, the members took a vote and decided whether they were going to make an effort to try to get new blood into the club, or [if] they were all kind of ready to hand the torch to the next group. So, they just decided to sell the property.”
The property consists of a 16-bedroom and three bathroom clubhouse, a building which has its own history.
“It’s basically an old barge. They had crews that came in 100 years ago to help build the levees and do a lot of the work out there,” he explains. “So some of these barges turned into duck club houses because they built the levees around them. The men back 100 years ago used those [barges] for their quarters to sleep at night.”
That clubhouse is where the hunters gather after they reach their limit of seven ducks.
“They’ll take their boat back to the club and then make a make a breakfast or a brunch or whatever, and then usually the guys just kind of hang out in the club, and watch college football, watch the NFL, or whatever they want to watch, and it’s usually just kind of a hang [out place].”
My comments: My first appraisal job was in Northern California at the Butte County Assessor’s office. I knew nothing about duck hunting. Many of the guys working there were avid duck hunters, one of the reasons they worked there. I had heard about duck clubs but had never seen one. Fascinating! I learned how they did the hunting, but never tried it.
To see the listing, with many photos, Click Here.
————————————————————————
UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!!
By Doug Smith, SRA
Excerpts: November 2 is not the deadline for the appraiser to deliver a UAD 2.6 appraisal to the lender or AMC. It is the deadline for a new UAD 2.6 appraisal to have already made its initial submission to UCDP.
That distinction matters.
An appraiser could complete a legacy UAD 2.6 appraisal before November 2 and deliver it to the client before November 2—and it could still be too late. If its initial submission to UCDP occurs on or after November 2, UCDP will return a Fatal message and a “Not Successful” status.
The GSE transition timeline provides a remarkably clear example. A UAD 2.6 appraisal is ordered on October 1. It is not initially submitted to UCDP until November 5. The result: Not Successful. The timeline states that UAD 2.6 appraisals must be submitted to UCDP before the mandate or converted to UAD 3.6.
So an appraiser looking at November 2 as “the last day I can finish a legacy appraisal” is looking at the wrong date.
The appraiser’s practical deadline has to be earlier.
To read the full article, Click Here
Editor’s Note: There was no link available for this article online. It is posted on my blog. Every blog post has a link. Putting it on a separate web page is a hassle. I have my weekly email newsletters back to 2012 posted every week on my blog. I will be doing this for articles that are too short for my monthly newsletter, but are very interesting.
My comments : Read this article if you will be doing UAD 3.6 Appraisal reports. UAD 3.6 vs. 2.6 and many other topics are covered. I had never read a detailed description of all the changes and deadlines when UAD 3.6 is adopted. I had just read about “bits and pieces”, and rumors. Thanks to Doug for writing this.
————————————————————————
Are you getting too many ad-only emails?
4 ways to get only the FREE email newsletters and NOT the ad-only emails.
1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters
2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.
3. Email Archives: https://appraisaltoday.com/archives
(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.
4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.
To read more about the 4 ways, plus information on why I take ads, etc. Click here
————————————————————————
Make use of your driving time by exercising
Appraising is a fairly sedentary job, with most of the time spent sitting in a
car or at a desk. Do you take time to exercise every day? Do feel stressed out
when you are running late for an appointment? Do you feel stressed as a deadline approaches?
One of the best and worst times in appraising is driving. Working out in the
field is what attracted many of us to appraising, including myself. But the time
spent driving is unproductive time.
There are so many stresses today. Exercising is a great stress reducer!
Although the exercises below are for driving, many can also be used in your
office.
I have a personal trainer and exercise almost every day at home and a gym
close to my house. I always listen to podcasts while exercising. Exercising while driving takes no extra time!
Shoulder exercises
Do “shoulder shrugs” where you bring your shoulders up to your ears, one at
time, then both. Drop your shoulders quickly, focusing on the relaxed feeling.
Arm and hand exercises
For steering wheel exercises, put your hands in the 10:00 and 2:00 position.
Squeeze the steering wheel tight, pushing inward for 2-3 seconds, then release.
Keep a relaxed grip on your steering wheel, to keep tension from moving up
to your face, neck, and shoulders. One at a time, lift your fingers off the steering wheel, then lightly put them back.
To read more about this topic, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.
If this article helped you learn how to do exercising while driving, it is worth the subscription price!
————————————————————————
Cancel at any time for any reason!
You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
To purchase the Monthly Appraisal Today newsletter :
www.appraisaltoday.com/order or call 510-865-8041
What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info
Cancel at any time for any reason!
You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
To purchase the Monthly Appraisal Today newsletter:
www.appraisaltoday.com/order or call 510-865-8041
————————————————————————
The 3.6 Rollout: Chaos Now, Clarity Later?
By Logan Dorman · Published September 18, 2026 · Updated
Excerpts: The 3.6 rollout has raised more questions than answers, leaving the industry navigating a landscape that remains unclear.
UAD 3.6 has dominated the appraiser conversation on LinkedIn, yet the irony is that almost nobody truly understands it. That isn’t the fault of appraisers. Even the most experienced professionals and the people positioned as “3.6 experts” have more questions than answers. I recently listened to a panel of appraisers I respect immensely, and even they acknowledged the gaps. The truth is simple: people may be preparing for 3.6, but nobody is fully ready. Admitting that doesn’t make anyone less competent. It reflects the reality of the rollout.
What the industry does have is an abundance of opinions. Some defend the new structure, others condemn it. While the underlying intent of 3.6 may have merit, the rollout has been undeniably chaotic. Functional software is lagging, training has been insufficient, and critical questions remain unanswered. These issues trace directly back to the decision‑makers who pushed the system forward without adequate preparation. But assigning blame won’t solve the problem. The only productive path forward is patience.
There is, however, a positive outcome that has received little attention.
UAD 3.6 will separate the wheat from the chaff. AMCs that rely on low‑fee, high‑volume “rubber stamp” appraisers will struggle because those appraisers will not be able to hide substandard work behind the new level of required detail. While the purpose of 3.6 is to improve the quality of the appraisal report, an important side effect is that it will also highlight the quality of the appraiser. Not all appraisers operate at the same level, and 3.6 will make that impossible to ignore.
To read the article and over 50 appraiser comments, Click Here
My comment: Good to read something positive about UAD 3.6!
————————————————————————
Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI
By Dustin Harris
Excerpts: When was the last time a private client told you they actually enjoyed reading your appraisal report? Not “thanks, got it.” Enjoyed it. Sat down, read it, understood it, maybe even showed it to somebody.
I’m guessing never. And I don’t blame the client one bit.
Our reports are built for underwriters and algorithms and secondary market compliance. That’s fine, that’s what they’re for. But when a homeowner, or a divorce attorney, or an estate executor gets that same 35-page PDF with the grids and the boilerplate and the standardized fields, they don’t feel informed. They feel buried.
An interactive web report flips all of that. You’re not handing them a document anymore, you’re meeting them where they already live, which is on their phone, scrolling.
So what does this actually look like? Picture sending your client a password protected link along with their formal report. They open it up and right at the top is a great photo of the property with your value opinion and effective date front and center, no hunting required.
To read more, Click Here
My comments: Very interesting! Definitely worth trying. No UAD 3.6 for non-lender appraisals!
————————————————–
NO UAD 3.6 UPDATE THIS WEEK FROM ME. SEE DOUG SMITH’S ARTICLE ON “MANY DEADLINES!” ABOVE
————————————————————————
HOW TO USE THE NUMBERS BELOW.
Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.
Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.
My comments: Rates are going up and down in 2026
———————————————————————–
Mortgage applications decreased 1.5 percent from one week earlier
WASHINGTON, D.C. (September 23, 2026) — Mortgage applications decreased 1.5 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending September 18, 2026. Last week’s results included an adjustment for the Labor Day holiday.
The Market Composite Index, a measure of mortgage loan application volume, decreased 1.5 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 9 percent compared with the previous week. The Refinance Index decreased 3 percent from the previous week and was 62 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 1 percent from one week earlier. The unadjusted Purchase Index increased 9 percent compared with the previous week and was 11 percent lower than the same week one year ago.
“Mortgage rates vaulted higher last week, with the 30-year fixed rate at 7.12 percent – the highest level since May 2024. With fixed rates much higher, more borrowers opted for ARMs, with the ARM share reaching 9.8 percent, as rates for 5/1 ARMs were more than a percentage point lower than those for fixed rate loans,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “Applications for both refinance and purchase loans declined further last week, noting that the comparison is to the week that included the Labor Day holiday. With this week’s decline, the pace of refinancing fell to its slowest pace since February 2025.”
The refinance share of mortgage activity decreased to 39.3 percent of total applications from 39.4 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 9.8 percent of total applications.
The FHA share of total applications decreased to 16.7 percent from 16.9 percent the week prior. The VA share of total applications decreased to 12.0 percent from 12.4 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.4 percent the week prior.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 7.12 percent from 6.97 percent, with points increasing to 0.73 from 0.72 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) increased to 7.15 percent from 7.03 percent, with points decreasing to 0.53 from 0.59 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 6.78 percent from 6.62 percent, with points increasing to 0.96 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 15-year fixed-rate mortgages increased to 6.43 percent from 6.30 percent, with points increasing to 1.15 from 0.98 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 5/1 ARMs decreased to 6.10 percent from 6.23 percent, with points decreasing to 0.76 from 0.99 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.
The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.
————————————————————————

Ann O’Rourke, MAI, SRA, MBA
Appraiser and Publisher Appraisal Today
1826 Clement Ave. Suite 203 Alameda, CA 94501
Phone: 510-865-8041
Email: ann@appraisaltoday.com
Online: www.appraisaltoday.com
We want to know what you think!! Please leave a comment.