Artificial Intelligence Will Not Replace Appraisers

Newz: Freddie ADU Guide, AMCs, AI and Appraisal Photos, FHA QC Changes

September 18, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Expanding Intended Users? Not So Fast
  • A Practical Guide to Appraising Accessory Dwelling Units (ADUs) By Freddie Mac
  • Artificial Intelligence Will Not Replace Appraisers By Tony Pistilli
  • Former 1847 Ohio Jail Goes Under Offer for $400K: How One Family Turned Inmate Cells Into Pantries and Closets
  • MY AD: The Appraisal Triangle: Knowledge. Experience, Aptitude and Attitude
  • HUD Rewrites FHA Appraisal Quality Control by Kenneth J. Mullinix
  • If the Management Model Is So righteous, Spread It Around (AMCs)
  • MY UAD 3.6 UPDATE How the get the list of GSE validated UAD 3.6 software vendors, Facebook page to read appraiser comments on UAD 3.6 software.
  • MBA stats: Mortgage applications decreased 4.1 percent from one week earlier
A Practical Guide to Appraising Accessory Dwelling Units (ADUs)

By Freddie Mac

Excerpts: Sample Topics:

Appraisal Considerations:

Firstly, an appraiser can’t simply ignore an ADU. If the determination is made that additional finished area qualifies and meets the definition of an ADU, there are some practical steps the appraiser must take in the analysis.

Appraisal Development:

The appraiser will need to determine any effect the ADU has on the market value or marketability of the subject property. The appraiser’s analysis must be documented in the appraisal report and conclude whether an adjustment is supported for the ADU (remembering that the conclusion for no adjustment also requires market support).

Allowable Flexibility:

A good best practice for any appraiser is to reference and use Freddie Mac resources and published appraisal guidelines, which detail the steps an appraiser may take when valuing a property with an ADU. If a subject property ADU complies with zoning and land use requirements, the appraisal report must include at least one comparable sale with an ADU. If not available, then the appraiser may consider an older sale from the subject’s market or a competing market. The appraiser may also expand the search and comparison beyond just three sales, including pending contract sales or listings to justify the support for adjustments.

My comments: If you appraise ADUs, or are just curious, read this article from Freddie Mac!

To read more, Click Here

My comments: If you appraise properties with ADUs, read this detailed and practical advice for appraisers.

————————————————————-
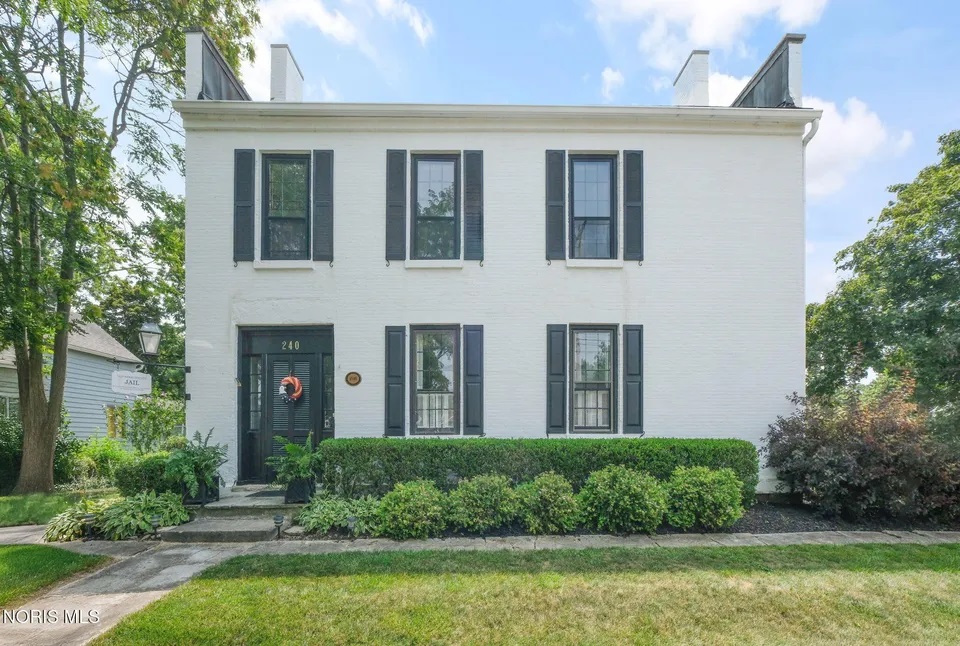
Former 1847 Ohio Jail Goes Under Offer for $400K: How One Family Turned Inmate Cells Into Pantries and Closets

Excerpts: 3 bedrooms, 3 baths, 2,690 sq.ft., 0.5 acre, built in 1947

When most people sit down for Sunday dinner, they aren’t staring directly into 19th-century jail cells. But for listing agent Caroline Hoffmann, having remnants of 19th-century law enforcement in the dining room was just part of normal family life.

The historic Old Wood County Jail at 240 W Indiana Ave in Perrysburg, OH—currently under contract with a contingent offer on its $400,000 listing—isn’t just an unusual piece of real estate to Hoffmann. It’s her family’s legacy.

“I think the fact that it still has the original jail cells intact is what really gets people’s attention all the time,” Hoffmann says. “Everybody wants to know if it’s haunted. It’s not.”

While the 2,960-square-foot brick property was originally constructed in 1847 and functioned as a county lockup until 1870, its modern history is deeply personal. The building served as the city jail until 1899, after which the public record goes quiet until 1918. That’s when Hoffmann’s family history with the structure began.

“My great-great-grandfather bought it from his brother-in-law in 1924. His brother-in-law had purchased it in 1918,” Hoffmann explains.

The structure was subsequently converted into three individual apartments—one on the lower level and two on the upper floor, each configured with one bedroom, a bathroom, and a small kitchen. Over the decades, it operated as a steady investment property.

To read the listing, with a floor plan and photos, Click Here

————————————————————

Artificial Intelligence Will Not Replace Appraisers

But appraisers who understand and use it responsibly will replace those who do not

By Tony Pistilli

Artificial intelligence has officially moved from the magical and mysterious into the mainstream of appraisal practice. Among the most significant forms of artificial intelligence entering the appraisal profession today is computer vision. This technology allows computer models to “see” pictures in ways that once, only human eyes could.

For many appraisers, this will raise understandable questions: How does this technology actually work? What are my obligations under USPAP? And how do I use artificial intelligence without getting in trouble with the state board?

And of course, many will also ask: If I use this, am I only contributing to the elimination of appraisers?

The answers point to a simple conclusion: Artificial intelligence does not replace appraisers. It rewards those who understand and use it well.

How Computer Vision Is Trained to “See” What We See

Computer vision is a subset of artificial intelligence that enables computers to extract information from pictures. This is much like what appraisers do today: We see a fireplace, write it down, and eventually type it into the form.

The Enduring Relevance of Appraisers

Virtually every respected profession has faced similar technological sea changes. Accountants weren’t replaced by Excel spreadsheets, radiologists weren’t replaced by imaging software, and attorneys weren’t replaced by online databases. These professionals got better, faster, and more accurate at analysis, diagnostics, and legal research. Their value remained intact.

Appraisers will be no different.

To read more, Click Here

My comments: Good analysis. The author has a software company using AI on photos and is very knowledgeable.

—————————————–

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday Posted by noon Friday

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page. NOTE: the popular ads with liability tips are below the first topic on my blog posts.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the left of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block. The newsletters have abbreviated titles, taken from their blog posts.

To read more about the 4 ways, plus information on why I take ads, etc.

Click here

—————————————————————-

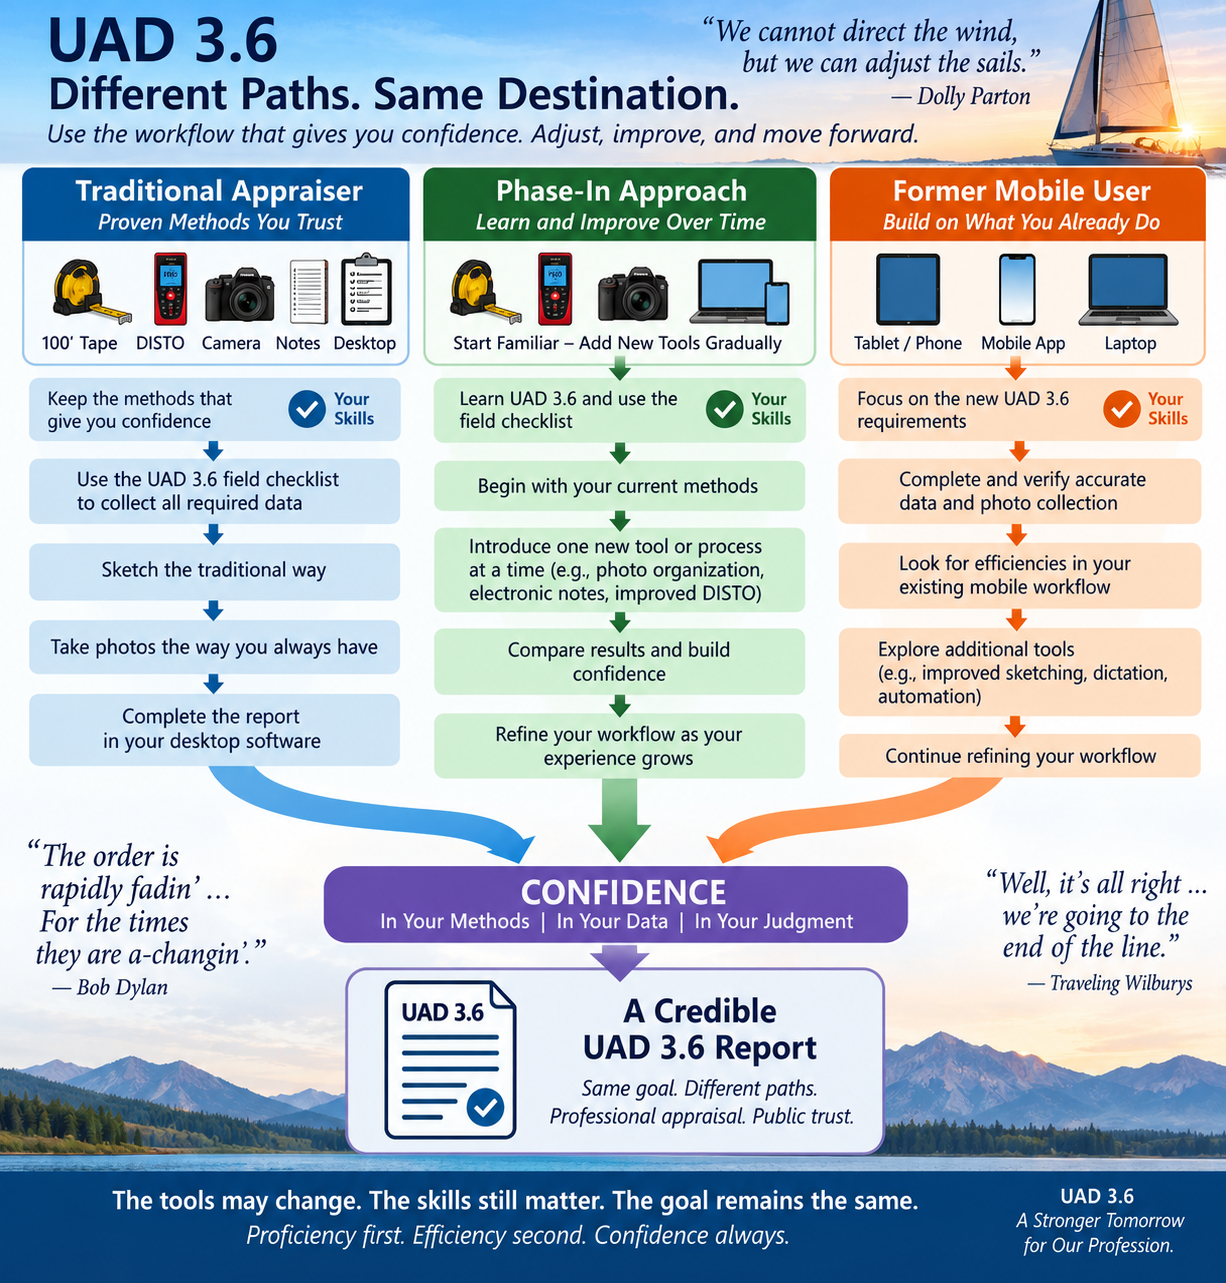
Appraisers, at this time must accept that “the order is rapidly fadin” and the whole appraisal world is headed to new horizons. The traditional elements of knowledge, experience and aptitude qualities require sharpening and enhancement,

By Doug Smith, SRA

In the September 2026 issue of Appraisal Today

Editor’s comment: Doug did the above very good image himself in Chatgpt!
He will be writing a very understandable article on how to use Chatgpt for appraisers for the November 2026 issue.

Excerpts: The traditional appraisal practice is represented by a three-sided triangle with two sides of knowledge and experience on a foundation of aptitude.

As important as all three of these are in a successful practice, attitude

remains the driving force. Attitude is the main requirement at this moment in time as the profession has always rewarded those willing to learn.

Appraisers, at this time must accept that “the order is rapidly fadin” and the

whole appraisal world is headed to new horizons. Appraisers, at this time must accept that “the order is rapidly fadin” and the

whole appraisal world is headed to new horizons.

The traditional elements of knowledge, experience and aptitude qualities require sharpening and enhancement,

Artificial Intelligence, UAD 3.6, new inspection technology, cloud computing, tablets, mobile workflows, XML reporting, and appraisal waivers are converging almost simultaneously. It is understandable that many appraisers feel overwhelmed.

Social media pages and discussion groups have become filled with

questions, software concerns, and uncertainty. Yet every profession reaches

moments like this. The issue is not whether change is occurring. The issue is how we respond to it. During times of uncertainty, the easiest decision is to make no decision.

Yet history shows that periods of greatest change reward those who

continue learning and adapting rather than standing still. Appraisers are uniquely trained to reconcile conflicting evidence. That is what the sales comparison approach teaches every day. Appraisers don’t wait for perfect comparable sales; they analyze imperfect information and arrive at a supported opinion.

Perhaps the greatest irony is that appraisers should be among the people

least afraid of uncertainty, because uncertainty is the environment in which they have always worked. Knowledge, experience and aptitude qualities require sharpening and enhancement,

To read the very interesting full article, plus 3+ years of previous issues, subscribe to the paid Appraisal Today at www.appraisaltoday.com/order .

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason! You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

What’s the difference between the Appraisal Today free Weekly email newsletter and the paid Monthly newsletter? Click here for more info.

————————————————–

If you are a paid subscriber and did not receive the

September, 2026 issue emailed on

Tuesday, September 2, 2026 please email info@appraisaltoday.com, and we will send lt to you. You can also hit the reply button. Be sure to include a comment requesting it. Or, call 510-865-8041

—————————————————————–

HUD Rewrites FHA Appraisal Quality Control

by Kenneth J. Mullinix

Excerpts: Significant changes to the appraisal profession rarely arrive with headlines. Instead, they appear in agency guidance, revisions to underwriting manuals or updates to long-standing administrative procedures. Although these policy changes often receive little public attention, they can significantly influence how residential appraisers, lenders and appraisal management companies conduct business.

HUD Mortgagee Letter 2026-10 is one such change. Effective June 23, the U.S. Department of Housing and Urban Development (HUD) eliminated the long-standing requirement that FHA-approved lenders obtain appraisal field reviews on at least 10% of selected quality control loan files. While the revision appears procedural, it represents one of the most significant changes to FHA appraisal quality control in recent years.

More importantly, the Mortgagee Letter reflects a broader shift in regulatory philosophy — from prescribed review requirements to risk-based quality management that gives lenders greater flexibility while maintaining accountability for appraisal quality. For residential appraisers, it also provides insight into the future direction of federal appraisal oversight.

The New Rule

Mortgagee Letter 2026-10 eliminates the mandatory 10% sampling requirement. Instead of requiring appraisal field reviews on a fixed percentage of quality control files, HUD now permits lenders to determine whether a field review is warranted based on their assessment of collateral risk.

Why HUD Made the Change

HUD’s rationale is both practical and economic. According to the agency, mandatory appraisal field reviews often produced limited additional benefit while imposing measurable costs on lenders. HUD estimated that eliminating the requirement could save the mortgage industry approximately $3.3 million annually. What It Means for Appraisers

Some appraisers may initially view the revised policy as a reduction in appraisal oversight. It is not.

Every FHA appraisal remains subject to lender review, underwriting analysis, automated quality control systems and potential post-closing examination. USPAP obligations and FHA reporting requirements remain unchanged, and appraisers remain responsible for producing credible, well-supported opinions of value.

For experienced appraisers, the practical impact should be minimal. Sound market analysis, logical adjustments, thorough documentation and transparent reporting remain the best defense against any form of appraisal review.

To read more, Click Here

To read the Mortgagee Letter 2026-10 Click Here

My comments: Detailed article. If you do FHA appraisals, check it out.

—————————————————————-
If the Management Model Is So righteous, Spread It Around (AMCs)

Excerpts: If the management model were truly noble, it would not stop at appraisers. Yet somehow the babysitting service never expands beyond us.

Once upon a time there was a profession that stood between the public and chaos. For forty five years I watched that profession take every punch the mortgage world could invent. Every market dip, every delayed closing, every regulatory shift, every headline looking for a villain landed on the appraiser. We carried it because we understood the role. We were the guardrail.

But when the word racist became fashionable, that was the breaking point. Appraisers were already the most over regulated people in the entire mortgage process. It was absurd to pretend that lawyers, originators, brokers, realtors, AMC’s and bankers were spotless while appraisers alone were the problem. That conclusion was not logical. It was convenient. And it became the narrative.

And here is the part that never gets said out loud. Why are appraisers the only ones being managed? Why is there an entire shadow industry built to supervise, monitor, and skim off the work of one profession while lawyers, originators, bankers and everyone else walk free? If management companies are such a brilliant idea, why not apply them to the legal world? Why not assign babysitters to originators? Why not force bankers to hand over most of their fee to a management company that checks their ethics and competence? If the management model is so righteous, spread it around. But it never is. It is only imposed on the appraiser.

To read more plus some interesting appraiser comments, Click Here

My comments: Short but interesting. I love the discussion of why appraisers? My answer: We have no large national association, such as NAR to speak for us.


My UAD 3.6 Update

How the get the list of GSE validated UAD 3.6 vendor software companies.

Go to https://singlefamily.fanniemae.com/integrated-vendor-list

Scroll down to Fannie Mae Product Interface

Select (scroll down) UAD 3.6 appraisal software provider then click Search.

I have included this link in other newsletters, if you can’t find the last time I included it. I check it almost every day to see what software is validated.

Fannie requires validation for uploaded appraisals. It does not mean that all the software components are completed and ready to go, such as inspection apps and AI.

As of 9/14/26 there were 10 validated vendor software approved. About 24 vendors total are anticipated.

Any UAD 3.6 software you are considering using MUST BE VALIDATED OR YOUR APPRAISALS WILL NOT BE ACCEPTED BY THE GSES.

——————————————————————–

Facebook group to read appraiser comments on UAD 3.6 software. : “Appraisers Perspective of UAD 3.6” Search for the vendor name or the software name, such as Total. My “go to” place to see what appraisers are saying. I go there regularly.

————————————————————————

HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, Click Here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down. We are all waiting for rates to drop lower in 2026.

————————————————————————-

Mortgage applications decreased 4.1 percent from one week earlier

Mortgage applications decreased 4.1 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending September 11, 2026. This week’s results include an adjustment for the Labor Day holiday.

The Market Composite Index, a measure of mortgage loan application volume, decreased 4.1 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 15 percent compared with the previous week. The Refinance Index decreased 9 percent from the previous week and was 65 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 1 percent from one week earlier. The unadjusted Purchase Index decreased 13 percent compared with the previous week and was 19 percent lower than the same week one year ago.

“Ongoing market concerns over spiking energy prices, persistently high inflation, and future monetary policy pushed bond yields and mortgage rates higher last week. As the 10-year Treasury inched closer to the 5 percent mark, mortgage rates followed and were almost 7 percent. The 30-year fixed rate at 6.97 percent was at its highest level since May 2025,” said Joel Kan, CMB, MBA’s VP and Deputy Chief Economist. “After adjusting for the Labor Day holiday, purchase applications dipped relative to the week prior as higher mortgage rates caused many buyers to pause their purchase decisions. The current level of rates also eliminated much of the benefit to refinance for many borrowers, resulting in declines in conventional, FHA, and VA refinance applications.”

The refinance share of mortgage activity decreased to 39.4 percent of total applications from 40.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity decreased to 8.4 percent of total applications.

The FHA share of total applications decreased to 16.9 percent from 17.2 percent the week prior. The VA share of total applications increased to 12.4 percent from 12.0 percent the week prior. The USDA share of total applications decreased to 0.4 percent from 0.5 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 6.97 percent from 6.85 percent, with points increasing to 0.72 from0.67 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750)increased to 7.03 percent from 6.74 percent, with points decreasing to 0.59 from 0.63 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 6.62 percent from 6.53 percent, with points decreasing to 0.85 from 0.86 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 6.30 percent from 6.17 percent, with points increasing to 0.98 from 0.93 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs increased to 6.23 percent from 5.82 percent, with points increasing to 0.99 from 0.84 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

———————————————————–

Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
Defending Adjustments for Appraisers

Newz:  GSEs Request Feedback on UAD 3.6, Defending Adjustments

September 4 , 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Too Late for a Reconsideration of Value
  • How to Defend Adjustments in Appraisal Reports
  • $112 Million Laguna Beach Mansion With a Private Library and a Rotating Bed in Primary Suite Could Become Priciest Home Ever Sold in Orange County
  • GSEs Request Appraiser Feedback on UAD 3.6
  • MY AD: How AI Can Help Residential Appraisers and Why Appraisers Will Always be Needed By By David Galatto
  • First the Borrower Fee. Now the Appraiser Compensation in Court By Kenneth J. Mullinix
  • The part of the process appraisers never see, and the reason your file keeps coming back
  • UAD 3.6 UPDATE – Inspection Checklist, New Survey: UAD 3.6 mandate is Nov. 2nd. Are you ready for it?,
  • MBA STATS: Mortgage applications increased 0.8 percent from one week earlier

————————————————————————–

How to Defend Adjustments in Appraisal Reports

When someone questions an adjustment, many appraisers respond, “It’s based on market data” or “my experience in the market.” These statements might be true, but they don’t support the adjustment. They just state where it came from.

Appraisal reports are similar to scientific papers. A scientist can’t write “Based on my experiments, the hypothesis is correct” and expect peer review to accept it. Scientists need to share their methodology, summarize their analysis, and support their conclusions.

The same applies to appraisal adjustments. Saying you used market data is like saying you conducted an experiment. It’s just the starting point. Your report needs to summarize how you analyzed the data and how it supports that specific adjustment.

Without this documentation, you haven’t provided credible analysis. You’ve stated an unsupported opinion, regardless of your experience.

You need a clear path from market evidence to the number on your grid. Defending appraisal adjustments isn’t one perfect technique. It’s about using multiple, credible methods, explaining your logic, and sequencing your work so it aligns with how the market behaves and with USPAP.

Below is a practical, step-by-step approach you can put to work right away.

Start with the Right Sequence

Before you calculate any adjustment, get the order right. In practice, you should follow this sequence:

  • Apply transactional adjustments:
  • Real property rights conveyed
  • Financing terms
  • Conditions of sale
  • Expenditures made after purchase
  • Market conditions (time)
  • Apply property adjustments:
  • Location
  • Physical characteristics (e.g., finished square footage, bathrooms, garages, condition, quality)

Transactional adjustments affect the overall transaction price, and each adjustment creates a new base for the next one. They answer the question, “What would this comparable have sold for under typical terms on my effective date?”

These adjustments normalize the sales by removing distortions from unusual financing, non-market conditions, or time differences.

Equalize Market Conditions Before You Compare

Read more!!

Recent Executive Orders Affecting Appraisers

Newz: Recent Executive Orders Affecting    Appraisers, When Appraisers Take the Stand

June 12, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: A case of forgery
  • Recent Executive Orders: Threat, Opportunity, or Both for Appraisers? By Kim Perotti, AXIS AMC
  • $22.8 Million Aspen Home With Its Own Private Waterfall Feels Like a Real-Life Fairy Tale
  • MY AD: If the Standards Are Uniform, Why Isn’t Your License? By Thaddus Dawson, Jr., CG
  • When Appraisers Take the Stand By By David C. Wilkes, Esq., CRE, FRICS and Kevin M. Clyne, Esq., CRE
  • Agents, Are You Using AI to Price Your Listings? By Tom Horn
  • 10K Appraisers. Policy and Advocacy Day, By 10K Appraisers Foundation
  • MBA: Mortgage applications increased 10.8 percent from one week earlier

Recent Executive Orders: Threat, Opportunity, or Both for Appraisers?

By Kim Perotti, a founding partner of AXIS AMC

Excerpts: In March 13, 2026, President Trump signed two Executive Orders that together amount to a clear message for our profession: build more houses, make credit easier, and get the valuation piece done faster and cheaper. We think it’s critically important that our industry discuss the implications.

The two orders are:

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION

AND PROMOTING ACCESS TO MORTGAGE CREDIT

While they are not “about” appraisers, the Executive Orders will absolutely reshape the environment in which we work. Appraisers who treat these as background noise will find the ground shifting under their feet. Those who read them as a roadmap can pick their spots and come out stronger and, more importantly, help shape how they are put into practice.

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION:

Faster, Cheaper Construction – What That Really Means for Your Desk

PROMOTING ACCESS TO MORTGAGE CREDIT: Faster, Cheaper Valuations – Where the Squeeze Shows Up – Second Order

The second order takes direct aim at how loans—and valuations—get done. The theme is unmistakable: streamline, digitize, and de-emphasize technical compliance.

For appraisers, here are the potential realities:

More alternative valuation products: Regulators are being encouraged to expand the use of AVMs, desktop, and hybrid appraisals and reduce full appraisal requirements on low-risk and small-balance loans. You should expect more hybrid and desktop requests and data-only products as well as a clearer dividing line between high-volume, low-margin work and complex, higher-risk assignments.

Pressure on fees and turn times: Agencies are being asked to set “clear appraisal timelines” and cut costs and therefore lenders will likely lean harder on speed and price whenever a waiver, AVM, or hybrid is allowed, and traditional assignment ordering will have to justify itself on risk grounds.

Changes in who can appraise and how: The order invites simplification of appraiser qualification requirements. Easier entry could mean more competitors and lenders may fill low-fee niches with less-experienced personnel or non-traditional vendors.

If your business is built primarily on simple, low-risk assignments, this is a direct competitive challenge.

Alignment of FHA and VA rules: HUD and VA are asked to align standards where risk is comparable, clarify what truly requires pre-closing repairs vs. what’s cosmetic, and expand post-closing repair flexibility.

That could change the frequency and scope of “subject to” conditions, reduce some friction and disputes around FHA/VA appraisals, and make your judgment about safety vs. cosmetic issues more visible and important.

In summation, this order calls for more technology and alternatives, more pressure on traditional appraisals, and more segmentation of valuation products by risk level.

A Clear Fork in the Road for Appraisers

Taken together, these two Executive Orders point in one direction: more volume, more complexity at the edges of the market, and more pressure to commoditize anything that looks “low risk.” Together they create a fork in the road for real estate appraisers:

If you stay in the lane of interchangeable, low-complexity assignments, you will feel the squeeze—from technology, from relaxed standards, and from new entrants.

If you lean into complexity—new construction, manufactured and modular, fringe markets, environmental and hazard issues, FHA/VA nuance—you become harder to replace, not easier.

This doesn’t mean abandoning efficiency or refusing alternative products. It means being fluent in hybrids and desktops so you can decide which work makes sense for you, positioning yourself as the expert when a lender can’t responsibly rely on an AVM or a waiver, and building documented expertise in the exact areas these orders will expand.

To read more, Click Here

My comments: Definitely worth reading. All about what this means for appraisers in detail. The best analysis for appraisers I have read about this executive order. The author is definitely an “insider” as she is Co President of AXIS, a long time AMC. When I wrote one of my first articles on AMCs, I interviewed AXIS.

Read more!!

Adapt or Step Back? How UAD 3.6 Is Forcing a Career Decision for Appraiser

Newz: UAD 3.6 Adapt or Step Back,

Getting Started With AI

May 29, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Too Late for a Reconsideration of Value
  • Adapt or Step Back? How UAD 3.6 Is Forcing a Career Decision for Appraisers, By Rachel Mann
  • 109-Year-Old ‘Boathouse’ That Appears To Float on Washington Canal at High Tide Hits the Market for $2.1 Million
  • Getting Started with AI for Appraisers
  • MY AD: Loose Lips Cause Claims (Loose Lips Lead to Lawsuits) By Claudia Gaglione, Esq.
  • Wells Fargo Settles Mortgage Discrimination Suit With $100M Fund To Help Low-Income Homebuyers
  • HB 355 and What Every Appraiser Should Learn from Kentucky’s Legislative Win, By Bryan S. Reynolds, MNAA
  • MBA: Mortgage applications decreased 8.5 percent from one week earlier

——————————————-

Adapt or Step Back? How UAD 3.6 Is Forcing a Career Decision for Appraisers

By Rachel Mann

Behind the technical transition lies a more personal question: Is it worth starting over at this stage of a career?

Excerpts: A Profession Split in Real Time

While there’s plenty of buzz around UAD 3.6 itself, it’s worth taking a boots-on-the-ground look at what active appraisers are actually feeling. In a recent industry poll conducted on Facebook, the findings were telling.

Out of 233 responses from active appraisers, 36.5% reported they are actively preparing, while 36.1% are taking a “wait and see” approach. The remaining responses, which we’ll get into below, reveal the deeper undercurrents.

The clear takeaway is that the industry isn’t aligned. There’s real uncertainty in how appraisers are responding to the shift, and a large unknown hanging over the profession.

And it raises a question: Is the uncertainty driven by the change itself, or by the lack of clear options for what happens next?

Appraiser Voices: Real Reactions to UAD 3.6

Beyond the “actively preparing” and “wait and see” camps, smaller groups of respondents revealed the deeper anxieties at play.

About 8.2% cited concerns about the learning curve, 4.7% said they’re considering stepping back from volume, and 2.6% plan to retreat into private work only.

Another 12% fell into smaller categories ranging from software testing readiness and hardware concerns to skepticism about implementation timelines.

The overall picture is a mix of readiness, hesitation, and resistance — revealing capacity limits and decision fatigue at a critical moment: adapt or step back? The underlying question for those nearing retirement is: Is it worth the time, cost, and effort to adapt at this stage in my career?

When a Workflow Change Becomes a Career….

A sudden decline in active appraisers could carry real consequences:

  • Loss of experienced appraisers who currently make up the majority of the workforce
  • 2. Disruption of long-standing client relationships, leaving lenders, AMCs, and homeowners scrambling
  • A thinning mentorship pipeline for new appraisers, weakening the path forward for the next generation
  • These changes, paired with the lack of exit planning, have broader implications. This isn’t an individual issue; it impacts industry stability and continuity.

To read more, Click Here

My comments: Worth reading the entire post for the details and interesting comments.

Read more!!

Appraisal Construction Progress Reports

Newz: Curiosity and AI, Construction Progress Reports

April 24, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Construction Progress Reports: Don’t Get Hammered
  • The Human Appraiser as a Macroeconomic Stabilizer By Kevin Hecht
  • Spectacular Glass Cabin Located Mere Steps From the Beach Lists for Less Than $175K
  • Appraisal Bias Training Now Required in Most States [2026]
  • MY AD: Review of Appraiser’s Guide to the New URAR Class
  • Curiosity in the Age of AI By Brent Owen
  • AI in real estate. Chat GPT can’t smell the 10 cats in the house By Ryan Lundquist
  • MBA: Mortgage applications increased 7.9 percent from one week earlier

———————————————————————–

Read more!!

Appraising Solar Panels

Newz: Solar Panels, Concessions, AI and Appraisals

April 3, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Navigating Red Flags: a Contentious Divorce Case
  • What Is the Appraisal Value of Solar Panels? FAQs for Residential Appraisers
  • Tiny New York Home With No Bedrooms Hits the Market for a Bargain Price
  • Concessions Are Not the Price: How to Measure What the Market Is Actually Doing
  • MY AD: How to reduce stress to be more productive in business and a happier life for appraisers
  • My First 50 Years by Steve Papin
  • AI Usage in Appraisals: Trust but Verify by Jo Traut
  • MBA STATS: Mortgage applications decreased 10.4 percent from one week earlier


————————————————————————-

——————————————

What Is the Appraisal Value of Solar Panels? FAQs for Residential Appraisers

Excerpts:

How Common Are Solar Panels in Residential Appraisals?

Solar panels are increasingly common. Declining system costs, government tax incentives, and utility rebates have made solar PV ownership more accessible than ever. If you haven’t encountered an owned solar system on a subject property yet, there’s a good chance you will soon—particularly as more states push toward renewable energy goals.

The practical takeaway: developing a working knowledge of solar valuation now puts you ahead of the curve.

Topics:

Owned vs Leased Solar Panels—and Why It Matters for Appraisers

How Do You Determine the Appraisal Value of Solar Panels?

  • Sales Comparison Approach. This is the preferred method under Fannie Mae and FHA guidelines.
  • Cost Approach Solar PV systems are typically priced on a cost-per-watt or cost-per-kilowatt basis.
  • Income Approach This method estimates value based on the energy savings the system produces.

What Do You Do When There Are No Comparable Sales with Solar Panels? This is the question appraisers ask most often, and it’s a real challenge in many markets.

——————————————————-

What Are the Key Components of a Solar PV System that Appraisers Should Be Able to Identify?

How Can Appraisers Build Competency in Solar Valuation?

Solar PV systems are one piece of a broader green home appraisal niche that’s growing fast.

To read more, Click Here

My comments: Very comprehensive analysis of the important factors. I have never appraised a home (or apartments and commercial properties) with Solar. I live in a “Mediterranean” climate in the San Francisco Bay area. No big changes in weather over the year. No snow, no high heat etc. But I have heard appraisers discussing the topics above. If I appraised Solar in a home I would use this article.

Read more!!

UAD 3.6 and Appraisal Workflow

Newz: Practical AI Uses for Appraisers, Appraisal Forms Humor 

March 13, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Client Insists on Cost to Cure
  • UAD 3.6 Is Coming: A Practical Moment to Rethink Your Workflow
  • Appraisal By Kevin Hetch
  • One of Palm Springs’ ‘Storied’ Rock Houses Hits the Market for $1.5 Million: ‘A Rare Treasure’
  • Getting 94 offers & a tighter housing market By Ryan Lundquist
  • MY AD: Do I really have to report that state board issue to my E&O insurance? By Peter Christsen, Esq.
  • Beyond the Hype: How I’m Using AI to Actually Save 10 Hours a Week By Dustin Harris
  • Appraisal Forms – the next Generation – Humor
  • MBA : Mortgage applications increased 3.2 percent from one week earlier

——————————————————————–


—————————————————————————

UAD 3.6 Is Coming: A Practical Moment to Rethink Your Workflow Appraisal

By Kevin Hecht

Excerpts: For many appraisers, the transition to UAD 3.6 feels different from past form updates. This is not simply a revised version of the URAR with a few new fields or definitions. It represents a structural shift in how appraisal data is organized, communicated, and delivered.

While change on this scale can feel disruptive, it also creates an opportunity to improve efficiency, modernize workflows, and position your business for the future.

This transition is not just about learning a new report format. It is about adapting to a new data-centric environment. And one of the most important places to start is with your appraisal software.

This Is a Moment of Opportunity

Transitions like this can feel uncertain, but they also offer a chance to improve how you work.

By taking time now to understand UAD 3.6, evaluate your software options, and refine your workflow, you can position your business to operate more efficiently and confidently in the new reporting environment.

The goal is not simply to adapt. It is to build a workflow that supports you well into the future.

UAD 3.6 is coming. And with the right preparation, it can be a step forward for both the profession and your practice.

Topics

  • This Is More Than a Form Update
  • Start by Looking at Your Process, Not Just Your Software
  • Not All Software Will Handle This Transition the Same Way
  • Efficiency Gains Are Possible, But They May Require Change
  • Focus on What Supports Your Business Long Term
  • The Appraiser’s Role Remains the Same
  • This Is a Moment of Opportunity

To read more, Click Here

My comments: I had never thought about the “big picture”: how the software affects your business. Worth reading.

I have been writing about the appraisal software for a year and just wrote another article on Appraisal software vendor Timelines for my April newsletter. Only 1 or 2 are ready to go. The others need more work done. Appraisers cannot learn to use the software until it is fully completed.

Why is this going so slow? The GSEs did not check with the software vendors to see how much time they needed to complete their software. The actual time needed has been longer than expected. Also, GSE requirements to make all the software the same for the reporting section had to be exactly the same for all the vendors. Also, PDF and XML reports must be correctly done. Getting this all validated by the GSEs is taking time.

Read more!!

Paired Sales for Appraisers

Newz: Paired Sales Analysis, AI and Appraisers?

February 27, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: When Confidentiality Agreements Conflict with USPAP
  • Paired Sales Analysis: Tips and Tools for Appraisers
  • Converted Church With Bell Tower and Pulpit Lists for $225K
  • Determining Assignment Conditions in a Vacuum By Jo Ann Aposto
  • MY AD: An Appraiser Gets Audited by the IRS! My Story Don’t Make My Mistakes! By Ann O’Rourke
  • Artificial Intelligence: Friend or Foe of Appraisers?
  • Fed moves to pull mortgages back into banking fold
  • MBA: Mortgage applications increased 0.4 percent from one week earlier

———————————————————————————

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


Paired Sales Analysis: Tips and Tools for Appraisers

By Kevin Hecht

Excerpts: Though not without challenges, paired sales analysis is a valuable technique to have in your appraisal toolkit. Mastering this method will help you develop more accurate, credible, and defensible appraisals.

This guide presents a step-by-step approach to performing paired sales analysis, practical tips and tools to improve your accuracy, plus strategies to overcome common challenges like sparse comparable data.

Paired Sales Analysis Example

For example, suppose two very similar homes in the same neighborhood sell within three months of each other. One house has a separate two-car garage, while the other does not. If the garage-equipped home sold for $15,000 more, you can reasonably infer that the garage adds $15,000 in value.

Uses

Primarily used in the sales comparison approach, paired sales analysis is particularly useful for estimating the value of unique property attributes such as:

  • Location advantages (corner lots, cul-de-sac positions, or waterfront access)
  • Scenic views or privacy features
  • Property upgrades (pools, finished basements, luxury kitchens)
  • Additional structures (workshops, guest houses, storage buildings)
  • Land size variations or irregular lot configurations

TOPICS

  • What is paired sales analysis
  • Step-by-Step Methodology of a Paired Sales Analysis…
  • Paired Sales Analysis Tips and Best Practices
  • Additional Tips Shared by Appraisers
  • Overcoming Challenges: What to Do When Data Is Sparse

To read more, Click Here

My comments: Comprehensive and definitely worth reading. I have regularly used paired sales, when I could find good comps. I often go back in time, as market conditions adjustments are easy to do. I got a few new ideas I had not thought of before in this article.

Read more!!

UAD 3.6 Appraisal Fees

New URAR and UAD 3.6 Appraisal Fees, AMC Tech Fees

February 6, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Using trainees – the safe way
  • Will the New URAR and UAD 3.6 Impact Appraisal Fees?
  • It looks like an SF apartment complex. It’s actually a $32M estate.
  • From Dealerships to AMCs: Tech Fees as the New Normal by Desiree Mehbod
  • MY AD: New in the February 2026 issue of Appraisal Today. Book Review: Mein Comp: The Last Appraiser
  • “Because Houses Are Human” AI and Appraisers By David Hyman
  • Architecture Is About to Grow a Nervous System
  • Buildings that are alive
  • MBA: Mortgage applications decreased 8.5 percent from one week earlier

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


———————————————————-

Will the New URAR and UAD 3.6 Impact Appraisal Fees?

Excerpts: With the new URAR and UAD 3.6 rolling out this year, you may be wondering what effect this will have on your fees. While there’s still a lot of uncertainty and speculation around this question, we’re sharing the opinions of professional real estate appraisers who answered our survey, “How do you anticipate the new URAR/UAD 3.6 changes will impact your appraisal fees?”

FEE INCREASES

Over 40% of respondents said they expect their appraisal fees to increase. Still, many respondents (28%) said they anticipate that fees will remain static, and 31% said they are not sure yet. Read their comments below to learn why or why not some appraisers believe their fees will increase with the new URAR and UAD 3.6.

APPRAISER RESPONSES

I Expect Fees to Increase” (41%)

“I have had ample time to practice the new 3.6 through my software and the inspection time will be increasing substantially…. Inspections are going to take some time especially if the dwelling is more than 1,000sf, which most in my market area are well above that. The report cannot be submitted until all sections are 100% complete, so there will be more time contacting agents, homeowners, town facilities, etc. Hoping the learning curve will be quicker than it appears at this point in time.”

I Expect Fees to Stay About the Same” (28%)

FEES REMAIN THE SAME

“I think it will be more labor intensive in the field but easier once you get back to the office.”

“I expect fees to stay the same. There may be less form filling; however, the analysis will remain the same. It’s not about the form or the analytics tools we use; it’s the analysis itself.”

The Bottom Line

While many appraisers anticipate that UAD 3.6 and the new URAR will initially require more time, tighter workflows, and new technology investments, the longer-term outlook is more balanced and, in many ways, promising.

Transitions of this scale often come with short-term growing pains, but clearer data standards, more structured reporting, and modernized tools are designed to create greater consistency and efficiency once the learning curve levels out. As several respondents pointed out, it will take real-world experience to understand where timelines and workloads ultimately settle.

At the same time, the new form offers appraisers a stronger platform to demonstrate the depth of their analysis, judgment, and market expertise.

To read more, Click Here

My comments: THIS IS THE HOTTEST TOPIC IN RESIDENTIAL LENDER APPRAISING. Appraiser opinions are useful but we all want to know what AMCs are planning for fees. I anticipate higher fees by AMCs, borrowers and direct lenders. I have been writing about what is happening since early this year, including details of all the “questions” and uncertainties on the SFR report.

Another significant fee factor is that many appraisers are retiring or quitting because they don’t want to learn the UAD 3.6 for appraisers. Those who stay will have lots of appraisal work as the 11-2-26 mandatory deadline approaches.

UAD 3.6 is not mandatory until November 2, 2026. The Legacy forms will be used during the transition. Will it be done by 11-2-26? Now, software vendors and lenders are way behind. 11-2-27 new mandate date???

On the plus side, 41% of appraisers said fees would go up and are positive about the new reports.

Read more!!

AI and Appraisers

Newz: UAD 3.6 Started for Lenders, AI and Appraisers

January 30, 2026

—————————————————————————–

What AI Means For Appraisers

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

——————————————————————–


What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Safety issues not fixed
  • 7.5 Things AI Is Already Doing Better Than Most Appraisers (And Why That’s Okay) By Mark Buhler
  • EXCLUSIVE: Tech Mogul Lists His Custom-Built Coral Gables Megamansion for Sky-High Price of $22 Million
  • Critical Thinking and the Intellectual Deficit in Real Estate Appraisal Qualifying Education by Timothy Andersen
  • MY AD: Appraisers’ Guide to the New URAR by Dave Towne
  • GSEs: Available Now in Broad Production: UAD 3.6 and Forms Redesign
  • URAR: Expect The Unexpected. How UAD 3.6 affects lenders
  • MBA: Mortgage applications decreased 8.5 percent from one week earlier

————————————–

7.5 Things AI Is Already Doing Better Than Most Appraisers (And Why That’s Okay)

By Mark Buhler

A while ago I wrote about “7.5 Things Appraisers Can Do That Artificial Intelligence Cannot”—the human parts of the job AVMs and algorithms still can’t touch: judging condition and quality, interpreting oddball features, smelling the house, defending adjustments, testifying in court, and exercising professional judgment under pressure.

None of that has changed.

What has changed is the toolset. AI is already doing parts of the workflow faster, cheaper, and more consistently than most humans—not the appraisal itself, but much of the heavy lifting underneath it:

Data gathering and sorting

Pattern detection

First-draft writing

Basic consistency and error checks

You will not beat AI at those tasks. The good news is you do not need to.

7.5 Tools you need:

1. Sifting Massive Datasets for Patterns

2. 2. Generating a First-Pass Comp Set

3. Producing Market Metrics and Adjustment Support on Demand

In my first article, I argued that AI cannot judge condition, interpret quirks, smell the house, testify in court, or exercise professional judgment. That remains true.

What has changed is the gap between appraisers who leverage AI and those who pretend it does not exist. The market is looking for valuation professionals who can…

To read more, Click Here

My comments: Definitely worth reading, including all 7 of the Tools.

——————————————————


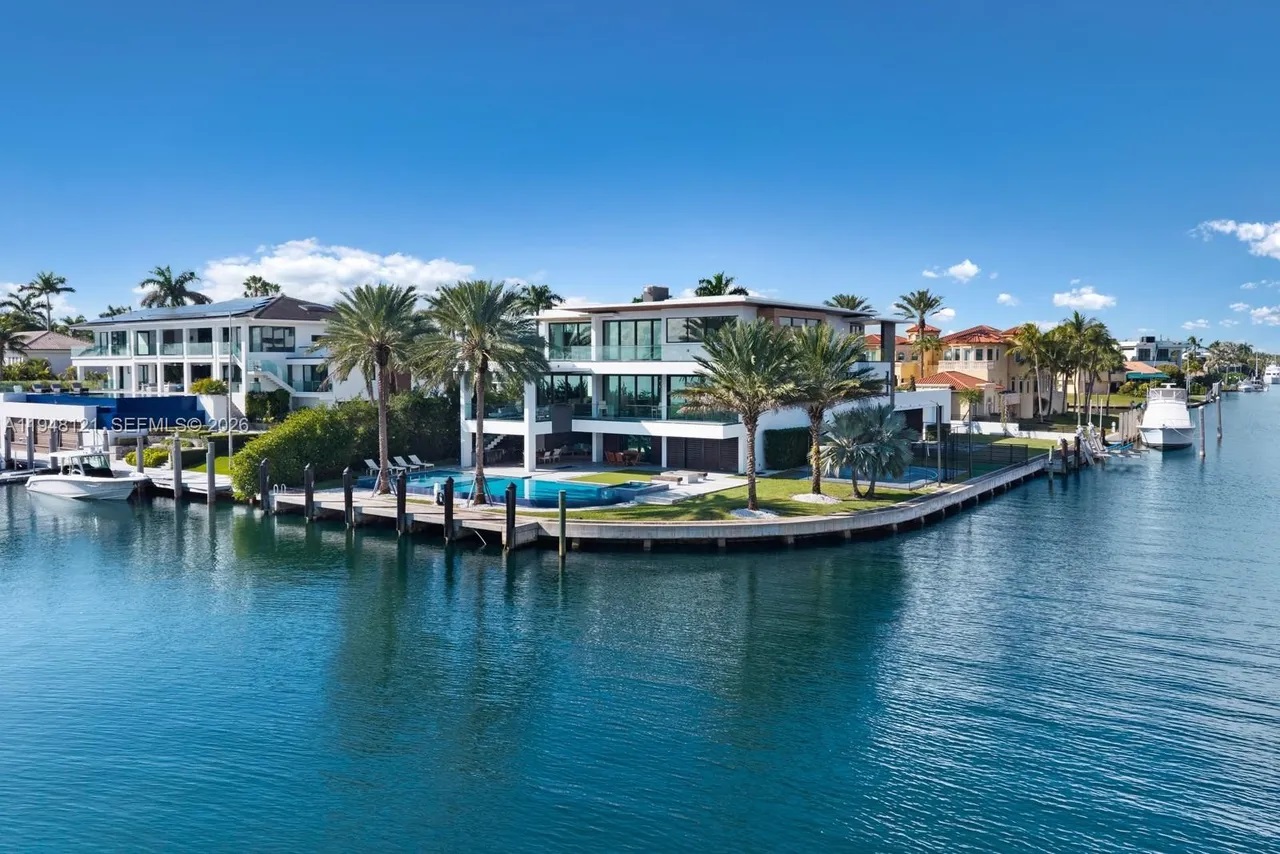
EXCLUSIVE: Tech Mogul Lists His Custom-Built Coral Gables Megamansion for Sky-High Price of $22 Million

Excerpts: 7 bedrooms, 7.5 baths, 7007 sq.ft., 0.47 acre lot, built in 2018

It was the unobstructed views out over the water that first drew the tech expert to the property, as well as the privacy offered by its location in a secure gated community, and the fact that the Bahamian island chain of Bimini is just a 1.5-hour boat ride from the home’s dock.

From the outside, the home could be mistaken for a resort thanks to its lavish pool, built-in barbecue, firepit lounge, outdoor kitchen, expansive waterfront terraces, and a basketball or volleyball court by the water—all of which make for a rare backdrop of relaxation and play.

Elsewhere on the grounds, there are two private docks that accommodate a superyacht of more than 100 feet, a 30,000-pound boat lift, and access to Biscayne Bay.

To read more, Click Here

To see the listing with an aerial view, virtual tour and 60 photos, Click Here

————————————————————-

Critical Thinking and the Intellectual Deficit in Real Estate Appraisal Qualifying Education

by Timothy Andersen, MAI The Appraiser’s Advocate

Excerpts: It is the premise of this essay that critical thinking, analytical rigor, integrative synthesis, and dialectical method are indispensable to the cultivation of competent real estate appraisers and the concomitant production of credible appraisals and non-misleading appraisal reports.

Yet, curiously, these conceptual pillars are either wholly absent or conspicuously marginalized within the current corpus of real estate appraisal qualifying education (QE). That QE in its present form is devoid of any formal engagement with these concepts suggests a foundational deficiency that imperils the credibility of both practice and pedagogy.

Appraisal is, at its core, a dialectical enterprise. The seller posits a value—often broker-influenced and aspirational. The buyer counters with skepticism and a desire for a discount. The broker inserts pecuniary incentives into the mix, motivated by the commission structure. The appraiser is thrust into this cauldron of competing value claims, charged with the burden of arbitrating truth. The appraiser must navigate opposing viewpoints, adjudicate conflicting data, and deliver a resolution rooted in evidence and reason.

In this sense, each appraisal is a dialectical negotiation, an intellectual endeavor wherein the appraiser becomes not merely a market technician but a philosophical mediator. Such work demands a skill set that far exceeds the filling of forms or the clicking of dropdown menus. It requires a mind trained in critical discernment, analytical rigor, synthetic coherence, and dialectical resolution, not merely in filling out a reporting form.

Yet, current appraisal QE and CE, and some of their providers, entrenched in their pedagogical inertia, fail to cultivate these competencies. They privilege mechanics over meaning, technique over thought. The consequence of such tactics is clear: we produce technicians, not scholars; form-fillers, not thinkers.

To read more,