For Appraisers: FHA Adopting UAD 3.6

Newz: FHA Adopting UAD 3.6, AO-41: Tech Guidance, Analysis of 2026 Appraisal Licenses, Certification 25 (in UAD 3.6)

October 9, 2026

ARTICLE LIST – Scroll down to see the articles, in order

  • LIA AD: “Off the cuff” opinions
  • FHA Announces Optional Broad Production Period for Uniform Appraisal Dataset (UAD) 3.6
  • Summary of Proposed Changes to HUD Handbook 4000.1 – September 2026
  • 8.5-Acre Waterfront Palm Beach Megamansion Owned by Billionaire Tech Mogul Is Listed for a Staggering $165 Million
  • (Advisory Opinion) AO-41: TAF’s New Tech Guidance and What It Means, By Isaac Peck, Publisher WorkingRE
  • MYAD: UAD 3.6 – A Phase-In Approach: Get the Report Done first By Doug Smith, SRA
  • Certification 25 and the Quiet Breach of Appraiser Confidentiality, By Desiree Mehbod, Part 1 and 2
  • Analysis of 2026 ASC Appraisal License Data By Chase Pursley
  • MY UAD 3.6 UPDATE – Exemption clarifications, Cert 25, VA
  • MBA STATS: Mortgage applications decreased 6.0 percent from one week earlier
FHA Announces Optional Broad Production Period for Uniform Appraisal Dataset (UAD) 3.6

FHA is pleased to announce a major step toward implementation of Uniform Appraisal Dataset (UAD) 3.6. Following the successful completion of beta testing, FHA’s Electronic Appraisal Delivery (EAD) portal is now available for an optional broad production period for mortgagees to submit appraisals using UAD 3.6.

This optional phase gives mortgagees flexibility to transition to UAD 3.6 for FHA cases prior to the government sponsored enterprises’ (GSEs’) mandatory transition scheduled for November 2, 2026.

What you need to know and do now:

Effective immediately, all FHA-approved mortgagees participating in Title II forward mortgage and Home Equity Conversion Mortgage (HECM) programs may begin submitting appraisals in the UAD 3.6 format.

Mortgagees may continue to deliver all or some of their appraisals to the EAD portal in the legacy UAD 2.6 format.

For a given case number, the same UAD format of the initial submission must be used in all subsequent appraisal submissions for that case ― submission of multiple formats is not permitted.

FHA will continue to gather information to assess mortgagee transition readiness before establishing and announcing an FHA mandatory adoption date.

Mortgagees and appraisers should review the UAD 3.6 Implementation Preparedness Toolbox resource, available on the EAD portal webpage, for key technical specifications and transition guidance.

To read the UAD 3.6 Implementation Preparedness Toolbox, Click Here

To read the announcement (pdf) , FHA INFO 2026-23, with more links,

My comment: Good to see what FHA is doing. For VA info, see MY UAD 3.6 UPDATE below
Read more!! →

New Fannie Highest and Best Use Playbook

Newz: New Fannie Highest and Best Use Playbook, UAD 3.6 Nov. 2 and Other Deadlines??

September, 25, 2026

ARTICLE LIST:

In Order, Scroll down the page to read

  • LIA AD: Conflicting Assignments and Professional Ethics
  • New Fannie Highest and Best Use Playbook and Q&As
  • For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat
  • UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!! By Doug Smith, SRA
  • MY AD: Make use of your driving time by exercising
  • Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI By Dustin Harris
  • MBA stats: Mortgage applications decreased 1.5 percent from one week earlier


Thanks to our Sponsor!!!

Very reasonable prices and good open rates for our ads!

————————————————————

New Fannie Highest and Best Use Playbook and Q&As

By Dave Towne

For those of you doing (or will do) the New URAR/UAD 3.6 mortgage lending reports from now into the future, you need to read and understand this new policy change from FannieMae. Because this new UAD report process also applies to FreddieMac, my presumption is they will issue a policy statement of their own with similar wording.

For the time being, here is the FNMA new policy, issued on Sept. 2, 2026: Highest and best use requirements for Uniform Appraisal Dataset (UAD) 3.6

This policy updates the highest and best use requirements for appraisal reports completed using Uniform Appraisal Dataset (UAD) 3.6.

These changes apply only to UAD 3.6 appraisal assignments to support the new Uniform Residential Appraisal Report (URAR) reporting requirements and do not apply to appraisal reports completed using legacy appraisal report forms.

We updated our policy to:

• require the property’s highest and best use, as improved or as proposed, to be a residential use, rather than requiring it to be the property’s present use;

• define present use, residential use, and subordinate use in the context of highest and best use;

• require the property to be a primarily residential one- to four-unit property, with any non-residential use subordinate to the residential use, replacing the previous “residential in nature” guidance; and

• establish the eligibility criteria and reporting requirements for one- to four-unit residential properties when the present use does not satisfy one or more of the highest and best use tests.

The UAD 3.6 Policy Supplement has been updated to reflect these changes.

Effective: This policy change is effective immediately for appraisal reports completed using UAD 3.6.

Remember, to be USPAP compliant, you can’t “just check the box” on the New URAR/UAD 3.6 data base input field (or on the Legacy forms either) to indicate ‘present use,’ and then move on. You must add a written statement in that site section comment input field explaining why you decided that is the accurate use of the property. Craft your statement to comply with the above policy.

Also remember this: if you decide the property’s H&BU is not Residential use, you must check the box “No.” In most cases, when you do that, the need to complete a full appraisal report ends at that point because the lender cannot proceed with a residential mortgage loan. Your statement needs to define what the actual use is if not Residential. Stop working on the report and contact your client to fully explain the current situation. Let them determine how to proceed.

—————————————————————–

What is in Fannie’s New The Highest & Best Use 25 page Playbook (Per Fannie)

• This playbook provides key concepts and illustrative scenarios to help industry participants better understand how the results of the highest and best use (HBU) may affect loan eligibility.

• Each scenario presents a complex highest and best use question based on the specific circumstances of a subject property. While every property has its own unique characteristics and circumstances, which may lead to different conclusions, these scenarios are designed to demonstrate how you can apply Fannie Mae policy consistently across a range of situations. They are intended to provide practical guidance and support informed, policy-compliant decision-making.

• A resolution is provided for each scenario, along with the appraiser and lender responsibilities with relevant Fannie Mae Selling Guide Supplement: Uniform Appraisal Data (UAD) 3.6 Policy resources.

• The Highest and Best Use Frequently Asked Questions document addresses common questions related to present use, highest and best use, mixed-use properties, analysis of subordinate uses, comparable sales, the URAR, and loan eligibility. The document is available separately and linked throughout the Playbook for easy reference.

To read the Highest and Best Use Playbook, Click Here

To read the separate FAQ document, with 27 Q&As, Click Here

My comments: Many thanks (again) to Dave Towne for writing a summary of the 25 page document at the top of this article. To subscribe to his regular emails, send an email to dtowne@fidalgo.net . Say that you want to subscribe to his list. I have been subscribing for many years.


Read more!! →

Fannie Appraiser Update

Newz: Fannie Appraiser Update, Kentucky Board Approves Increase in Licensing Fees

July 24, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Client Insists on Cost to Cure
  • Fannie Mae Appraiser Update, July 16, 2026
  • Glittering L.A Megamansion With ‘Dramatic’ 50-Foot Water Wall and Swim-Up Hits the Market for $88 Million
  • Kentucky Board Approves Significant Increase in Appraiser Licensing Fees
  • MY AD: Doug Smith’s tips on selecting UAD 3.6 software
  • Honoring Jan Bellas, Our Greatest Advocate
  • Where Does an FHA Appraisal End and a Home Inspection Begin? HUD Has an Opportunity to Clarify. By Shane White, SRA (REPRINT)
  • Upcoming National Appraisal Conferences in Las Vegas
  • MBA STATS: Mortgage applications increased 1.9 percent from one week earlier

————————————————————————–

Fannie Mae Appraiser Update

July 16, 2026

Get practical guidance to help you prepare for the Uniform Appraisal Dataset (UAD) 3.6 and Forms Redesign transition and stay current on updates that affect your work.

In this second Appraiser Update of 2026—and our 35th edition since launching in 2017—we’re sharing timely insights, policy updates, and resources to help you navigate industry changes and support your success.

In this issue, you’ll find:

Expert insights on key UAD 3.6 topics, including terminology updates, policy changes, unit counts, and more.

What Appraisal Management Company access to Collateral Underwriter® (CU®) means and how to navigate it effectively.

List of Topics

  • Changes to UAD language in 3.6
  •  Unit Count Differences in the Sales Comparison Grid
  •  UAD 3.6 Reports: Lessons Learned
  •  AMC Access to Collateral Underwriter

Sample Topic detail

Vet Comments for Accuracy and Necessity

Some of the most common problems we have seen in UAD 3.6 appraisal reports relate to inaccurate or unnecessary comments. Here are some actual cases that illustrate the issue:

Contradictory information: In the SCA grid, an appraiser correctly utilized the Comparable Weight field to state that Comp 1 was given most weight and Comps 2-3 were given less weight, but then the appraiser added a comment that “The final opinion of value has been weighted equally among comparable sales 1-3.” The contradiction between the information in the enumerated data versus the narrative comment is confusing to the reader and undermines the appraiser’s credibility. A more helpful and appropriate comment would explain why comp 1 merited the most weight.*

Repetitive information: Another common issue we have seen in UAD 3.6 reports is the appraiser repeating the condition rating (already stated in a defined data element) in the associated comment field.*

Outdated language: In another report, an appraiser commented in the Sketch Commentary field that “The GLA for the subject was derived by…” Of course, the term “GLA” or Gross Living Area has been replaced in UAD 3.6 with the term “above grade finished area” (see accompanying article in this newsletter), so the reference to GLA was a non sequitur and confusing to the reader.

*These cases illustrate the general principle that appraisers should not restate information already contained in the defined data elements.

To read more, Click Here

My comments: Definitely worth reading for excellent “how to” advice on UAD 3.6.

Read more!! →

Fannie Appraiser Update Q1 2026

Newz: Fannie Appraiser Update Q1, Suspended AMC, Bias

March 27, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Should I consider this an actual claim?
  • Fannie Appraiser Update Q1
  • 126-Year-Old Gentlemen’s Estate That Epitomizes Gilded Age Opulence Lists in the Berkshires for $8 Million
  • Suspended: The AMC That Turned “Review” Into a Value Demand
  • Retirement: To Stay, To Go, or Can’t Decide? That is the Question!
  • AQB Releases Job Analysis Report
  • A Baseless Bias Claim Turns Into a State Appraisal Crusade
  • MBA: Mortgage applications decreased 10.5 percent from one week earlier

———————————————————-

————————————————————————–

Fannie Appraiser Update Q1

Email Message 3/19/26

Welcome to the first Appraiser Update of 2026. This edition delivers timely information to help you stay competitive and ready for what’s next, including:

Preparing for the fast-approaching Uniform Appraisal Dataset (UAD) 3.6 and Forms Redesign mandate on Nov. 2, 2026;

Understanding Appraisal Quality Monitoring letters to appraisers related to time adjustments; and

Embracing expanded eligibility for manufactured housing and accessory dwelling units – available only for UAD 3.6 submissions.

Topics list

  • UAD 3.6 articles
  • Appraisal Software Selection
  • Treatment of Location and View
  • Market Conditions Analysis Letters
  • MH Policy Changes
  • ADU Policy Changes

To read the update, Click Here

My comment: Worth reading, of course. Always a very popular link!

Read more!! →

Q4 2025 Fannie Mae Appraiser Update – AMC Risk, UAD 3.6

Newz: 12 Days of Appraiser Christmas,
Q4 2025 Fannie Mae Appraiser Update –AMC Risk, UAD 3.6

December 19, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: A Family Feud and Intended Use
  • Q4 2025 Fannie Mae Appraiser Update – AMC risk, UAD 3.6
  • 12 Days of Appraiser Christmas
  • Santa’s House is Back on Zillow with a Bold New Holiday Look
  • Highest and Best—and the Highest Value By Richard Hagar
  • AQB Proposed Changes in New Appraiser Requirements
  • MBA: Mortgage applications decreased 3.8 percent from one week earlier
  • ————————————————————

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


——————————————————

Q4 2025 Fannie Mae Appraiser Update

As the year wraps up, we’re focused on what matters most to your success: clarity, consistency, and confidence in every appraisal. This edition gives you practical insights to stay ahead:

  • Several deep-dive articles on Uniform Appraisal Dataset (UAD) 3.6, focused on condition/quality ratings, the inspection component of Scope of Work, disaster mitigation, energy efficiency, and training and resources;
  • Why time adjustments matter—and how to apply them effectively; and
  • Our approach to managing Appraiser Management Company (AMC) risk for stronger compliance and reliability. Excerpts: In Jul. 2025, Fannie Mae began sending letters to AMCs detailing appraisal quality issues identified through Fannie Mae loan quality reviews completed in 2024. Each letter contains a comprehensive list of the issues identified for appraisals associated with that AMC.

To read more, Click Here

My comments: Worth reading. First time I have ever seen comments on AMCs. Good to see that GSEs are looking at AMCs.

————————————————————–

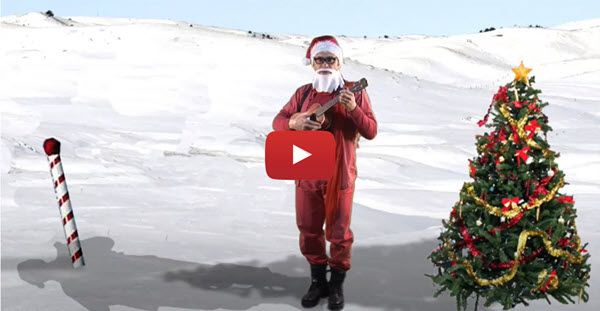
12 Days of Appraiser Christmas

NOTE on video: Click on image and it opens in Youtube.

Very funny!! 3.5 minute video

Sample appraisal requests:

On the fourth day of Christmas my best client sent to me falling

Shacks, three field reviews, two double wides, and a drive by single family.

On the tenth day of Christmas, my best client sent to me 10 tax appeals and eight Mega Mansions.

Singer in this video is comedian David Cassel as the Ukulele Bandito http://www.theukulelebandito.com / (he is not a Portland appraiser, but he is funny)

Many thanks to Gary F. Kristensen, SRA, ASA, AGA at A Quality Appraisals in Portland, Oregon.

My comment: I love this FUN video ;>

Read more!! →

Fannie Mae’s Selling Guide Updates

Newz: Fannie Mae’s Selling Guide Updates, Appraisers and Certainty in Mortgage Lending

November 14, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA: Conflicting Assignments and Professional Ethics
  • Beyond Terminology: What Fannie Mae’s Selling Guide Updates Mean for Appraisers
  • Genius’ Midcentury Modern Home Designed by Jimi Hendrix’s Studio Architect Lists in Woodstock for $3.5 Million
  • App-solutely Clueless: When Sales Tries to School Appraisers
  • Trump Defends 50-Year Mortgage Plan as ‘Not a Big Deal’ After Furious Backlash
  • The Strategic Advantage of Certainty in Mortgage Lending What it means for appraisals
  • MBA: Mortgage applications increased 0.6 percent from one week earlier

—————————————————————

Changes to Fannie Selling Guide dated April 15, 2014

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

————————————————————

—————————————————————

Beyond Terminology: What Fannie Mae’s Selling Guide Updates Mean for Appraisers

by Scott DiBiasio, Director of Government Affairs, Appraisal Institute

Excerpts: Fannie Mae recently issued important updates to its Selling Guide that may look like technical revisions but have significant implications for appraisers, consumers, and the valuation profession. The most visible changes involve the retirement of the term “appraisal waiver” in favor of “value acceptance” and adjustments to the Reconsideration of Value (ROV) process. Together, these changes reflect the GSEs’ modernization priorities—but also highlight the ongoing tension between efficiency and transparency.

From “Appraisal Waiver” to “Value Acceptance”

Fannie Mae has decided to eliminate the term “appraisal waiver” from the Selling Guide, replacing it entirely with “value acceptance.” Even the parenthetical “(appraisal waiver)” has been removed. The stated goal is to unify industry language and create consistency across the valuation spectrum.

That may sound harmless, but let’s be clear: the average consumer is not going to recognize that “value acceptance” means their lender has waived an appraisal altogether. That lack of clarity undermines transparency at a critical stage of the lending process.

The Appraisal Institute (AI) will absolutely continue to call these products what they are: appraisal waivers. Language matters. Consumers and appraisers alike deserve accuracy, not euphemisms, when it comes to understanding whether an independent appraisal has been performed.

Why This Matters for Appraisers

Taken together, the Selling Guide updates and the expansion of waiver-based models point to several key takeaways:

1. Language shapes perception. If consumers don’t recognize that value acceptance is an appraisal waiver, transparency suffers. That’s why AI will continue to call these products by their true name.

2. Efficiency is not clarity. Simplifying disclosures may ease compliance for lenders, but it risks reducing borrower awareness of their rights.

3. Modernization is accelerating. With waivers, UPDs, and hybrid appraisals expanding, appraisers must adapt their skills to remain at the center of the valuation process.

4. Incursion is real. Regulators, property data collectors, and third-party vendors are positioning themselves between appraisers and their clients. The profession cannot afford to cede ground.

To read more, Click Here

My comments: I had never read about what is discussed in this article. I don’t always read the Fannie Selling Guide Updates. Now I know why it is important.

When I wrote my article on Appraisal Regulatory Chaos in the monthly Appraisal Today newsletter, Scott let me include excerpts from what he has written about it plus sent me new information. This article has a few “promotional” comments about AI and classes, but well worth reading.

Read more!! →

Q3 2025 Fannie Mae Appraiser Update

Q3 2025 Fannie Mae Appraiser Update, When Sales are not Comps

September 26, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: When a Property Owner Wants to Do the Appraiser’s Job
  • Q3 2025 Fannie Mae Appraiser Update
  • 14 Mile Island House: $10.8 Million Historical Estate on a Private Island in New York Is Listed for Sale for the First Time in 60 Years
  • It’s the Right Time By Jeff Bradford, Founder and CEO of Bradford Technologies
  • Sales Don’t Always Become Comps By Ryan Lundquist
  • Is Commercial Property Appraisal Right for You?
  • Mortgage applications increased 0.6 percent from one week earlier
    —————————————————————————
  • Humor for Appraisers

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

——————————————————————-

————————————————————————–

Q3 2025 Fannie Mae Appraiser Update

Excerpts: In this edition, we share information and resources to help you navigate recently announced changes.

Perhaps the most significant appraisal policy change in recent memory is the launch of the new Uniform Appraisal Dataset (UAD) 3.6. In this edition we continue to unpack UAD 3.6 changes with the Update Report and the Completion Report.

To help with UAD 3.6 implementation, we have created a tool for appraisers to check their reports for UAD 3.6 compliance.

We also review recent Selling Guide changes related to reconsideration of value (ROV). Speaking of the Selling Guide, we provide some tips on how to make the most of this important resource for appraisers and we highlight changes to our ANSI fact sheet.

Topic LIst

  • Restricted Appraisal Update and Completion Reports
  • Comp driveby not required for UAD 3.6
  • UAD 3.6 compliance checker
  • Reconsideration of Value update
  • Stay up to date on Selling Guide changes

My comments: No more driving comps is a big change and is somewhat controversial for appraisers. Will lenders who don’t require UAD 3.6 drop the comp inspection requirement?

To read more, Click Here

Read more!! →

Changes to FHA Appraisal Requirements

Newz: FHA Appraisal Changes, Fannie Measurement Standards Update

July 4, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Unreasonable Subpoena Request
  • HUD Announces Changes to FHA Appraisal Requirements
  • The Rock House In Larkspur CO Is Back On The Market for $1,000,000
  • Baghdad Bob of Freddie Mac Merits Mention As Mideast Erupts
  • The Full Measure – June 25, 2025 By Kevin Hecht, Appraiser and Economist
  • Fannie: Standardizing Property Measuring Guidelines
  • MBA: Mortgage applications increased 2.7 percent from one week earlier

———————————————————————————

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

———————————————————-

——————————————–

HUD Announces Changes to FHA Appraisal Requirements

Excerpts: There are four significant appraisal-related revisions to Section II. D. of the Handbook.

  1. Subject and comparable photograph requirements have been revised….
  2. The appraiser is no longer required to state the remaining economic life of the dwelling in the appraisal report.
  3. In situations in which the subject is located in an increasing or decreasing market, the appraiser is no longer required to include an absorption analysis, a minimum of two sales that closed within 90 days of the effective date, and two active listings or pending sales.
  4. For Section 223(e) mortgages, the appraiser is no longer required to include an estimate of remaining physical life for the subject property improvements.

It is important to note that the originating lender is the client, not HUD/FHA, and as such, the lender may still require some or all the above items.

To read more, Click Here

To read the full document, Mortgagee Letter 2025-18, Click Here

My comments: Read the full article above and the original Morgagee Letter (Link above) for more details if you do FHA appraisals.

————————————————————————–

The Rock House In Larkspur CO Is Back On The Market for $1,000,000

Excerpts: 2 bedrooms, 2 baths, 2,432 sq.ft., 0.86 acre lot. Built in 2000.

The Larkspur Rock House is an iconic Flinstones style home, and now it can be yours for only $1,000,000. The rocks are maybe 200 million years old!!!Outdoor living spaces.

The Rock House is anything but ordinary—this striking, stucco-clad home is seamlessly built into a soaring red rock monolith, transforming nature’s artistry into a one-of-a-kind architectural statement.

The dramatic rock wall isn’t a backdrop—it’s the centerpiece, rising through all three levels and anchoring each floor in natural grandeur. Every space is visually and physically connected to the monolith at its core.

To read more, Click Here

To read the listing, Click Here

https://www.zillow.com/homedetails/6619-Apache-Pl-Larkspur-CO-80118/13497121_zpid/

Read more!! →

What’s a comparable property for appraisals?

Newz: Q2 Fannie Appraiser Update, Appraiser Wins Discrimination Lawsuit

June, 13, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA ad: Am I Still on the ‘Do Not Use’ List?
  • What’s a comparable property? Or a “comp,” as we say more informally? By Bryan Reynolds
  • Rotterdam’s Yellow Cube Homes
  • Q2 2025 Fannie Mae Appraiser Update – UAD 3.6
  • A Back to the Future Housing Market By Ryan Lundquist
  • Case Dismissed: Ohio Appraiser Wins Discrimination Lawsuit by Isaac Peck
  • Mortgage applications increased 12.5 percent from one week earlier

——————————————————————


—————————————————

Real Estate Agents and Comparable Sales – Tips for Appraisers

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

—————————————————————–

What’s a comparable property? Or a “comp,” as we say more informally?

By Bryan Reynolds

Excerpts: Let me give you an example of an appraisal report I saw recently, which is why I’m asking this question: There are 65 comparable properties currently offered for sale in the subject’s neighborhood, ranging from a price of $330,000 to $5,400,000. The report also states that there are 44 comparable sales in the subject’s neighborhood within the past 12 months, ranging from $152,000 to $2.2 million. That’s a big range. Are you comfortable putting that in your report?

What does the term “comparables” even mean? Let’s go to the authoritative sources. Here’s one: The Dictionary of Real Estate Appraisal, published by the Appraisal Institute. It defines comparables as “a shortened term for similar property sales, rentals, or operating expenses used in the comparison in the valuation process and best usage. The thing being compared should be specified.” In other words, are you looking at comparable sales, comparable rentals, or comparable listings?

Lastly, I’m going to pull up the Encyclopedia of Real Estate Appraising. It’s a great big book, and it has a whole section on this. I highlighted one part of it because I like it: “What is a comparable property? It is one that would be a reasonable alternative for most prospective buyers who would be interested in the subject property.”

What is a comparable property? It is one that would be a reasonable alternative for most prospective buyers who would be interested in the subject property.” —Encyclopedia of Real Estate Appraising

That’s very simple, and it invokes some good, common sense

To read more, Click Here

My comments: Lots of opinions on this topic!

—————————————————————————————-


29008552 – innovative yellow cubic houses built in rotterdam

Rotterdam’s Yellow Cube Homes

Excerpts: Both a popular tourist attraction and a strange architectural experiment, the cluster of 39 homes stands out amongst the city’s mostly modern architecture. However, that is what makes these “cube-perched-on-a-point” homes all the more interesting.

he elevated cubes are essentially houses supported on hexagonal piers; this design frees up the ground space for public use. Each cube measures 72 feet in height with each side measuring 25.5 feet. While the pillars and floor are made from reinforced concrete, structural wooden skeletons from the base for constructing the cubes were mounted on the floors’ edges. Interestingly, cement panels with rockwool insulation in the middle resulted in cutting down on almost all exterior sounds.

Inside, the complicated form meant that the interior walls were angled at 54.7 degrees with the floor. The consequences of this construction detail is that 25% of the almost 1,100-square-feet of living space is unusable because of the angular walls. The interior is divided into three floors that are connected by a narrow wooden staircase. The ground level houses in the living room and an open kitchen with plenty of windows. The second floor has two bedrooms, a bathroom, and a small living area. Finally, the third floor is a three-sided pyramid that can be used as a bedroom or an office.

To read more and see interior photos and floor plans, Click Here

My comments: Fascinating, with very good photos.

Read more!! →

Comparable Sales for Appraisals

Newz: Curiosity and Appraisers, GSEs future, Sideline AMCs

May 23, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Your Role as a Judge’s Appraiser
  • On Comparable Sales By Timothy Andersen, MAI
  • Futurist Architect’s Funky Spaceship-Inspired ‘Starcastle’ Hits the Market in Connecticut for $1.5 Million
  • Why Curiosity Matters in Appraisals
  • Mortgage Bankers Association head addresses ‘elephant in the room’
  • Bye Bye AMC: A Script to Sideline Appraisal Middlemen
  • Mortgage applications decreased 5.1 percent from one week earlier

Real Estate Agents and Comparable Sales – Tips for Appraisers

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

—————————————————————-


On Comparable Sales

By Timothy Andersen, MAI

Excerpts: This short article raises issues related to what constitutes or defines a comparable sale. While it may seem arrogant to take on a topic of this import, it is necessary, since there is not currently a formal definition. There are descriptions of what a comparable sale is. But there is no formal, universally recognized definition¹. However, does there need to be? Do we have enough technical information to understand the concept of a comparable sale? This article suggests the descriptions are sufficient.

It is common for the GSEs to criticize appraisers’ poor choice of comps. Under some conditions, the GSEs’ have the justification to level these critiques. Yet, given the wealth of descriptions there are in the available literature about what constitutes a comparable sale, why do appraisers ignore those descriptions to their own peril?

To read more, Click Here

My comments: Good analysis by Tim, The USPAP Expert. GSEs vs. USPAP goes on and on. I hate it when GSEs tell me how to do my appraisals. I am so glad I quit working for them in 2005. Non-lender appraisals rarely have special requirements and reviews.

Read more!! →