New Fannie Highest and Best Use Playbook

Newz: New Fannie Highest and Best Use Playbook, UAD 3.6 Nov. 2 and Other Deadlines??

September, 25, 2026

ARTICLE LIST:

In Order, Scroll down the page to read

  • LIA AD: Conflicting Assignments and Professional Ethics
  • New Fannie Highest and Best Use Playbook and Q&As
  • For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat
  • UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!! By Doug Smith, SRA
  • MY AD: Make use of your driving time by exercising
  • Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI By Dustin Harris
  • MBA stats: Mortgage applications decreased 1.5 percent from one week earlier
 

Thanks to our Sponsor!!!

Very reasonable prices and good open rates for our ads!

————————————————————

New Fannie Highest and Best Use Playbook and Q&As

By Dave Towne

For those of you doing (or will do) the New URAR/UAD 3.6 mortgage lending reports from now into the future, you need to read and understand this new policy change from FannieMae. Because this new UAD report process also applies to FreddieMac, my presumption is they will issue a policy statement of their own with similar wording.

For the time being, here is the FNMA new policy, issued on Sept. 2, 2026: Highest and best use requirements for Uniform Appraisal Dataset (UAD) 3.6

This policy updates the highest and best use requirements for appraisal reports completed using Uniform Appraisal Dataset (UAD) 3.6.

These changes apply only to UAD 3.6 appraisal assignments to support the new Uniform Residential Appraisal Report (URAR) reporting requirements and do not apply to appraisal reports completed using legacy appraisal report forms.

We updated our policy to:

• require the property’s highest and best use, as improved or as proposed, to be a residential use, rather than requiring it to be the property’s present use;

• define present use, residential use, and subordinate use in the context of highest and best use;

• require the property to be a primarily residential one- to four-unit property, with any non-residential use subordinate to the residential use, replacing the previous “residential in nature” guidance; and

• establish the eligibility criteria and reporting requirements for one- to four-unit residential properties when the present use does not satisfy one or more of the highest and best use tests.

The UAD 3.6 Policy Supplement has been updated to reflect these changes.

Effective: This policy change is effective immediately for appraisal reports completed using UAD 3.6.

Remember, to be USPAP compliant, you can’t “just check the box” on the New URAR/UAD 3.6 data base input field (or on the Legacy forms either) to indicate ‘present use,’ and then move on. You must add a written statement in that site section comment input field explaining why you decided that is the accurate use of the property. Craft your statement to comply with the above policy.

Also remember this: if you decide the property’s H&BU is not Residential use, you must check the box “No.” In most cases, when you do that, the need to complete a full appraisal report ends at that point because the lender cannot proceed with a residential mortgage loan. Your statement needs to define what the actual use is if not Residential. Stop working on the report and contact your client to fully explain the current situation. Let them determine how to proceed.

—————————————————————–

What is in Fannie’s New The Highest & Best Use 25 page Playbook (Per Fannie)

• This playbook provides key concepts and illustrative scenarios to help industry participants better understand how the results of the highest and best use (HBU) may affect loan eligibility.

• Each scenario presents a complex highest and best use question based on the specific circumstances of a subject property. While every property has its own unique characteristics and circumstances, which may lead to different conclusions, these scenarios are designed to demonstrate how you can apply Fannie Mae policy consistently across a range of situations. They are intended to provide practical guidance and support informed, policy-compliant decision-making.

• A resolution is provided for each scenario, along with the appraiser and lender responsibilities with relevant Fannie Mae Selling Guide Supplement: Uniform Appraisal Data (UAD) 3.6 Policy resources.

• The Highest and Best Use Frequently Asked Questions document addresses common questions related to present use, highest and best use, mixed-use properties, analysis of subordinate uses, comparable sales, the URAR, and loan eligibility. The document is available separately and linked throughout the Playbook for easy reference.

To read the Highest and Best Use Playbook, Click Here

To read the separate FAQ document, with 27 Q&As, Click Here

My comments: Many thanks (again) to Dave Towne for writing a summary of the 25 page document at the top of this article. To subscribe to his regular emails, send an email to dtowne@fidalgo.net . Say that you want to subscribe to his list. I have been subscribing for many years.

————————————————————————
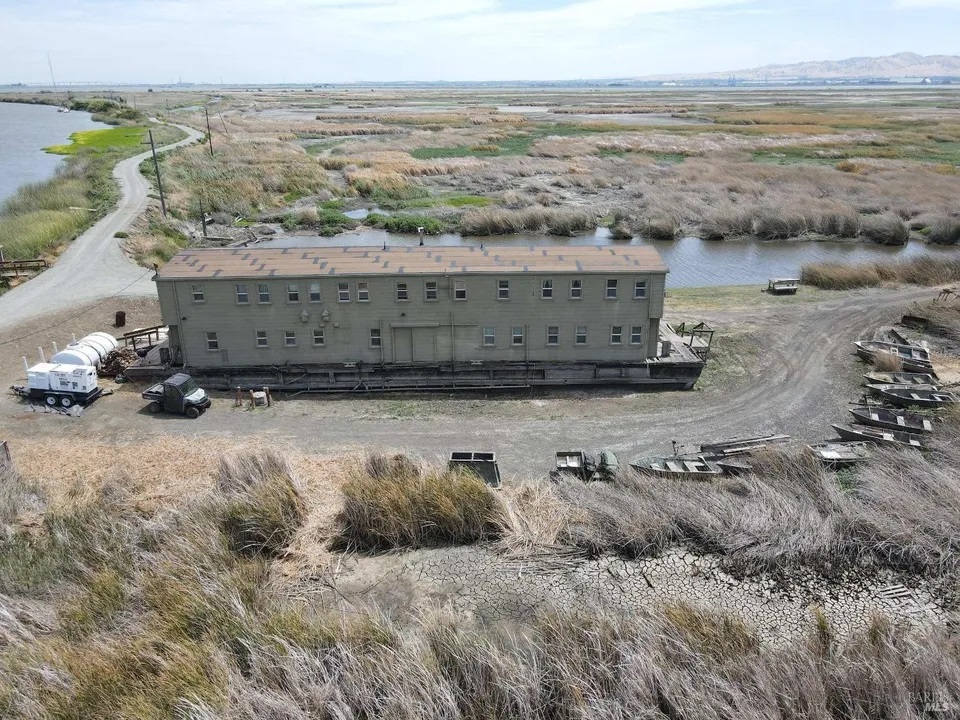
For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat

Excerpts: 16 bedrooms, 5,OOO sq.ft., 399.95 acre lot.

400-acre marsh property which has served as hunter’s have for more than a century has hit the market for $1.5 million.

Concord Farms Duck Club in Suisun City, CA consists of a 16-bedroom, three-bathroom clubhouse.

“It’s just a place where these guys can go out and shoot ducks. It’s been going on for like 100 years plus,” explains listing agent John Ward with California Outdoor Properties. He adds that the hunters take boats out to duck blinds in the marsh where they wait.

“You have your duck call and your shotgun, and you start blowing your whistle or your duck call, and hopefully some birds come in.”

Ward says there are about 160 duck clubs in the Suisun Marsh area, with many of them dating back more than a hundred years. Hunters buy memberships in the clubs.

“There’s just kind of a changing of the guard a little bit now with some of the older guys just getting older,” Ward says.

“[With] this particular club, the members took a vote and decided whether they were going to make an effort to try to get new blood into the club, or [if] they were all kind of ready to hand the torch to the next group. So, they just decided to sell the property.”

The property consists of a 16-bedroom and three bathroom clubhouse, a building which has its own history.

“It’s basically an old barge. They had crews that came in 100 years ago to help build the levees and do a lot of the work out there,” he explains. “So some of these barges turned into duck club houses because they built the levees around them. The men back 100 years ago used those [barges] for their quarters to sleep at night.”

That clubhouse is where the hunters gather after they reach their limit of seven ducks.

“They’ll take their boat back to the club and then make a make a breakfast or a brunch or whatever, and then usually the guys just kind of hang out in the club, and watch college football, watch the NFL, or whatever they want to watch, and it’s usually just kind of a hang [out place].”

My comments: My first appraisal job was in Northern California at the Butte County Assessor’s office. I knew nothing about duck hunting. Many of the guys working there were avid duck hunters, one of the reasons they worked there. I had heard about duck clubs but had never seen one. Fascinating! I learned how they did the hunting, but never tried it.

To see the listing, with many photos, Click Here.

————————————————————————

UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!!

By Doug Smith, SRA

Excerpts: November 2 is not the deadline for the appraiser to deliver a UAD 2.6 appraisal to the lender or AMC. It is the deadline for a new UAD 2.6 appraisal to have already made its initial submission to UCDP.

That distinction matters.

An appraiser could complete a legacy UAD 2.6 appraisal before November 2 and deliver it to the client before November 2—and it could still be too late. If its initial submission to UCDP occurs on or after November 2, UCDP will return a Fatal message and a “Not Successful” status.

The GSE transition timeline provides a remarkably clear example. A UAD 2.6 appraisal is ordered on October 1. It is not initially submitted to UCDP until November 5. The result: Not Successful. The timeline states that UAD 2.6 appraisals must be submitted to UCDP before the mandate or converted to UAD 3.6.

So an appraiser looking at November 2 as “the last day I can finish a legacy appraisal” is looking at the wrong date.

The appraiser’s practical deadline has to be earlier.

To read the full article, Click Here

Editor’s Note: There was no link available for this article online. It is posted on my blog. Every blog post has a link. Putting it on a separate web page is a hassle. I have my weekly email newsletters back to 2012 posted every week on my blog. I will be doing this for articles that are too short for my monthly newsletter, but are very interesting.

My comments : Read this article if you will be doing UAD 3.6 Appraisal reports. UAD 3.6 vs. 2.6 and many other topics are covered. I had never read a detailed description of all the changes and deadlines when UAD 3.6 is adopted. I had just read about “bits and pieces”, and rumors. Thanks to Doug for writing this.

————————————————————————

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.

To read more about the 4 ways, plus information on why I take ads, etc. Click here

————————————————————————

Make use of your driving time by exercising

Appraising is a fairly sedentary job, with most of the time spent sitting in a

car or at a desk. Do you take time to exercise every day? Do feel stressed out

when you are running late for an appointment? Do you feel stressed as a deadline approaches?

One of the best and worst times in appraising is driving. Working out in the

field is what attracted many of us to appraising, including myself. But the time

spent driving is unproductive time.

There are so many stresses today. Exercising is a great stress reducer!

Although the exercises below are for driving, many can also be used in your

office.

I have a personal trainer and exercise almost every day at home and a gym

close to my house. I always listen to podcasts while exercising. Exercising while driving takes no extra time!

Shoulder exercises

Do “shoulder shrugs” where you bring your shoulders up to your ears, one at

time, then both. Drop your shoulders quickly, focusing on the relaxed feeling.

Arm and hand exercises

For steering wheel exercises, put your hands in the 10:00 and 2:00 position.

Squeeze the steering wheel tight, pushing inward for 2-3 seconds, then release.

Keep a relaxed grip on your steering wheel, to keep tension from moving up

to your face, neck, and shoulders. One at a time, lift your fingers off the steering wheel, then lightly put them back.

To read more about this topic, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.

If this article helped you learn how to do exercising while driving, it is worth the subscription price!

————————————————————————

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter :

www.appraisaltoday.com/order or call 510-865-8041

What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

————————————————————————
The 3.6 Rollout: Chaos Now, Clarity Later?

By Logan Dorman · Published September 18, 2026 · Updated

Excerpts: The 3.6 rollout has raised more questions than answers, leaving the industry navigating a landscape that remains unclear.

UAD 3.6 has dominated the appraiser conversation on LinkedIn, yet the irony is that almost nobody truly understands it. That isn’t the fault of appraisers. Even the most experienced professionals and the people positioned as “3.6 experts” have more questions than answers. I recently listened to a panel of appraisers I respect immensely, and even they acknowledged the gaps. The truth is simple: people may be preparing for 3.6, but nobody is fully ready. Admitting that doesn’t make anyone less competent. It reflects the reality of the rollout.

What the industry does have is an abundance of opinions. Some defend the new structure, others condemn it. While the underlying intent of 3.6 may have merit, the rollout has been undeniably chaotic. Functional software is lagging, training has been insufficient, and critical questions remain unanswered. These issues trace directly back to the decision‑makers who pushed the system forward without adequate preparation. But assigning blame won’t solve the problem. The only productive path forward is patience.

There is, however, a positive outcome that has received little attention.

UAD 3.6 will separate the wheat from the chaff. AMCs that rely on low‑fee, high‑volume “rubber stamp” appraisers will struggle because those appraisers will not be able to hide substandard work behind the new level of required detail. While the purpose of 3.6 is to improve the quality of the appraisal report, an important side effect is that it will also highlight the quality of the appraiser. Not all appraisers operate at the same level, and 3.6 will make that impossible to ignore.

To read the article and over 50 appraiser comments, Click Here

My comment: Good to read something positive about UAD 3.6!

————————————————————————

Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI

By Dustin Harris

Excerpts: When was the last time a private client told you they actually enjoyed reading your appraisal report? Not “thanks, got it.” Enjoyed it. Sat down, read it, understood it, maybe even showed it to somebody.

I’m guessing never. And I don’t blame the client one bit.

Our reports are built for underwriters and algorithms and secondary market compliance. That’s fine, that’s what they’re for. But when a homeowner, or a divorce attorney, or an estate executor gets that same 35-page PDF with the grids and the boilerplate and the standardized fields, they don’t feel informed. They feel buried.

An interactive web report flips all of that. You’re not handing them a document anymore, you’re meeting them where they already live, which is on their phone, scrolling.

So what does this actually look like? Picture sending your client a password protected link along with their formal report. They open it up and right at the top is a great photo of the property with your value opinion and effective date front and center, no hunting required.

To read more, Click Here

My comments: Very interesting! Definitely worth trying. No UAD 3.6 for non-lender appraisals!

————————————————–

NO UAD 3.6 UPDATE THIS WEEK FROM ME. SEE DOUG SMITH’S ARTICLE ON “MANY DEADLINES!” ABOVE

————————————————————————

HOW TO USE THE NUMBERS BELOW.

Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down in 2026

———————————————————————–

Mortgage applications decreased 1.5 percent from one week earlier

WASHINGTON, D.C. (September 23, 2026) — Mortgage applications decreased 1.5 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending September 18, 2026. Last week’s results included an adjustment for the Labor Day holiday.

The Market Composite Index, a measure of mortgage loan application volume, decreased 1.5 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 9 percent compared with the previous week. The Refinance Index decreased 3 percent from the previous week and was 62 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 1 percent from one week earlier. The unadjusted Purchase Index increased 9 percent compared with the previous week and was 11 percent lower than the same week one year ago.

“Mortgage rates vaulted higher last week, with the 30-year fixed rate at 7.12 percent – the highest level since May 2024. With fixed rates much higher, more borrowers opted for ARMs, with the ARM share reaching 9.8 percent, as rates for 5/1 ARMs were more than a percentage point lower than those for fixed rate loans,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “Applications for both refinance and purchase loans declined further last week, noting that the comparison is to the week that included the Labor Day holiday. With this week’s decline, the pace of refinancing fell to its slowest pace since February 2025.”

The refinance share of mortgage activity decreased to 39.3 percent of total applications from 39.4 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 9.8 percent of total applications.

The FHA share of total applications decreased to 16.7 percent from 16.9 percent the week prior. The VA share of total applications decreased to 12.0 percent from 12.4 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.4 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 7.12 percent from 6.97 percent, with points increasing to 0.73 from 0.72 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) increased to 7.15 percent from 7.03 percent, with points decreasing to 0.53 from 0.59 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 6.78 percent from 6.62 percent, with points increasing to 0.96 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 6.43 percent from 6.30 percent, with points increasing to 1.15 from 0.98 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.10 percent from 6.23 percent, with points decreasing to 0.76 from 0.99 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

————————————————————————


Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
Avoiding Court: A Common Sentiment Among Appraisers

Newz: Cyber Attack Risk for Appraisers,

Avoiding Court: A Common Sentiment Among Appraisers

May 1, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Avoiding Court: A Common Sentiment Among Appraisers
  • Cyber Insurance: Why It’s Time for Appraisers to Protect Themselves By Isaac Peck, Senior Broker at OREP.org
  • Electrochemist’s Exclusive Private Island Escape With 9-Hole Golf Course and Helipad Hits the Market in Florida for $89 Million
  • Hype Heretics – Twisting the narrative to create hype. By JoAnn Apostol
  • MY AD: What is a Good Appraiser?
  • April 2026 Housing Insights: A Market Searching for Stability, By Kevin Hecht, Appraiser and Economist
  • A new Scope of Work, By George Dell, MAI
  • MBA: Mortgage applications decreased 1.6 percent from one week earlier

——————————————-


—————————————————

Cyber Insurance: Why It’s Time for Appraisers to Protect Themselves

By Isaac Peck, Senior Broker at OREP.org

Excerpts: You log in, expecting to send a report or check your schedule for the coming week, only to find your system locked, client files gone, and a message blinking on the screen:

“YOUR FILES ARE ENCRYPTED

To regain access, you must pay a ransom. Do not attempt to decrypt or modify the files yourself.

Any unauthorized action will result in permanent data loss.

Payment instructions are below. You have 72 hours.”

Directly below the words, a clock begins counting down.

You feel panic setting in.

To make matters worse, you had committed to delivering a rush appraisal to the lender/AMC this morning for a time-sensitive closing. You can’t access reports, contact clients, or meet deadlines. You’re losing money, time, and worst of all, your clients’ trust.

Directly below the words, a clock begins counting down.

This type of mentality only compounds the problem. According to recent national data, more than half of U.S. cyberattacks now target small businesses, not large corporations. Firms with fewer than 100 employees are significantly more likely to be targeted than larger companies, largely because they lack dedicated IT staff, formal security protocols, and incident-response plans. In other words, they’re easier targets.

The financial consequences are not theoretical. According to Verizon’s 2024 Data Breach Investigations Report, small business data breaches can cost anywhere from $120,000 to over $1.2 million, depending on severity. Other industry studies released this summer put the average cost of a single cyber incident at roughly $25,000—far more than most appraisal businesses can absorb without serious disruption.

Unique Risks for Appraisers

Home appraisers face unique cyber risks that make them especially vulnerable to digital attacks. Unlike larger firms with dedicated IT teams, most appraisers operate as solo practitioners or small businesses.

Nevertheless, even the smallest appraisal offices handle highly sensitive data every day: property details, borrower information, lender communications, and access credentials all flow through their systems, often via unsecured emails or cloud-based platforms.

The Role of Insurance

When a cyber incident hits, speed matters. For appraisers, the real damage often isn’t just the ransom demand or the technical cleanup—it’s the downtime, the missed deadlines, and the loss of client confidence that follows.

Cyber insurance exists to help businesses recover quickly and responsibly. For appraisers, that means having access to technical experts who can investigate what happened, contain the breach, and restore systems so work can resume. It also means guidance on how to communicate with lenders, clients, and other parties if sensitive information is compromised.

To read more, Click Here

My comments: Read this article. I have received information from several appraiser E and and O companies about cyber insurance. And read about the risks online. This article is definitely the best I have read as it explains the details of what a cyber attack means for appraisers. Since it was from an E and O carrier I did not know how much useful information it had. I’m glad I read it and wrote about it.

Read more!! →

New URAR – Mixed Feedback

Newz: UAD 3.6 – 10 Biggest Changes,

UAD 3.6 – Mixed Feedback

April 17, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: The Fine Print
  • The 10 Biggest Changes in the New URAR, By Kevin Hecht
  • Tiny Vermont Home That Spans Less Than 1,000 Square Feet Hits the Market for the Huge Price of $1.2 Million
  • Why Appraisers Write in the Third Person—and Whether First-Person Reporting Improves Clarity, By Jamie Owen
  • MY AD: Appraisal: Profession, Industry or Trade? by Martin Wagar
  • Rollout of 3.6 Receives Mixed Feedback, By Isaac Peck, Publisher Working RE
  • Starter Homes Are Disappearing—Are Modular and Manufactured Houses the Answer?
  • MBA: Mortgage applications increased 1.8 percent from one week earlier

———————————————————


——————————————————————-

The 10 Biggest Changes in the New URAR

By Kevin Hecht

Excerpts: The redesign of the Uniform Residential Appraisal Report is the largest overhaul of residential appraisal reporting in nearly three decades.

While the underlying appraisal principles remain the same, the structure, workflow, and level of detail in the report are changing in meaningful ways.

Here are the ten changes appraisers are most likely to notice.

Topics:

1. One Dynamic Report Replaces Multiple Legacy Forms

2. Reports Will Adapt to the Assignment

3. Data Fields Are More Granular

4. Commentary Is Integrated Throughout the Report

5. Scope of Work Drives Report Content

6. Inspection Observations Are More Structured

7. The Sales Comparison Approach Is Still Central

8. Software Platforms Will Change

9. Reports Will Include Both Narrative and Structured Data

10. The Transition Will Take Time

Summary

The new URAR represents a fundamental shift in residential appraisal reporting, moving the profession away from rigid, form‑driven responses and toward clearer, more transparent analysis.

While the core appraisal principles remain unchanged, how appraisers communicate their reasoning, observations, and conclusions will look different under the redesigned framework.

By understanding the most significant changes now, appraisers can better prepare for the transition and continue producing credible, well‑supported appraisal reports in an evolving reporting environment.

To read more, Click Here

My comments: Good topics list and summary. Read the details. Well written and understandable.

Read more!! →

AI and Appraisers

Newz: UAD 3.6 Started for Lenders, AI and Appraisers

January 30, 2026

—————————————————————————–

What AI Means For Appraisers

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

——————————————————————–


What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Safety issues not fixed
  • 7.5 Things AI Is Already Doing Better Than Most Appraisers (And Why That’s Okay) By Mark Buhler
  • EXCLUSIVE: Tech Mogul Lists His Custom-Built Coral Gables Megamansion for Sky-High Price of $22 Million
  • Critical Thinking and the Intellectual Deficit in Real Estate Appraisal Qualifying Education by Timothy Andersen
  • MY AD: Appraisers’ Guide to the New URAR by Dave Towne
  • GSEs: Available Now in Broad Production: UAD 3.6 and Forms Redesign
  • URAR: Expect The Unexpected. How UAD 3.6 affects lenders
  • MBA: Mortgage applications decreased 8.5 percent from one week earlier

————————————–

7.5 Things AI Is Already Doing Better Than Most Appraisers (And Why That’s Okay)

By Mark Buhler

A while ago I wrote about “7.5 Things Appraisers Can Do That Artificial Intelligence Cannot”—the human parts of the job AVMs and algorithms still can’t touch: judging condition and quality, interpreting oddball features, smelling the house, defending adjustments, testifying in court, and exercising professional judgment under pressure.

None of that has changed.

What has changed is the toolset. AI is already doing parts of the workflow faster, cheaper, and more consistently than most humans—not the appraisal itself, but much of the heavy lifting underneath it:

Data gathering and sorting

Pattern detection

First-draft writing

Basic consistency and error checks

You will not beat AI at those tasks. The good news is you do not need to.

7.5 Tools you need:

1. Sifting Massive Datasets for Patterns

2. 2. Generating a First-Pass Comp Set

3. Producing Market Metrics and Adjustment Support on Demand

In my first article, I argued that AI cannot judge condition, interpret quirks, smell the house, testify in court, or exercise professional judgment. That remains true.

What has changed is the gap between appraisers who leverage AI and those who pretend it does not exist. The market is looking for valuation professionals who can…

To read more, Click Here

My comments: Definitely worth reading, including all 7 of the Tools.

——————————————————


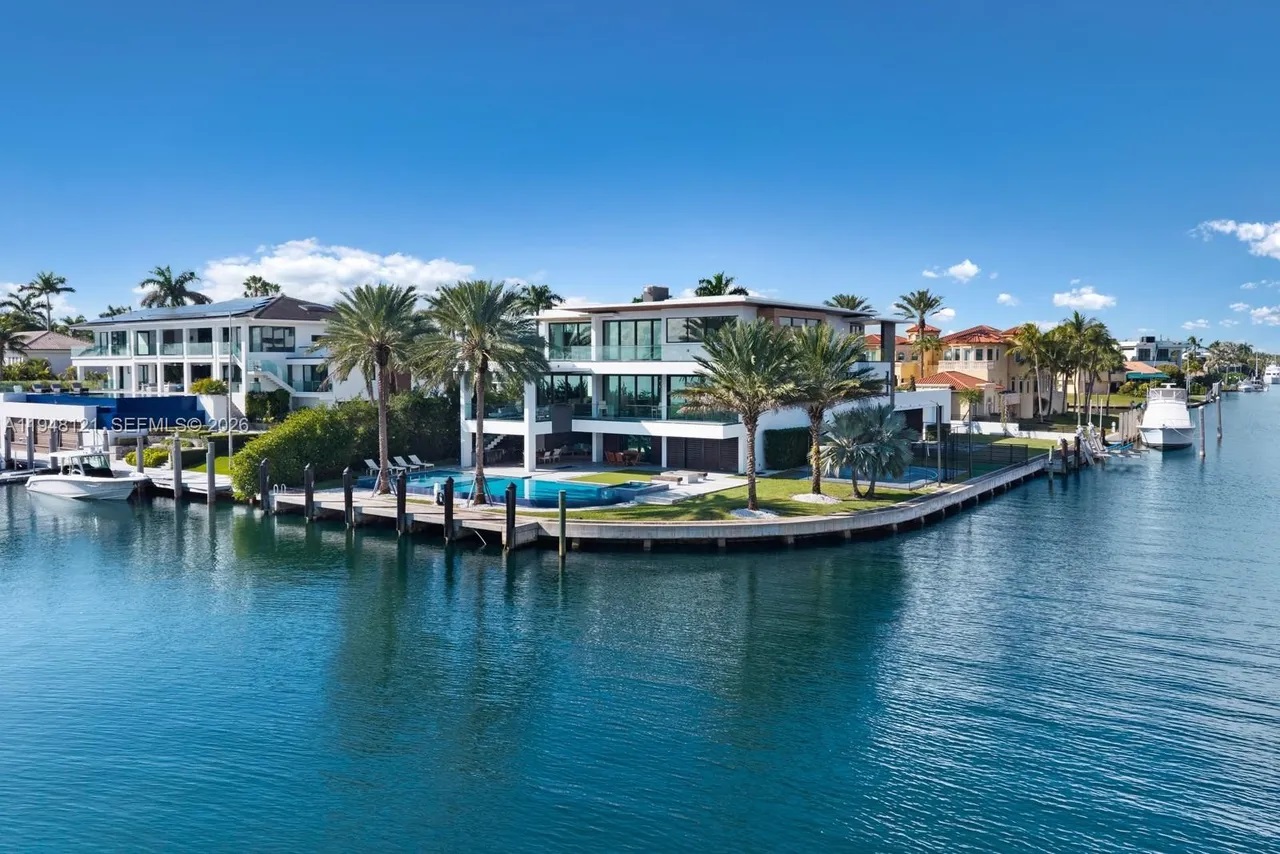
EXCLUSIVE: Tech Mogul Lists His Custom-Built Coral Gables Megamansion for Sky-High Price of $22 Million

Excerpts: 7 bedrooms, 7.5 baths, 7007 sq.ft., 0.47 acre lot, built in 2018

It was the unobstructed views out over the water that first drew the tech expert to the property, as well as the privacy offered by its location in a secure gated community, and the fact that the Bahamian island chain of Bimini is just a 1.5-hour boat ride from the home’s dock.

From the outside, the home could be mistaken for a resort thanks to its lavish pool, built-in barbecue, firepit lounge, outdoor kitchen, expansive waterfront terraces, and a basketball or volleyball court by the water—all of which make for a rare backdrop of relaxation and play.

Elsewhere on the grounds, there are two private docks that accommodate a superyacht of more than 100 feet, a 30,000-pound boat lift, and access to Biscayne Bay.

To read more, Click Here

To see the listing with an aerial view, virtual tour and 60 photos, Click Here

————————————————————-

Critical Thinking and the Intellectual Deficit in Real Estate Appraisal Qualifying Education

by Timothy Andersen, MAI The Appraiser’s Advocate

Excerpts: It is the premise of this essay that critical thinking, analytical rigor, integrative synthesis, and dialectical method are indispensable to the cultivation of competent real estate appraisers and the concomitant production of credible appraisals and non-misleading appraisal reports.

Yet, curiously, these conceptual pillars are either wholly absent or conspicuously marginalized within the current corpus of real estate appraisal qualifying education (QE). That QE in its present form is devoid of any formal engagement with these concepts suggests a foundational deficiency that imperils the credibility of both practice and pedagogy.

Appraisal is, at its core, a dialectical enterprise. The seller posits a value—often broker-influenced and aspirational. The buyer counters with skepticism and a desire for a discount. The broker inserts pecuniary incentives into the mix, motivated by the commission structure. The appraiser is thrust into this cauldron of competing value claims, charged with the burden of arbitrating truth. The appraiser must navigate opposing viewpoints, adjudicate conflicting data, and deliver a resolution rooted in evidence and reason.

In this sense, each appraisal is a dialectical negotiation, an intellectual endeavor wherein the appraiser becomes not merely a market technician but a philosophical mediator. Such work demands a skill set that far exceeds the filling of forms or the clicking of dropdown menus. It requires a mind trained in critical discernment, analytical rigor, synthetic coherence, and dialectical resolution, not merely in filling out a reporting form.

Yet, current appraisal QE and CE, and some of their providers, entrenched in their pedagogical inertia, fail to cultivate these competencies. They privilege mechanics over meaning, technique over thought. The consequence of such tactics is clear: we produce technicians, not scholars; form-fillers, not thinkers.

To read more, Click Here

My comments: This article explains what is missing in classes required for licensing. What you learn when first starting appraising is very, very important so you don’t have to try to learn it later.

Unfortunately after licensing started many new appraisers had not very good education. The appraisal professional associations, such as the Appraisal Institute (and predecessor associations) would not offer trainee classes. They only offered classes for getting designations. I had to refer them to the local “how to fill out a form” classes which were not very good.

The plan for appraisers to train appraisers did not work out well for many new appraisers. Appraisers lacked experience in teaching and did not want to take the time to train appraisers. Prior to licensing, most appraisers were staff appraisers at lenders who provided training. I was trained at an assessor’s office.

——————————————————————–

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday Posted by noon Friday

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page. NOTE: the popular ads with liability tips are below the first topic on my blog posts.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the left of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block. The newsletters have abbreviated titles, taken from their blog posts.

To read more about the 4 ways, plus information on why I take ads, etc.

Click here

——————————————————–

Train the Trainer Class for GSEs New URAR and UAD 3.6

Appraisers’ Guide to the New URAR

In the May 2025 issue of Appraisal Today

By Dave Towne

Excerpts: Quality and Condition Ratings Updated and Appendix F-1

We learned that the Definitions for Q and C have been updated for more

clarity.

These will be in a new Appendix F-1, (available on the GSE web sites) which

appraisers should review BEFORE beginning to do UAD 3.6 URAR Reports!

I have to keep F-1 running in the background on my computer, and will do

that when teaching. F-1 is about 350 pages and shows most all entries that are required on the new reports.

Secondly, the Report will allow for better reporting of Q & C ratings for

various components. And additional property amenities can be selected from a list or drop-down.

In most cases, the Report will involve both office desktop and field tablet

inputting of data… which at this point appears to be more comprehensive than is currently required. Will the lenders recognize this fact, and correspondingly tell their lending client that the “appraisal Report” will cost more than what it might have in the past?

More importantly, will appraisers quit accepting low-ball fee assignments?

These are unknown at this point.

One more point, based on my review of the class material: this new process

is demanding a much more intensive and precise gathering of property detail than appraisers currently do.

It will take more time to do in the field than appraisers currently spend, and if

the appraiser transfers the field data back to their office desktop for completion, that will entail more time.

The ability to do complete inspections with a piece of paper on a clipboard is

going to end. A tablet or large smart phone is strongly recommended.

To read the full article and more newer articles on UAD 3.6, plus 3+ years of previous issues, subscribe to the paid Appraisal Today at www.appraisaltoday.com

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason! You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

What’s the difference between the Appraisal Today free Weekly email newsletter and the paid Monthly newsletter? Click here for more info.Subscribe to Monthly Newsletter

——————————————

If you are a paid subscriber and did not receive the

January, 2026 issue emailed on Friday January 2, 2026 please email info@appraisaltoday.com, and we will send it to you. You can also hit the reply button. Be sure to include a comment requesting it. Or, call 510-865-8041
Available Now in Broad Production: UAD 3.6 and Forms Redesign

UAD 3.6 and Forms Redesign Broad Production Period is here.

The Uniform Appraisal Dataset (UAD) 3.6 and Forms Redesign Broad Production period starts today, January 26, 2026, with a mandate of November 2, 2026. All lenders are now permitted to submit UAD 3.6 appraisal reports to the Uniform Collateral Data Portal® (UCDP®). EMAIL DATED 1-26-26

The Uniform Appraisal Dataset (UAD) 3.6 and Forms Redesign Broad Production Period begins today, January 26, 2026. All lenders are now permitted to submit UAD 3.6 appraisal reports to the Uniform Collateral Data Portal® (UCDP®).

Submission of UAD 3.6 appraisal reports is not yet mandatory; however, lenders that have updated their systems and processes to support UAD 3.6 appraisal reports – including working with an appraisal software provider whose software has been verified for UAD 3.6 – are encouraged to begin integrating appraisal reports that use UAD 3.6 into their workflow. Gradually integrating UAD 3.6 appraisal reports will help lenders prepare for a full transition by the November 2, 2026 mandate, when all appraisal reports on loans sold to Freddie Mac or Fannie Mae must use UAD 3.6

WHAT THIS MEANS FOR APPRAISERS NOW: Appraisers will still be providing UAD 2.6 – the current forms. You will have time to learn UAD 3.6 appraisals. The demand for the UAD 2.6 will decline over time as lenders get set up for UAD 3.6.

To read the official original copy of what Freddie says, Click Here

Comments from Dave Towne on 1-27-26

Editor’s comment: I have been reading Dave’s emails for a long time. They are reliable.

What this means is the process to order appraisals, appraisal completion using software coded for the New URAR/UAD 3.6 data base, submittal back to the appraiser client, and eventual upload to the GSE’s can now happen. However, during this phase, the legacy appraisal forms and back end processing can also be used.

But the current reality is only 2.5 appraisal software vendors and few mortgage lenders are actually able to do this new process in what was expected to be full processing by now.

Two of the software vendors apparently have their software fully coded and approved to work with UAD 3.6. The third vendor has the ‘front end’ of their software working, but some of the other internal functions are not yet included which can somewhat impede the appraisers interaction. Two of the well-known vendors, and another newer vendor do not yet have their software fully approved by the GSE’s – which is required before the lender can allow the appraiser to use those. This is a real conundrum at present.

The process of updating the appraisal inspection and reporting beyond our current legacy actions sounds simple, “on paper”, as they say. The same applies to the lender back-end systems. In actual implementation it’s a daunting process to write software to do what the GSE’s expect. And from what I’ve been told, the software vendors apparently were not fully consulted early on.

There currently are SIX appraisal software vendors independently charged with designing their software to work with the UAD 3.6/MISMO system and functionality.

The timeline from the GSE’s shows the full cut-over date to the New URAR/UAD 3.6 to be Monday, Nov. 2, 2026. Per the GSE plan, this means:

Submit 3.6 Only – November 2, 2026 – Lenders must use UAD 3.6 for all new submissions on or after this date. Revisions allowed for previously submitted

Will this date ‘hold’ throughout the mortgage lending arena? I won’t speculate because I dropped my crystal ball two days ago when I got out of my vehicle and it shattered on the pavement! It depends on all vendor software operating correctly, and all lender back end processing systems up and running properly.

dtowne@fidalgo.net

www.towneappraisals.com

Mount Vernon, WA

———————————————————————

URAR: Expect The Unexpected

How UAD 3.6 affects lenders

Editor’s notes: Published by National Mortgage Professional. A good look at what lenders and appraisers need to know plus comments by an appraiser, Dan Figurski.

Broad production opens January 26, 2026, when all lenders may submit the new format alongside the legacy UAD 2.6. UAD 3.6 becomes mandatory for all new GSE appraisal submissions on November 2, 2026, and UAD 2.6 will fully retire in May 2027.

WHAT THIS MEANS FOR APPRAISERS NOW: Appraisers will still be providing UAD 2.6 – the current forms. No one knows when UAD 3.6 software will be ready for appraisers to use from all vendors and when lenders will be set up for it. Change required final date to 11-2-27 or later??

Key changes include the elimination of individual form numbers, expanded and standardized field sets, updated condition and quality definitions, and enhanced data structures that improve automation, quality control, and interoperability with loan origination systems. Lenders must ensure technology readiness, update systems to support UAD 3.6, and adjust quality control processes accordingly. FHA’s adoption is expected to begin in spring 2026, extending the new format beyond GSE‑conforming business.

Appraiser comments (interview):

NMP: Are there any unexpected changes that may surprise originators?

Figurski: One change in the redesigned URAR that might catch originators by surprise is how clearly property issues will be highlighted in the new reports.

In the past, if there was a concern with a property — say a safety hazard, a structural problem, or evidence of water damage — you’d have to really dig through the report to find it. On the new reports, those issues will be front and center at the beginning of the report. Originators will know very quickly whether there are problems that could influence the transaction or collateral risk.

NMP: What are the repercussions for those who are unprepared for implementation?

Figurski: The redesigned URAR will create a lot of efficiencies for lenders, originators, and servicers, but it’s a complete overhaul of how appraisal information has been delivered in the past. The structure looks different, the way information is presented is different, and there are more details and data fields than before. Companies that aren’t updating their workflows, training their teams, or working closely with their partners to prepare for these changes will struggle to keep pace.

On the other hand, those that are putting in effort now will be in a strong position to benefit.

NMP: What other positive features have you learned about?

Figurski: Something I thought was interesting was that the new report allows appraisers to confirm whether a property has broadband internet access. Considering how heavily our society relies on the internet — whether for streaming movies, working from home, running home security systems, or even supporting smart appliances — a strong internet connection is almost as important as having electricity or running water. By formally including it in the appraisal, the redesigned URAR acknowledges how central connectivity has become to both property value and livability.

To read more, Click Here

My comments: Definitely worth reading to see what will change for lenders. Also, appraiser comments on why the internet broadband data is provided.

—————————————————————–

HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, Click Here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down. We are all waiting for rates to drop lower in 2026.

Mortgage applications decreased 8.5 percent from one week earlier

WASHINGTON, D.C. (January 28, 2026) — Mortgage applications decreased 8.5 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending January 23, 2026. This week’s results include an adjustment for the Martin Luther King Jr. Day federal holiday.

The Market Composite Index, a measure of mortgage loan application volume, decreased 8.5 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 16 percent compared with the previous week. The Refinance Index decreased 16 percent from the previous week and was 156 percent higher than the same week one year ago. The seasonally adjusted Purchase Index decreased 0.4 percent from one week earlier. The unadjusted Purchase Index decreased 4 percent compared with the previous week and was 18 percent higher than the same week one year ago.

“Mortgage rates increased for the first time in a month, and as expected, refinance applications fell by 16 percent. The 30-year fixed rate was the highest in three weeks at 6.24 percent,” said MBA’s Joel Kan, Vice President and Deputy Chief Economist. “FHA refinance activity bucked the overall trend and increased, as FHA rates remained almost 20 basis points lower than conforming rates. With rates holding in the 6 percent range, the refinance market is likely to remain sensitive to week-to-week rate movements.”

Added Kan, “Purchase applications were 18 percent higher than last year’s pace, and the average loan size stayed at its highest level since September 2025, signaling that prospective homebuyers remain active at the start of 2026.”

The refinance share of mortgage activity decreased to 56.2 percent of total applications from 61.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 7.6 percent of total applications.

The FHA share of total applications increased to 18.6 percent from 15.9 percent the week prior. The VA share of total applications decreased to 14.7 percent from 16.2 percent the week prior. The USDA share of total applications increased to 0.5 percent from 0.4 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 6.24 percent from 6.16 percent, with points increasing to 0.55 from 0.54 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 6.34 percent from 6.39 percent, with points increasing to 0.40 from 0.38 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 6.06 percent from 6.04 percent, with points increasing to 0.75 from 0.73 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 5.64 percent from 5.55 percent, with points decreasing to 0.61 from 0.65 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs increased to 5.56 percent from 5.42 percent, with points increasing to 0.80 from 0.62 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.


Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email: ann@appraisaltoday.com

Online: www.appraisaltoday.com
Crazy Appraiser Stories

Newz: Crazy Appraiser Stories,
How to Do Regression, Resolutions

CHANGE YOUR TEMPLATES!!

January 2, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Borrower Wants Answers Appraiser Can’t Give
  • Off the Rails: Crazy Appraiser Stories
  • Inside Pacific Palisades’ Most Expensive Home—a $39.5 Million Hilltop Marvel
  • How to Build a Regression Model in Excel: A Guide for Real Estate Appraisers by Jim Amorin
  • Why Resolve anything? By George Dell, MAI
  • MBA, Fannie Mae see 2027 (and 2026) housing markets very differently
  • MBA STATS – None This Week

Crazy Appraiser Stories!!

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

——————————————————

Off the Rails: Crazy Appraiser Stories

You’ve all got stories of crazy inspections: eccentric collections, mysterious apparitions, and unorthodox decor. Here are a few we found to be the most Buzzworthy.

Excerpts: Reflections

My assignment: a log home in the middle of the city. I go into the owner’s suite, and right in the middle of the room is this built-in whirlpool tub up on a pedestal with velvet steps leading up to it. The whole ceiling is just mirrors. I think, How am I going to deal with this? The owner is so proud of this custom owner’s suite they’ve built.

It isn’t something that the normal market would want, so it has a certain…market impact, let’s say. I handled it by cost to cure.

—Jared Preisler

Let That Sink In

When I was an appraiser trainee, I was tagging along with my supervisor on a packed day of about eight appointments. It was mid-January in upstate New York. Trust me when I tell you it was COLD. First appointment, 9am: we finished walking through the inside of the home and headed outside. I began walking around the back yard (tall winter boots on, of course) when I suddenly realized I was about three feet lower than I had been moments ago. I looked down to see brown, icy water pooling around my feet. I struggled to comprehend what was happening as my boots became completely submerged. Seconds later, the homeowner cracked the door open just wide enough to shout, “Watch out for the koi pond! It’s probably covered in snow!”

I spent the rest of the day wearing socks I borrowed from a homeowner and plastic bags stuffed into my boots, while a swampy smell permeated my boss’s car. Lesson learned.

—KWAppraisalGroup

To read more, Click Here


Read more!! →

Q4 2025 Fannie Mae Appraiser Update – AMC Risk, UAD 3.6

Newz: 12 Days of Appraiser Christmas,
Q4 2025 Fannie Mae Appraiser Update –AMC Risk, UAD 3.6

December 19, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: A Family Feud and Intended Use
  • Q4 2025 Fannie Mae Appraiser Update – AMC risk, UAD 3.6
  • 12 Days of Appraiser Christmas
  • Santa’s House is Back on Zillow with a Bold New Holiday Look
  • Highest and Best—and the Highest Value By Richard Hagar
  • AQB Proposed Changes in New Appraiser Requirements
  • MBA: Mortgage applications decreased 3.8 percent from one week earlier
  • ————————————————————

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


——————————————————

Q4 2025 Fannie Mae Appraiser Update

As the year wraps up, we’re focused on what matters most to your success: clarity, consistency, and confidence in every appraisal. This edition gives you practical insights to stay ahead:

  • Several deep-dive articles on Uniform Appraisal Dataset (UAD) 3.6, focused on condition/quality ratings, the inspection component of Scope of Work, disaster mitigation, energy efficiency, and training and resources;
  • Why time adjustments matter—and how to apply them effectively; and
  • Our approach to managing Appraiser Management Company (AMC) risk for stronger compliance and reliability. Excerpts: In Jul. 2025, Fannie Mae began sending letters to AMCs detailing appraisal quality issues identified through Fannie Mae loan quality reviews completed in 2024. Each letter contains a comprehensive list of the issues identified for appraisals associated with that AMC.

To read more, Click Here

My comments: Worth reading. First time I have ever seen comments on AMCs. Good to see that GSEs are looking at AMCs.

————————————————————–

12 Days of Appraiser Christmas

NOTE on video: Click on image and it opens in Youtube.

Very funny!! 3.5 minute video

Sample appraisal requests:

On the fourth day of Christmas my best client sent to me falling

Shacks, three field reviews, two double wides, and a drive by single family.

On the tenth day of Christmas, my best client sent to me 10 tax appeals and eight Mega Mansions.

Singer in this video is comedian David Cassel as the Ukulele Bandito http://www.theukulelebandito.com / (he is not a Portland appraiser, but he is funny)

Many thanks to Gary F. Kristensen, SRA, ASA, AGA at A Quality Appraisals in Portland, Oregon.

My comment: I love this FUN video ;>

Read more!! →