New Fannie Highest and Best Use Playbook

Newz: New Fannie Highest and Best Use Playbook, UAD 3.6 Nov. 2 and Other Deadlines??

September, 25, 2026

ARTICLE LIST:

In Order, Scroll down the page to read

  • LIA AD: Conflicting Assignments and Professional Ethics
  • New Fannie Highest and Best Use Playbook and Q&As
  • For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat
  • UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!! By Doug Smith, SRA
  • MY AD: Make use of your driving time by exercising
  • Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI By Dustin Harris
  • MBA stats: Mortgage applications decreased 1.5 percent from one week earlier
 

Thanks to our Sponsor!!!

Very reasonable prices and good open rates for our ads!

————————————————————

New Fannie Highest and Best Use Playbook and Q&As

By Dave Towne

For those of you doing (or will do) the New URAR/UAD 3.6 mortgage lending reports from now into the future, you need to read and understand this new policy change from FannieMae. Because this new UAD report process also applies to FreddieMac, my presumption is they will issue a policy statement of their own with similar wording.

For the time being, here is the FNMA new policy, issued on Sept. 2, 2026: Highest and best use requirements for Uniform Appraisal Dataset (UAD) 3.6

This policy updates the highest and best use requirements for appraisal reports completed using Uniform Appraisal Dataset (UAD) 3.6.

These changes apply only to UAD 3.6 appraisal assignments to support the new Uniform Residential Appraisal Report (URAR) reporting requirements and do not apply to appraisal reports completed using legacy appraisal report forms.

We updated our policy to:

• require the property’s highest and best use, as improved or as proposed, to be a residential use, rather than requiring it to be the property’s present use;

• define present use, residential use, and subordinate use in the context of highest and best use;

• require the property to be a primarily residential one- to four-unit property, with any non-residential use subordinate to the residential use, replacing the previous “residential in nature” guidance; and

• establish the eligibility criteria and reporting requirements for one- to four-unit residential properties when the present use does not satisfy one or more of the highest and best use tests.

The UAD 3.6 Policy Supplement has been updated to reflect these changes.

Effective: This policy change is effective immediately for appraisal reports completed using UAD 3.6.

Remember, to be USPAP compliant, you can’t “just check the box” on the New URAR/UAD 3.6 data base input field (or on the Legacy forms either) to indicate ‘present use,’ and then move on. You must add a written statement in that site section comment input field explaining why you decided that is the accurate use of the property. Craft your statement to comply with the above policy.

Also remember this: if you decide the property’s H&BU is not Residential use, you must check the box “No.” In most cases, when you do that, the need to complete a full appraisal report ends at that point because the lender cannot proceed with a residential mortgage loan. Your statement needs to define what the actual use is if not Residential. Stop working on the report and contact your client to fully explain the current situation. Let them determine how to proceed.

—————————————————————–

What is in Fannie’s New The Highest & Best Use 25 page Playbook (Per Fannie)

• This playbook provides key concepts and illustrative scenarios to help industry participants better understand how the results of the highest and best use (HBU) may affect loan eligibility.

• Each scenario presents a complex highest and best use question based on the specific circumstances of a subject property. While every property has its own unique characteristics and circumstances, which may lead to different conclusions, these scenarios are designed to demonstrate how you can apply Fannie Mae policy consistently across a range of situations. They are intended to provide practical guidance and support informed, policy-compliant decision-making.

• A resolution is provided for each scenario, along with the appraiser and lender responsibilities with relevant Fannie Mae Selling Guide Supplement: Uniform Appraisal Data (UAD) 3.6 Policy resources.

• The Highest and Best Use Frequently Asked Questions document addresses common questions related to present use, highest and best use, mixed-use properties, analysis of subordinate uses, comparable sales, the URAR, and loan eligibility. The document is available separately and linked throughout the Playbook for easy reference.

To read the Highest and Best Use Playbook, Click Here

To read the separate FAQ document, with 27 Q&As, Click Here

My comments: Many thanks (again) to Dave Towne for writing a summary of the 25 page document at the top of this article. To subscribe to his regular emails, send an email to dtowne@fidalgo.net . Say that you want to subscribe to his list. I have been subscribing for many years.

————————————————————————
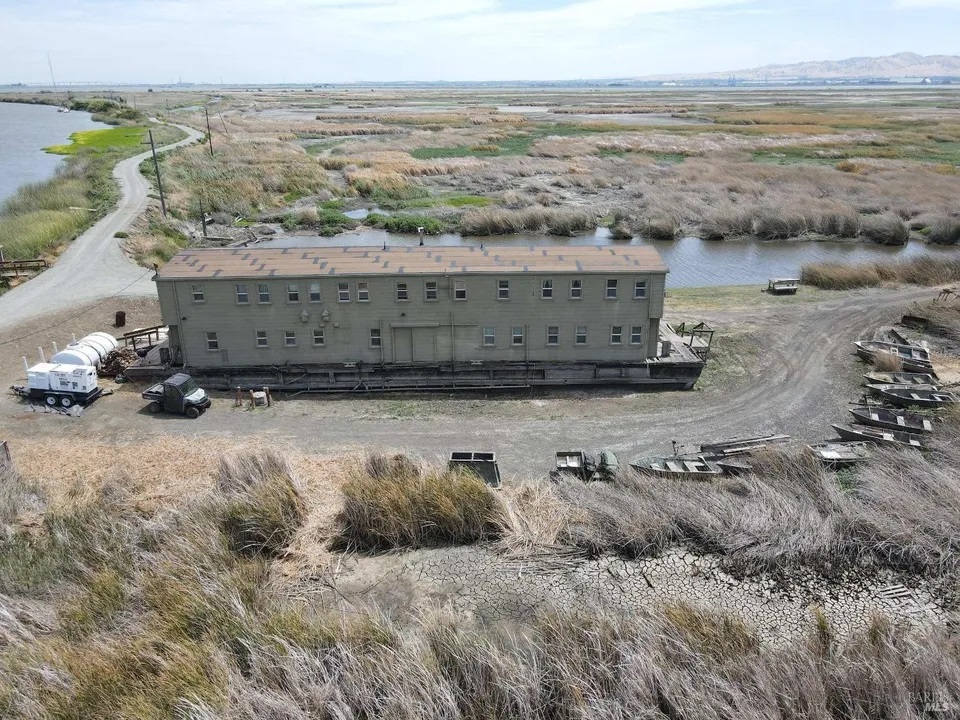
For the Price of a San Francisco Condo, You Can Buy a 400-Acre Historic Marshland Retreat

Excerpts: 16 bedrooms, 5,OOO sq.ft., 399.95 acre lot.

400-acre marsh property which has served as hunter’s have for more than a century has hit the market for $1.5 million.

Concord Farms Duck Club in Suisun City, CA consists of a 16-bedroom, three-bathroom clubhouse.

“It’s just a place where these guys can go out and shoot ducks. It’s been going on for like 100 years plus,” explains listing agent John Ward with California Outdoor Properties. He adds that the hunters take boats out to duck blinds in the marsh where they wait.

“You have your duck call and your shotgun, and you start blowing your whistle or your duck call, and hopefully some birds come in.”

Ward says there are about 160 duck clubs in the Suisun Marsh area, with many of them dating back more than a hundred years. Hunters buy memberships in the clubs.

“There’s just kind of a changing of the guard a little bit now with some of the older guys just getting older,” Ward says.

“[With] this particular club, the members took a vote and decided whether they were going to make an effort to try to get new blood into the club, or [if] they were all kind of ready to hand the torch to the next group. So, they just decided to sell the property.”

The property consists of a 16-bedroom and three bathroom clubhouse, a building which has its own history.

“It’s basically an old barge. They had crews that came in 100 years ago to help build the levees and do a lot of the work out there,” he explains. “So some of these barges turned into duck club houses because they built the levees around them. The men back 100 years ago used those [barges] for their quarters to sleep at night.”

That clubhouse is where the hunters gather after they reach their limit of seven ducks.

“They’ll take their boat back to the club and then make a make a breakfast or a brunch or whatever, and then usually the guys just kind of hang out in the club, and watch college football, watch the NFL, or whatever they want to watch, and it’s usually just kind of a hang [out place].”

My comments: My first appraisal job was in Northern California at the Butte County Assessor’s office. I knew nothing about duck hunting. Many of the guys working there were avid duck hunters, one of the reasons they worked there. I had heard about duck clubs but had never seen one. Fascinating! I learned how they did the hunting, but never tried it.

To see the listing, with many photos, Click Here.

————————————————————————

UAD 3.6 — Whose November 2 Deadline Is It? There are many dates!!

By Doug Smith, SRA

Excerpts: November 2 is not the deadline for the appraiser to deliver a UAD 2.6 appraisal to the lender or AMC. It is the deadline for a new UAD 2.6 appraisal to have already made its initial submission to UCDP.

That distinction matters.

An appraiser could complete a legacy UAD 2.6 appraisal before November 2 and deliver it to the client before November 2—and it could still be too late. If its initial submission to UCDP occurs on or after November 2, UCDP will return a Fatal message and a “Not Successful” status.

The GSE transition timeline provides a remarkably clear example. A UAD 2.6 appraisal is ordered on October 1. It is not initially submitted to UCDP until November 5. The result: Not Successful. The timeline states that UAD 2.6 appraisals must be submitted to UCDP before the mandate or converted to UAD 3.6.

So an appraiser looking at November 2 as “the last day I can finish a legacy appraisal” is looking at the wrong date.

The appraiser’s practical deadline has to be earlier.

To read the full article, Click Here

Editor’s Note: There was no link available for this article online. It is posted on my blog. Every blog post has a link. Putting it on a separate web page is a hassle. I have my weekly email newsletters back to 2012 posted every week on my blog. I will be doing this for articles that are too short for my monthly newsletter, but are very interesting.

My comments : Read this article if you will be doing UAD 3.6 Appraisal reports. UAD 3.6 vs. 2.6 and many other topics are covered. I had never read a detailed description of all the changes and deadlines when UAD 3.6 is adopted. I had just read about “bits and pieces”, and rumors. Thanks to Doug for writing this.

————————————————————————

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.

To read more about the 4 ways, plus information on why I take ads, etc. Click here

————————————————————————

Make use of your driving time by exercising

Appraising is a fairly sedentary job, with most of the time spent sitting in a

car or at a desk. Do you take time to exercise every day? Do feel stressed out

when you are running late for an appointment? Do you feel stressed as a deadline approaches?

One of the best and worst times in appraising is driving. Working out in the

field is what attracted many of us to appraising, including myself. But the time

spent driving is unproductive time.

There are so many stresses today. Exercising is a great stress reducer!

Although the exercises below are for driving, many can also be used in your

office.

I have a personal trainer and exercise almost every day at home and a gym

close to my house. I always listen to podcasts while exercising. Exercising while driving takes no extra time!

Shoulder exercises

Do “shoulder shrugs” where you bring your shoulders up to your ears, one at

time, then both. Drop your shoulders quickly, focusing on the relaxed feeling.

Arm and hand exercises

For steering wheel exercises, put your hands in the 10:00 and 2:00 position.

Squeeze the steering wheel tight, pushing inward for 2-3 seconds, then release.

Keep a relaxed grip on your steering wheel, to keep tension from moving up

to your face, neck, and shoulders. One at a time, lift your fingers off the steering wheel, then lightly put them back.

To read more about this topic, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.

If this article helped you learn how to do exercising while driving, it is worth the subscription price!

————————————————————————

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter :

www.appraisaltoday.com/order or call 510-865-8041

What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

————————————————————————
The 3.6 Rollout: Chaos Now, Clarity Later?

By Logan Dorman · Published September 18, 2026 · Updated

Excerpts: The 3.6 rollout has raised more questions than answers, leaving the industry navigating a landscape that remains unclear.

UAD 3.6 has dominated the appraiser conversation on LinkedIn, yet the irony is that almost nobody truly understands it. That isn’t the fault of appraisers. Even the most experienced professionals and the people positioned as “3.6 experts” have more questions than answers. I recently listened to a panel of appraisers I respect immensely, and even they acknowledged the gaps. The truth is simple: people may be preparing for 3.6, but nobody is fully ready. Admitting that doesn’t make anyone less competent. It reflects the reality of the rollout.

What the industry does have is an abundance of opinions. Some defend the new structure, others condemn it. While the underlying intent of 3.6 may have merit, the rollout has been undeniably chaotic. Functional software is lagging, training has been insufficient, and critical questions remain unanswered. These issues trace directly back to the decision‑makers who pushed the system forward without adequate preparation. But assigning blame won’t solve the problem. The only productive path forward is patience.

There is, however, a positive outcome that has received little attention.

UAD 3.6 will separate the wheat from the chaff. AMCs that rely on low‑fee, high‑volume “rubber stamp” appraisers will struggle because those appraisers will not be able to hide substandard work behind the new level of required detail. While the purpose of 3.6 is to improve the quality of the appraisal report, an important side effect is that it will also highlight the quality of the appraiser. Not all appraisers operate at the same level, and 3.6 will make that impossible to ignore.

To read the article and over 50 appraiser comments, Click Here

My comment: Good to read something positive about UAD 3.6!

————————————————————————

Rethinking Private Appraisal Delivery: Building Interactive Web Reports with AI

By Dustin Harris

Excerpts: When was the last time a private client told you they actually enjoyed reading your appraisal report? Not “thanks, got it.” Enjoyed it. Sat down, read it, understood it, maybe even showed it to somebody.

I’m guessing never. And I don’t blame the client one bit.

Our reports are built for underwriters and algorithms and secondary market compliance. That’s fine, that’s what they’re for. But when a homeowner, or a divorce attorney, or an estate executor gets that same 35-page PDF with the grids and the boilerplate and the standardized fields, they don’t feel informed. They feel buried.

An interactive web report flips all of that. You’re not handing them a document anymore, you’re meeting them where they already live, which is on their phone, scrolling.

So what does this actually look like? Picture sending your client a password protected link along with their formal report. They open it up and right at the top is a great photo of the property with your value opinion and effective date front and center, no hunting required.

To read more, Click Here

My comments: Very interesting! Definitely worth trying. No UAD 3.6 for non-lender appraisals!

————————————————–

NO UAD 3.6 UPDATE THIS WEEK FROM ME. SEE DOUG SMITH’S ARTICLE ON “MANY DEADLINES!” ABOVE

————————————————————————

HOW TO USE THE NUMBERS BELOW.

Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down in 2026

———————————————————————–

Mortgage applications decreased 1.5 percent from one week earlier

WASHINGTON, D.C. (September 23, 2026) — Mortgage applications decreased 1.5 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending September 18, 2026. Last week’s results included an adjustment for the Labor Day holiday.

The Market Composite Index, a measure of mortgage loan application volume, decreased 1.5 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 9 percent compared with the previous week. The Refinance Index decreased 3 percent from the previous week and was 62 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 1 percent from one week earlier. The unadjusted Purchase Index increased 9 percent compared with the previous week and was 11 percent lower than the same week one year ago.

“Mortgage rates vaulted higher last week, with the 30-year fixed rate at 7.12 percent – the highest level since May 2024. With fixed rates much higher, more borrowers opted for ARMs, with the ARM share reaching 9.8 percent, as rates for 5/1 ARMs were more than a percentage point lower than those for fixed rate loans,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “Applications for both refinance and purchase loans declined further last week, noting that the comparison is to the week that included the Labor Day holiday. With this week’s decline, the pace of refinancing fell to its slowest pace since February 2025.”

The refinance share of mortgage activity decreased to 39.3 percent of total applications from 39.4 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 9.8 percent of total applications.

The FHA share of total applications decreased to 16.7 percent from 16.9 percent the week prior. The VA share of total applications decreased to 12.0 percent from 12.4 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.4 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 7.12 percent from 6.97 percent, with points increasing to 0.73 from 0.72 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) increased to 7.15 percent from 7.03 percent, with points decreasing to 0.53 from 0.59 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 6.78 percent from 6.62 percent, with points increasing to 0.96 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 6.43 percent from 6.30 percent, with points increasing to 1.15 from 0.98 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.10 percent from 6.23 percent, with points decreasing to 0.76 from 0.99 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

————————————————————————


Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
Nobody is Ready for UAD 3.6 Today

Newz:  Nobody is Ready for UAD 3.6,

Time to Take Out the AMC Junk

August 28, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Think carefully before signing a Records Affidavit
  • Nobody is Ready for UAD 3.6 by Isaac Peck, Publisher WorkingRE
  • The famed rotating round house at 4 Harkle Road in Novato is for sale for the first time
  • It’s Time to Take Out the Junk: AMC Practices Exposed by Logan Dorman
  • MY AD: How to reduce stress to be more productive in business and a happier life
  • Becoming an Appraiser: Courage to Grow Beyond Training by Timothy Andersen, MAI
  • UAD 3.6 UPDATE – Comp Photos, Any Future for Residential Appraisers?
  • MBA STATS: Mortgage applications decreased 1.0 percent from one week earlier

Nobody is Ready for UAD 3.6

by Isaac Peck, Publisher WorkingRE

I just got back from Valuation Expo, the nation’s largest and most dynamic conference for real estate appraisers and valuation industry stakeholders. More than 800 people made it to Las Vegas this year.

Appraisers, chief appraisers at appraisal management companies (AMCs), lenders, regulators, software developers, service providers, insurance professionals and more convened to talk about the latest technology and explore where the profession is headed.

The mood was elevated and positive—many attendees were genuinely invigorated and excited about the future. And yet, despite all the positivity, another reality was plainly clear from the conversations: Nobody is ready for UAD 3.6.

While many of the leading software providers received initial approval from Fannie Mae and Freddie Mac (the GSEs) in late 2025 and early 2026, word on the ground is that there are still plenty of bugs to work out.

AMC executives privately shared that they have staff simultaneously testing all the GSE-approved appraisal reporting software so they can troubleshoot and support appraisers when they inevitably run into bugs and errors trying to turn in an assignment. Some of those bugs are being run back to the software companies in real time, as appraisers, AMCs, lenders and software providers work together to find a solution.

In other words, while the GSEs tested the main appraisal report software providers on several different types of assignments, there are so many nuances, data fields and report settings that bugs are surfacing rapidly now that appraisers are finally doing live assignments.

In addition to the software challenges, part of the problem is that most lenders haven’t begun ordering UAD 3.6 reports at all.

I spoke with several regional AMCs. Each had completed just two UAD 3.6 assignments—and in each case, one of the two was a test run the AMC had ordered itself.

If one of the largest mortgage lenders in the country has only done six UAD assignments, how many appraisers have actually completed a UAD 3.6 assignment? The answer is very, very few.

An appraisal software executive shared with me privately that he fears appraisers may be (wrongly) blamed if the rollout goes poorly and the market is disrupted. It would be easy to sell a narrative that “appraisers weren’t ready,” or that appraisers can’t handle the new report format. Such a view clearly misses the point. After all, appraisers don’t control the development of the software, nor do they control when UAD 3.6 reports start getting ordered, to Reuter’s point.

Will we see an avalanche of UAD 3.6 orders in September and October, and will the transition happen smoothly by mid-October? It seems unlikely.

Many thanks to Isaac Peck for “in person” realistic reporting on the Most Popular Topic in appraising – Future of UAD 3.6 and GSEs.

To read more, Click Here

My comments: Definitely worth reading the full article!!! I was unable to attend this conference but have attended many webinars and two “boot camps” via zoom since early 2025. Plus I have written about the problems.

This article was no surprise to me. It puts all the pieces together and has quotes from knowledgeable people, plus what appraisers said.

Read more!! →

Surplus vs. Excess Land for Appraisers

Newz: Surplus vs. Excess Land,
Easement Issues and Liability

August 14, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Easements: Issues and Appraiser Liability
  • Surplus Land vs. Excess Land: What Appraisers Need to Know, By Kevin Hecht
  • Built Different: How the Ranch-Style Home Went from 1930s Architectural Rebel to America’s Favorite Floor Plan
  • Let’s Talk About Letters of Engagement, By Jeff Whaley
  • MY AD: UAD 3.6 Software Evaluation Checklist
  • An Abridged History of the Appraiser Profession, By Kendra Budd, Editor Working RE
  • My UAD 3.6 Tips of the Week
  • MBA: Mortgage applications increased 3.6 percent from one week earlier

———————————————————

Surplus Land vs. Excess Land: What Appraisers Need to Know

By Kevin Hecht

Excerpts: Land valuation is a fundamental aspect of real estate appraisal, influencing property transactions, development decisions, and investment strategies. A key part of the process involves distinguishing between the land that supports the property’s current use and any additional land that may or may not have independent value.

Commonly, a square footage adjustment is made based on lot size differences among comparable properties without one key distinction: whether the difference in land is surplus or excess land. This fails to consider whether the extra land has value independent of the subject property.

Surplus land generally does not contribute value beyond its association with the primary parcel, though it may still add some contributory value in certain market conditions. Excess land, by contrast, has value because it can be divided and sold separately.

Understanding this distinction is essential for developing a credible appraisal.

Surplus Land vs. Excess Land at a Glance

Surplus Land – Cannot be separated and sold independently

Excess Land – Can be divided and sold separately

Surplus Land – No independent highest and best use

Excess Land – May have a different highest and best use

Surplus Land – Typically contributes limited additional value

Excess Land – Has independent value and should be analyzed separately

Surplus Land – Remains part of the primary property

Excess Land – Can potentially support separate development

Key Differences Between Surplus and Excess Land

Surplus and excess land apply to commercial and residential properties. Before determining whether land is surplus or excess, appraisers must consider zoning, highest and best use, surrounding properties and their use, property improvements, and supply and demand for the property and any proposed improvements.

Why the Distinction Matters in Appraisal

Choosing the correct land type has an effect on the final value of the property. Excess land adds value to the subject property and creates future potential. Thus, a higher price per square foot should be assigned to excess land over surplus land.

Ultimately, identifying land type is about more than just checking if a property can be split. It’s about understanding the property’s most productive use under current legal and economic conditions.

To read more, Click Here

My comments: Read this article!! The best comprehensive article I have read on this issue. Understanding Surplus vs. Excess Land is critical in appraising. I have encountered this issue mostly in commercial and agricultural appraisals. It can happen in any type of property.

Unfortunately, residential lender appraisers sometimes encounter this but don’t know much about it. I have appraised it on single family properties. Not understanding what this is of the many ways residential appraisers end up trouble at the state appraisal board because of lack of knowledge and experience.

Read more!! →

Recent Executive Orders Affecting Appraisers

Newz: Recent Executive Orders Affecting    Appraisers, When Appraisers Take the Stand

June 12, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: A case of forgery
  • Recent Executive Orders: Threat, Opportunity, or Both for Appraisers? By Kim Perotti, AXIS AMC
  • $22.8 Million Aspen Home With Its Own Private Waterfall Feels Like a Real-Life Fairy Tale
  • MY AD: If the Standards Are Uniform, Why Isn’t Your License? By Thaddus Dawson, Jr., CG
  • When Appraisers Take the Stand By By David C. Wilkes, Esq., CRE, FRICS and Kevin M. Clyne, Esq., CRE
  • Agents, Are You Using AI to Price Your Listings? By Tom Horn
  • 10K Appraisers. Policy and Advocacy Day, By 10K Appraisers Foundation
  • MBA: Mortgage applications increased 10.8 percent from one week earlier

Recent Executive Orders: Threat, Opportunity, or Both for Appraisers?

By Kim Perotti, a founding partner of AXIS AMC

Excerpts: In March 13, 2026, President Trump signed two Executive Orders that together amount to a clear message for our profession: build more houses, make credit easier, and get the valuation piece done faster and cheaper. We think it’s critically important that our industry discuss the implications.

The two orders are:

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION

AND PROMOTING ACCESS TO MORTGAGE CREDIT

While they are not “about” appraisers, the Executive Orders will absolutely reshape the environment in which we work. Appraisers who treat these as background noise will find the ground shifting under their feet. Those who read them as a roadmap can pick their spots and come out stronger and, more importantly, help shape how they are put into practice.

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION:

Faster, Cheaper Construction – What That Really Means for Your Desk

PROMOTING ACCESS TO MORTGAGE CREDIT: Faster, Cheaper Valuations – Where the Squeeze Shows Up – Second Order

The second order takes direct aim at how loans—and valuations—get done. The theme is unmistakable: streamline, digitize, and de-emphasize technical compliance.

For appraisers, here are the potential realities:

More alternative valuation products: Regulators are being encouraged to expand the use of AVMs, desktop, and hybrid appraisals and reduce full appraisal requirements on low-risk and small-balance loans. You should expect more hybrid and desktop requests and data-only products as well as a clearer dividing line between high-volume, low-margin work and complex, higher-risk assignments.

Pressure on fees and turn times: Agencies are being asked to set “clear appraisal timelines” and cut costs and therefore lenders will likely lean harder on speed and price whenever a waiver, AVM, or hybrid is allowed, and traditional assignment ordering will have to justify itself on risk grounds.

Changes in who can appraise and how: The order invites simplification of appraiser qualification requirements. Easier entry could mean more competitors and lenders may fill low-fee niches with less-experienced personnel or non-traditional vendors.

If your business is built primarily on simple, low-risk assignments, this is a direct competitive challenge.

Alignment of FHA and VA rules: HUD and VA are asked to align standards where risk is comparable, clarify what truly requires pre-closing repairs vs. what’s cosmetic, and expand post-closing repair flexibility.

That could change the frequency and scope of “subject to” conditions, reduce some friction and disputes around FHA/VA appraisals, and make your judgment about safety vs. cosmetic issues more visible and important.

In summation, this order calls for more technology and alternatives, more pressure on traditional appraisals, and more segmentation of valuation products by risk level.

A Clear Fork in the Road for Appraisers

Taken together, these two Executive Orders point in one direction: more volume, more complexity at the edges of the market, and more pressure to commoditize anything that looks “low risk.” Together they create a fork in the road for real estate appraisers:

If you stay in the lane of interchangeable, low-complexity assignments, you will feel the squeeze—from technology, from relaxed standards, and from new entrants.

If you lean into complexity—new construction, manufactured and modular, fringe markets, environmental and hazard issues, FHA/VA nuance—you become harder to replace, not easier.

This doesn’t mean abandoning efficiency or refusing alternative products. It means being fluent in hybrids and desktops so you can decide which work makes sense for you, positioning yourself as the expert when a lender can’t responsibly rely on an AVM or a waiver, and building documented expertise in the exact areas these orders will expand.

To read more, Click Here

My comments: Definitely worth reading. All about what this means for appraisers in detail. The best analysis for appraisers I have read about this executive order. The author is definitely an “insider” as she is Co President of AXIS, a long time AMC. When I wrote one of my first articles on AMCs, I interviewed AXIS.

Read more!! →

The Appraiser Exodus and How to Fix It

Newz: Expanded Intended Users?

The Appraiser Exodus and How to Fix It.

May 8, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Expanding Intended Users? Not So Fast
  • Under Pressure: What’s Driving the Appraiser Exodus and How to Fix It, By David Massey
  • Historic Tudor Estate With English Gardens and Prairie Views Is Listed for $4.7 Million Near Chicago
  • What is a Pre-listing appraisal? Written for Home Owners But Has Good Tips for Appraisers, By Tom Horn
  • MY AD: What Happened When Government Decided That Appraisers Needed Protection, By Cindy Chance, PhD
  • How to See the Potential in Homes That Don’t Look Perfect. Written for Home Owners But Has Good Tips for appraisers
  • More Than 60% of America Is Covered by Drought and Millions of Homes Are at Risk
  • UAD 3.6 Bootcamp, LIVE in Chicago, IL and on Zoom, Wednesday – Friday, May 13th-15th
  • MBA STATS: Mortgage applications decreased 4.4 percent from one week earlier


——————————————————————-

Under Pressure: What’s Driving the Appraiser Exodus and How to Fix It,

By David Massey

Ask any veteran appraiser or physician what has changed most over the past twenty years, and the answer is usually the same: paperwork.

Professions once centered on skill, judgment, and service are now dominated by portals, compliance layers, and third-party control. Burnout rises, independence falls, and a quiet exodus follows.

The American Medical Association reports that physicians now spend nearly two hours on documentation for every hour of patient care.

The appraisal profession is now well into that cycle.

According to the Appraisal Institute’s 2023 Fact Sheet, the number of practicing appraisers in the United States has declined by roughly 8,000 in recent years. The Conference of State Bank Supervisors shows a longer-term drop from about 120,000 appraisers in 2008 to fewer than 96,000 by 2017, a 21 percent decline in less than a decade. IBISWorld reports another six percent employment drop between 2018 and 2023. The U.S. Bureau of Labor Statistics projects only modest growth through 2034, far short of what is needed to replace retirees.

The pipeline is shrinking while demand remains steady.

The National Association of Realtors ® 2023 Appraisal Survey found that more than half of appraisers are now asked monthly, or more often, to complete assignments outside their normal geographic or property-type expertise. More telling, 54 percent cited Appraisal Management Companies as the single greatest challenge to their business. That statistic alone explains much of what has gone wrong.

When I started in this profession, appraisal centered on analysis, interpretation, and professional opinion. I studied neighborhoods, walked properties, and applied experience to market behavior. Today, much of the job revolves around compliance portals, redundant uploads, and layers of review by people who have never inspected a property.

AMCs were created after the 2008 crisis to protect appraiser independence. The idea made sense. The execution has failed. Today, borrowers commonly pay $600 to $700 for an appraisal, while the appraiser often receives about half of that after AMC fees. Turn times lengthen. Panel depth shrinks. Geographic competency erodes. And experienced appraisers quietly step away.

What was meant to reduce pressure has become a system of control. Communication between lenders and appraisers is filtered. Pricing is dictated by algorithms. Scope interpretations are issued by third parties removed from the field. Judgment is slowly replaced by checklist compliance.

Healthcare has already traveled this road.

A 2025 Annals of Internal Medicine study showed nearly five percent of U.S. physicians left clinical practice in a single year, driven largely by burnout and administrative burden. The American Medical Association reports that physicians now spend nearly two hours on documentation for every hour of patient care.

Appraisers now operate inside the same imbalance. More time formatting reports than analyzing markets. More time satisfying review protocols than developing defensible opinions. Judgment yields to process.

This is not a workforce inconvenience. It is a structural market risk.

The fix is not complicated, but it does require courage.

First, appraisal fee transparency must be mandatory. If a borrower pays $650 and the appraiser receives $325, both parties deserve to know. Transparency restores accountability and allows market forces to function.

To read more, Click Here

My comments: Worth reading, especially how to fix it. We all know what is happening to residential lender appraisers.

For doctors, corporate medicine has taken over. For example, primary care physicians are allowed only 15 minute visits with patients. Large insurance companies make it very difficult for patients to get the care they need by denying what the patient needs. Doctors don’t like it, plus the excessive paperwork.

I play pickleball with a retired doctor. He had to sell his medical practice as he was underbid on fees by large health insurance companies.

Read more!! →

Appraising Solar Panels

Newz: Solar Panels, Concessions, AI and Appraisals

April 3, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Navigating Red Flags: a Contentious Divorce Case
  • What Is the Appraisal Value of Solar Panels? FAQs for Residential Appraisers
  • Tiny New York Home With No Bedrooms Hits the Market for a Bargain Price
  • Concessions Are Not the Price: How to Measure What the Market Is Actually Doing
  • MY AD: How to reduce stress to be more productive in business and a happier life for appraisers
  • My First 50 Years by Steve Papin
  • AI Usage in Appraisals: Trust but Verify by Jo Traut
  • MBA STATS: Mortgage applications decreased 10.4 percent from one week earlier


————————————————————————-

——————————————

What Is the Appraisal Value of Solar Panels? FAQs for Residential Appraisers

Excerpts:

How Common Are Solar Panels in Residential Appraisals?

Solar panels are increasingly common. Declining system costs, government tax incentives, and utility rebates have made solar PV ownership more accessible than ever. If you haven’t encountered an owned solar system on a subject property yet, there’s a good chance you will soon—particularly as more states push toward renewable energy goals.

The practical takeaway: developing a working knowledge of solar valuation now puts you ahead of the curve.

Topics:

Owned vs Leased Solar Panels—and Why It Matters for Appraisers

How Do You Determine the Appraisal Value of Solar Panels?

  • Sales Comparison Approach. This is the preferred method under Fannie Mae and FHA guidelines.
  • Cost Approach Solar PV systems are typically priced on a cost-per-watt or cost-per-kilowatt basis.
  • Income Approach This method estimates value based on the energy savings the system produces.

What Do You Do When There Are No Comparable Sales with Solar Panels? This is the question appraisers ask most often, and it’s a real challenge in many markets.

——————————————————-

What Are the Key Components of a Solar PV System that Appraisers Should Be Able to Identify?

How Can Appraisers Build Competency in Solar Valuation?

Solar PV systems are one piece of a broader green home appraisal niche that’s growing fast.

To read more, Click Here

My comments: Very comprehensive analysis of the important factors. I have never appraised a home (or apartments and commercial properties) with Solar. I live in a “Mediterranean” climate in the San Francisco Bay area. No big changes in weather over the year. No snow, no high heat etc. But I have heard appraisers discussing the topics above. If I appraised Solar in a home I would use this article.

Read more!! →

How to Appraise Basements

Newz: Appraising Basements, AMCs,

Who is doing UAD 3.6 appraisals?

February 20, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Limiting Liability to Third Parties
  • Basement Appraisals: Understanding Contributory Value (Updated for UAD 3.6)
  • Fascinating ‘Basement Home’ That Rises Just Inches Above the Ground Hits the Market for Less Than $160K
  • The AMCs: Coming Soon to a Lawsuit Near You
  • MY AD: The Cost Approach for Appraisers is not popular, by Tim Andersen, MAI
  • 26% of Appraisers Feel Ready: What UAD 3.6 Demand
  • Mortgage applications increased 2.8 percent from one week earlier
  • Have you received a UAD 3.6 order yet? Survey.
  • MBA: Mortgage applications increased 2.8 percent from one week earlier

Basement Issues and Values

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


Basement Appraisals: Understanding Contributory Value (Updated for UAD 3.6)

Excerpts: While homeowners may ask, “Does a finished basement add value to my appraisal?” you know the answer is a bit more complicated. A basement may impact a residential property’s value, and as an appraiser, you’ll need to evaluate its significance.

While determining the contributory value of basements isn’t overly complex, it does pose challenges. To help you out, we’ll outline essential steps and provide tips for evaluating a basement’s contributory value.

Summary

Determining how a basement contributes to a residential property’s value requires an appraiser to identify the basement type, its level of finishing, and any common concerns, like signs of mold or structural issues. Following best practices is key. This includes separating the basement from the above-grade finished area, understanding the intended use of the space, and completing comprehensive market research. By doing so, you can evaluate the basement’s contributory value more accurately

Topics include:

Types of basements (partial list)

Cellars

Partial Basements

Walk-Up Basements

How Is the Basement Finished? Determining Levels

Know the Intended Use and Client Requirements

To read more, Click Here

My comments: The best analysis and advice on basements I have seen. Watch the 7 minute video on Understanding Q/C ratings (UAD 3.6) Where I work the ground does not freeze. In my Island city there is no cemetery as the ground water from San Francico Bay is very high. Basements need pumps to remove salt water. Basement walls are not used to support the home. Sometimes there are above ground basements, basements dug out of the ground, and many other types of basements. In steep hillside areas what is a “basement” can be controversial.

In Alameda, my city, native American burials, primarily from the Ohlone people, are heavily concentrated in former shellmounds (ancient cemeteries) throughout Alameda. Almost were removed many years ago, similar to other Bay area cities close to the Bay.

Read more!! →

Appraising with Limited Comps

Newz: Limited Comps, Freddie Mac: Property Data Collection, Avoiding ourt

January 23, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Avoiding Court
  • Arriving at a Credible Appraisal When Comparable Sales Are Limited By Kevin Hecht
  • MAPPED: The Most Expensive Home Sales of 2025—From Palantir CEO’s Record-Breaking Ranch to Florida’s Priciest Mansion
  • MY AD: The AMC Conundrum in the Appraisal Business by Dave Towne
  • From Data to Value: How Mass Appraisal Delivers Fair Market Assessments
  • Freddie Mac. Insight Articles: Property Data Collection: An Overview
  • Housing Market Predictions for 2026
  • MBA: Mortgage applications increased 14.1 percent from one week earlier

———————————————————————–

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


Arriving at a Credible Appraisal When Comparable Sales Are Limited
By Kevin Hecht

Excerpts: Limited sales activity is common in rural markets, custom-home neighborhoods, and low-turnover areas. When comps are few, the appraiser’s task is not to find perfect matches, but to show that the selected sales are the best available indicators of value and that all departures from ideal data are well supported.

In this article, we’ll answer questions like: How far back do appraisers look for comps? How far out geographically? What other tips and tricks do appraisers use to arrive at a credible appraisal, even when comps are limited? Additionally, we’ll share some insights from appraisers who answered our survey question, “What do you do when appraisal comps are few?”

When recent, proximate, and similar sales are unavailable, appraisers typically rely on some combination of the “Three D’s” to broaden their search for comparable property sales:

Dated – Search for older sales within the subject neighborhood.Distant – Search for similar sales farther away in competing neighborhoods.

Dissimilar – Search for dissimilar sales within the subject neighborhood by widening the parameters for improvements (GLA, age, features, etc.).

How Far Back Do Appraisers Look for Comps?

Time adjustments draw scrutiny. Most agency assignments expect appraisers to use the most recent closed sales available, typically within the prior 12 months when possible.1 When older sales are used, market conditions adjustments often become central to the analysis.

Time adjustments should be supported with clear data, applied consistently, and reconciled logically. Underwriters pay close attention to whether these adjustments reflect documented market behavior rather than assumptions, particularly in shifting markets.

We surveyed our appraisal community to find out, “What do you do when appraisal comps are few?” The following comments show how individual appraisers often put their own spin on the “Three D’s” when expanding the search for comparable sales:

“Time and distance. My preference is to go back farther in time within the same neighborhood and/or market area and make market condition adjustments. If that still doesn’t provide enough comps, I expand the market area, looking for more recent sales with similar characteristics to the subject property.”

“First consider a broader time frame. Market conditions adjustments are very supportable.”

“Expand search to other competitive neighborhoods. Next, go back in time.”

To read more, Click Here

My comments: I usually go back in time sometimes several years or longer if needed. Of course, I don’t do GSE appraisals with their restrictions…


Read more!! →

Fannie: Inspection and Reporting Tips UAD 3.6

Newz: Fannie: Inspection and Reporting Tips UAD 3.6, Appraising Haunted Houses

October 31, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Legal Request for Old Appraisal
  • Inspection and Reporting Tips for Appraiser Uniform Appraisal Dataset (UAD) Specification Issued by Fannie Mae and Freddie Mac
  • Penthouse One – 3 Story in Florida listed for $47,500,000
  • “No Name” Licenses, No Accountability: From Highways to Housing
  • Appraising Haunted Houses
  • Foolish Mortals or Bargain Buyers: 1 in 2 Americans Would Buy a ‘Haunted’ House for the Right Price
  • Mortgage applications increased 7.1 percent from one week earlier

—————————————————————————————-

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

—————————————————————————–


———————————————————-

Uniform Appraisal Dataset (UAD) Specification Issued by Fannie Mae and Freddie Mac

Document Version 1.0

October 21, 2025

Excerpts: Navigating changes to the appraisal process can be complex – make the transition to the Uniform Appraisal Dataset (UAD) 3.6 easier with the new Inspection and Reporting Tips for Appraisers guide. This resource clarifies key differences between the new Uniform Residential Appraisal Report (URAR) and legacy UAD 2.6 forms, providing the information you need when researching or physically inspecting a property.

The purpose of this document is to assist the appraiser by highlighting the notable differences between UAD 3.6 and UAD 2.6, and direct the appraiser to appropriate section(s) in the Uniform Residential Appraisal Report (URAR) Reference Guide on the Fannie Mae and Freddie Mac UAD web pages.

The document offers tips for different sections within the URAR that may be helpful to an individual who is completing various aspects of an appraisal assignment.

• Inspection Tips: When physically inspecting the property, or

• Reporting Tips: When researching and completing the URAR, including new information that may require research from a website, the homeowner, or other source.

Items to Note:

• When there are no material differences between UAD 3.6 and UAD 2.6 with respect to

information collected, those URAR sections are omitted from this document. For example, the

information collected for “Assignment Information” is not included below because it’s very similar between UAD 3.6 and UAD 2.6.

• Review the URAR Reference Guide chapters 22 through 24 to understand the dynamic nature of the grids (Sales Comparison, Rental Comparison, GRM Comparison).

To access the Inspection and Reporting Tips for Appraisers resource, Click Here.

My comments: Worth reading. The only document I have read that compares UAD 2.6 (current form reports) and UAD 3.6 in specific fields. Uses tables that make it easier to understand. Refers to F-1, the document that contains information on fields. Hopefully, when you are doing UAD 3.6 Reports, your software will pull in the relevant sections from F-1.

I have written 6 articles on UAD 3.6 in my paid monthly newsletter, including a list of what has changed on each page of the sample SFR1 (Single Family) report. The November newsletter includes an update on software vendors and where to get demos. None have completed their UAD 3.6 software, including verification by GSEs.

Read more!! →

Condo Prices, up/down/?? for Appraisals

Newz: NAR Calls Out Unregulated Middlemen (AMCs), Modular Construction?

October 10, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Dealing with Unhappy Buyers as an Appraiser
  • Condo prices are obviously dropping, By Ryan Lundquist
  • Foreclosure Fixer-Uppers Ready for Their Next Chapter: 5 Abandoned Homes Offering a Bargain Deal to Buyers
  • The Modular Construction Revolution That Hasn’t Happened (Yet)

By Ivan Rupnik

  • NAR Calls Out Unregulated Middlemen: A Wake-Up Call for FHFA
  • When Appraisers Rally: Korea Sends the U.S. a Wake-Up Call
  • MBA Mortgage applications decreased 4.7 percent from one week earlier,

—