
Newz: Handling Low Fees, Fee Questions, Fees: AMC Class Action Lawsuit
August 13, 2026
Article List – in order. Scroll down the page to the topics.
-
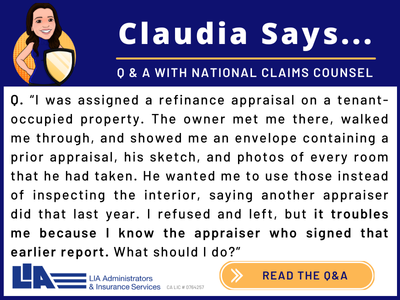
- LIA AD: When a property owner wants to do the appraisers job
- UAD 3.6 Survival Guide: How to Set Your Fee and Push Back on Low Offers By Chase Pursley
- This Off-Grid ‘Treehouse’ Is Perched 60 Feet in the Air—and Built From Shipping Containers Listed for $1.2 million in Epworth Georgia
- The Fee Question You Should Stop Asking Other Appraisers, By Dustin Harris
- MY AD: 2025 E&O Update – Claims, Payment Options, Lawsuits, Etc.
- Class Valuation Faces Class-Action Suit Over Appraiser PaymentsBy Frank Andorka, Managing Editor, WorkingRE
- AMCs – Locked Behind a Digital Iron Curtain, By Desiree Mehbod
- MY UAD 3.6 Update: Fees vary widely, software vendors working on finishing software details and inspection apps. Excellent Facebook page on UAD 3.6, mostly software issues.
- MBA STATS: Mortgage applications decreased 1.2 percent from one week earlier
Thanks to our Sponsor!!!
–———————————————
UAD 3.6 Survival Guide: How to Set Your Fee and Push Back on Low
By Chase Pursley
Excerpts: Stand Up for Your Fee on UAD 3.6 Orders
If your UAD 3.6 reports are taking longer at the same fee, you don’t have to absorb that. Compare the hours on similar assignments, then quote a fee that covers the work.
This post has no going rates and no fee surveys, and nobody here can tell you what a client will pay. Use your own records to explain what the assignment requires and what you charge.
Turn Logged Hours Into a Cost Per Report
Multiply your report hours by what you need to earn per hour, then add the costs tied to that report.
Set an hourly figure that covers your pay, taxes, and annual overhead. Then add only assignment expenses it doesn’t already cover, such as travel or a separate data purchase.
Here’s an illustration using $100 an hour and $50 in assignment expenses. These numbers are made up, and none of them is a suggested rate or fee. Substitute your own.
MORE TOPICS
-
-
- Confirm the Scope and Fee Before You Accept an Order
- Tell the AMC or lender what the report requires, then state your fee. A client can’t do much with “my costs went up.”
- “This assignment is a UAD 3.6 report on a two-unit, and here is my fee for that scope” is something they can answer.
-
How to Answer a Low Fee
When an Order Offers Less Than Your Fee
AND MORE EXELLENT TOPICS WITH HOW TO RESPOND
To read more, Click Here
My comments: Definitely the best article I have read on AMC fees. Read the article and find out how to handle the Fee Issue.
—————————————————–
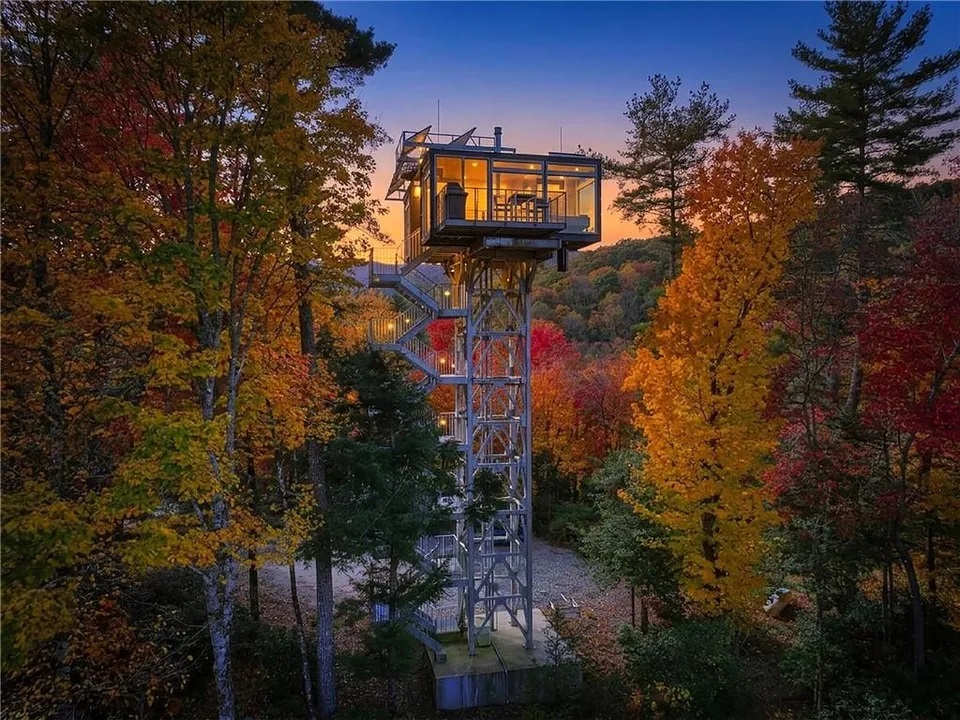
This Off-Grid ‘Treehouse’ Is Perched 60 Feet in the Air—and Built From Shipping Containers Listed for $1.2 million in Epworth Georgia
Excerpts: 1 bedroom, 1 bath, 14.31 acres, built in 2023
The structure itself is very unique. It’s a steel watchtower built to commercial grade but for residential purposes, purely for leisurely enjoyment, for getaways, for the adventurer at heart,” says listing agent Logan Fitts with Mountain Sotheby’s International Realty.
The 60-foot-high tower sits on 14.31 acres of land adjacent to the Chattahoochee National Forest with about 3,000 feet of river frontage. Two shipping containers are perched atop the tower, creating the living space.
“The main structure is the bedroom efficiency with a bed, sitting area, stove, kitchenette. There’s a landing between and then across is the bathroom area with a full shower, toilet, and double vanity,” he explains. “Then there’s a spiral staircase to the rooftop fire pit and lounge area.”
And while there is a lift for things like suitcases and packages, people need to walk up 82 steel-grated stairs, which Fitts admits can be a bit daunting.
“I was actually nervous going up the tower for the first time because it’s high and it is an experience. But once I did it, I said, ‘This is what real mountain experiences are like. This is something that people remember for the rest of their lives.'”
Once up there, the view is everything.
To read the listing with an aerial view and 68 photos, Click Here
My comments: No going up and down the stairs for me! Good exercise though…
—————————————————————–
The Fee Question You Should Stop Asking Other Appraisers
By Dustin Harris
Go into any appraiser group on Facebook right now and scroll for about ninety seconds. You will find some version of this question:
“Are you raising your fees for 3.6?”
It is a fair thing to wonder. The new report takes longer, and every appraiser in the country is doing the same math in their head. The question feels natural. It feels like colleagues comparing notes.
It is the wrong question. And depending on where you ask it, it may be an illegal one.
Here is the part that should get your attention. You do not have to reach an agreement. A discussion about pricing among competitors can itself be treated as an invitation to fix prices. It is a problem even if nobody agrees to anything, even if the number discussed is perfectly reasonable, and even if not one person in the thread ever changes a fee. Violations can carry both criminal and civil exposure, and a private plaintiff who wins one of these can recover three times their damages plus attorney’s fees.
Now let me get to why it is the wrong question even setting the law entirely aside.
When you ask a room full of appraisers whether they are raising fees, you are outsourcing the most important number in your business to a poll of people whose businesses you know nothing about. You do not know their overhead. You do not know their market, their turn times, their software, whether they have a trainee, whether they own their office or rent it, or how fast they personally work.
To read more, Click Here
My comments: When I started my appraisal business in 1986 there was no Internet, but I went to appraisal dinner meetings twice a month. I was warned that discussing fees during the meetings was illegal.
Another appraisal problem was classifying appraisal trainees as independent contractors. Mine were always employees. In the mid-1980s several large appraisal companies locallu were audited by the State labor regulators. Their trainees could not be employees legally. They had big fines.
———————————————————————-
Are you getting too many ad-only emails?
3 ways to get only the FREE email newsletters and NOT the ad-only emails.
1. Twitter: https://twitter.com/appraisaltoday Posted by noon Friday
2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page. NOTE: the popular ads with liability tips are below the first topic on my blog posts.
3. Link to the 10 most recent newsletters from newsletterS posted to my blog www.appraisaltoday.com. Scroll down past the big yellow signup block. The newsletters have abbreviated titles, taken from their blog posts.
To read more about the 3 ways, plus information on why I take ads, etc.
———————————————-
2026 E and O Update – Claims, Payment Options, Lawsuits, Etc
By Claudia Gaglione, Esq. & Magda Pretorius, Risk and Claims Analyst with LIA Administrators & Insurance Services (LIA)
In the October issue of Appraisal Today
Excerpts:
Artificial Intelligence
A hot topic in the appraisal community is how to integrate the use of AI into
the profession / their day to day business operation.
When working with AI to produce a report, appraisers have to be mindful of
their obligation under USPAP to produce a report that is credible and in no way misleading. They must always review, edit, and take full responsibility for the content of the reports they produce. They cannot simply rely upon AI generated material without ensuring its accuracy. That means double checking and verifying everything they possibly can.
We counsel insureds to take classes to listen to as many viewpoints as
possible. In the meantime, make sure that if your report contains any AI generated content that the workfile shows how and to what extent you took steps to verify that content; public records, calls to real estate agents, whatever it takes.
Appraisers with supervisory authority must also implement reasonable
policies, training, and oversight to ensure that any use of generative AI by trainees does not compromise client confidentiality or replace appropriate analysis or quality control.
There are no AI related claims in our program at this time.
UAD 3.6
The most common concern expressed by our insureds are where/how do
they include the additional language they have traditionally added in the
supplemental addendum of the appraisal report.
It is important that appraisers continue to add this language in their reports,
we suggest that they add the language in the report where/when
relevant.
We don’t have more knowledge than they have about the software and we
are getting to know the software/forms at the same time they are.
To read more about E&O, with many topics in this issue, plus 2+ years of previous issues, subscribe to the paid Appraisal Today at ww.appraisaltoday.com/order .
Not sure if you want to subscribe?
Sign up for monthly auto renewal for $8.25!
Cancel at any time for any reason! You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
What’s the difference between the Appraisal Today free Weekly email newsletter and the paid Monthly newsletter? Click here for more info.
———————————————-
If you are a paid subscriber and did not receive the November issue emailed on November 2, 2026, please email info@appraisaltoday.com, and we will send it to you. You can also hit the reply button. Be sure to include a comment requesting it.
————————————————————–
Please hit the reply button if you have any comments or info on any topics. I’m always looking for something new ;>
———————————————-
Class Valuation Faces Class-Action Suit Over Appraiser Payments
By Frank Andorka, Managing Editor, WorkingRE
Excerpts: Class Valuation, one of the largest appraisal management companies (AMCs) in the United States, is the latest AMC to be sued over the issue of appraisal fees and fee transparency.
Clayton Bernholtz, a Florida resident, filed a class-action lawsuit June 11, 2026, in Broward County Circuit Court against Class Valuation and CrossCountry Mortgage, alleging the companies overcharge consumers for home appraisals through undisclosed fees, in violation of the Florida Deceptive and Unfair Trade Practices Act (FDUTPA).
Bernholtz also accuses Class Valuation of unjust enrichment, alleging the company pockets the difference between what it charges consumers and what it actually pays appraisers. He is asking the court to certify the case as a class action on behalf of himself and all others similarly situated, which would allow other affected borrowers to join the suit.
Originally filed in Broward County, Florida, the case was later removed to the U.S. District Court for the Southern District of Florida (Case No. 0:26-cv-61978).
Many appraisers had hoped this issue would be resolved without litigation by the Consumer Financial Protection Bureau (CFPB), which had been expected to issue guidance before the new administration took over. In its current weakened state, it is unlikely such guidance will be coming, which leaves plaintiffs with no alternative (Editor’s Note: until the recent national elections see below.) The focus should be on consumer appraisal fees, not appraisal fees.
Essentially, Bernholtz’s allegations echo the core arguments of the other class-action lawsuits facing AMCs and lenders in this space — CrossCountry Mortgage breached its contract with him, he claims, while Class Valuation, as an appraisal management company, engaged in “unlawful, unfair and deceptive practices relating to the ‘appraisal fees’ they charge mortgage borrowers.”
To read more, Click Here
My comments: With the recent national elections, the CFPB may become more prominent to handle excess fees paid by borrowers. Not many people care about appraisal fees, but borrowers care – a much larger group than appraisers.
——————————————————————–
AMCs – Locked Behind a Digital Iron Curtain
By Desiree Mehbod
Excerpts: Imagine waking up to find your livelihood locked behind a digital iron curtain. That is exactly what happened to an entire panel of appraisers who logged in last week only to find themselves trapped. There were no warnings and no choices.
The Appraisal Management Company held their active assignments and their income hostage behind a mandatory checkbox. Agree to the new terms, or you do not get to work. The kicker is that this company proudly calls these people their appraiser partners, which makes you wonder what they do to their enemies.
The nightmare deepens once you look at what those terms actually demand. The AMC gave themselves full permission to harvest the intellectual property inside every completed appraisal report. They are taking the localized knowledge, the expertise, and the hard work of human professionals and feeding it directly into the maw of their artificial intelligence models. It is a corporate horror story where the machine strips the minds of the appraisers it is actively trying to replace, forcing them to build their own digital executioner for free.
To read more, Click Here
My comments: I recently attended a webinar demo of one of the new UAD 3.6 software vendors. They said they did not take appraisers data.
===================================
MY UAD 3.6 UPDATE
Appraisers are complaining about fees, which seem to vary widely. UAD 2.6 and UAD 3.6. Before AMCs took over around 1980, fees did not vary much over time or among lenders or mortgage brokers. Today’s AMC fee issues is the most significant fee problem that has ever occurred that I know of.
Continuing updates for UAD 3.6 software vendors. A Big Problem. Also, some vendors do not have a functioning, usable inspection app for appraisers who want to significantly decrease the time writing appraisals.
Where to see what appraisers are saying about UAD 3.6 software vendors.
No whining or off topics allowed. My favorite place to keep track of the software mess. Lots of Total posts is:
Most Excellent Facebook Page:
Appraisers Perspective of UAD 3.6
——————————————————————-
HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, Click Here.
Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.
My comments: Rates are going up and down. UAD 3.6 few orders. Many appraisers are not busy. Some are busy, usually with non-lender appraisals.
Mortgage applications decreased 1.2 percent from one week earlier
WASHINGTON, D.C. (November 4, 2026) — Mortgage applications decreased 1.2 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 30, 2026.
The Market Composite Index, a measure of mortgage loan application volume, decreased 1.2 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 2 percent compared with the previous week. The Refinance Index increased 0.1 percent from the previous week and was 60 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 2 percent from one week earlier. The unadjusted Purchase Index decreased 4 percent compared with the previous week and was 19 percent lower than the same week one year ago.
“Mortgage rates drifted down to their lowest level since September 2026 last week in the wake of the Federal Reserve’s decision to hold on additional rate hikes at its October meeting,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “While the 30-year rate declined to 7.3 percent, activity is still quite slow, with purchase application volume down for the week and refinance volume effectively flat at a very low level. As we have highlighted in recent weeks, more borrowers are choosing ARMs in this environment to lower their initial payments, with the ARM share at its highest level since September 2025.”
The refinance share of mortgage activity increased to 39.8 percent of total applications from 38.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.4 percent of total applications.
The FHA share of total applications decreased to 16.0 percent from 16.6 percent the week prior. The VA share of total applications increased to 11.2 percent from 11.0 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.5 percent the week prior.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.30 percent from 7.37 percent, with points decreasing to 0.75 from 0.76 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.
The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.20 percent from 7.28 percent, with points decreasing to 0.48 from 0.64 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.
The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.02 percent from 7.12 percent, with points remaining unchanged at 1.07 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.
The average contract interest rate for 15-year fixed-rate mortgages increased to 6.76 percent from 6.70 percent, with points increasing to 0.98 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 5/1 ARMs decreased to 6.29 percent from 6.41 percent, with points decreasing to 1.00 from 1.20 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.
The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.
——————————————-
 Ann O’Rourke, MAI, SRA, MBA
Appraiser and Publisher Appraisal Today
1826 Clement Ave. Suite 203 Alameda, CA 94501
Phone: 510-865-8041
Email: ann@appraisaltoday.com
Online: www.appraisaltoday.com
We want to know what you think!! Please leave a comment.