Appraisal Fees for Appraisers 11-13-26

Newz: Handling Low Fees, Fee Questions, Fees: AMC Class Action Lawsuit

August 13, 2026

Article List – in order. Scroll down the page to the topics.

    • LIA AD: When a property owner wants to do the appraisers job
    • UAD 3.6 Survival Guide: How to Set Your Fee and Push Back on Low Offers By Chase Pursley
    • This Off-Grid ‘Treehouse’ Is Perched 60 Feet in the Air—and Built From Shipping Containers Listed for $1.2 million in Epworth Georgia
    • The Fee Question You Should Stop Asking Other Appraisers, By Dustin Harris
    • MY AD: 2025 E&O Update – Claims, Payment Options, Lawsuits, Etc.
    • Class Valuation Faces Class-Action Suit Over Appraiser PaymentsBy Frank Andorka, Managing Editor, WorkingRE
    • AMCs – Locked Behind a Digital Iron Curtain, By Desiree Mehbod
    • MY UAD 3.6 Update: Fees vary widely, software vendors working on finishing software details and inspection apps. Excellent Facebook page on UAD 3.6, mostly software issues.
    • MBA STATS: Mortgage applications decreased 1.2 percent from one week earlier
Thanks to our Sponsor!!!

–———————————————

UAD 3.6 Survival Guide: How to Set Your Fee and Push Back on Low

By Chase Pursley

Excerpts: Stand Up for Your Fee on UAD 3.6 Orders

If your UAD 3.6 reports are taking longer at the same fee, you don’t have to absorb that. Compare the hours on similar assignments, then quote a fee that covers the work.

This post has no going rates and no fee surveys, and nobody here can tell you what a client will pay. Use your own records to explain what the assignment requires and what you charge.

Turn Logged Hours Into a Cost Per Report

Multiply your report hours by what you need to earn per hour, then add the costs tied to that report.

Set an hourly figure that covers your pay, taxes, and annual overhead. Then add only assignment expenses it doesn’t already cover, such as travel or a separate data purchase.

Here’s an illustration using $100 an hour and $50 in assignment expenses. These numbers are made up, and none of them is a suggested rate or fee. Substitute your own.

MORE TOPICS

      • Confirm the Scope and Fee Before You Accept an Order
      • Tell the AMC or lender what the report requires, then state your fee. A client can’t do much with “my costs went up.”
      • “This assignment is a UAD 3.6 report on a two-unit, and here is my fee for that scope” is something they can answer.

How to Answer a Low Fee

When an Order Offers Less Than Your Fee

AND MORE EXELLENT TOPICS WITH HOW TO RESPOND

To read more, Click Here

My comments: Definitely the best article I have read on AMC fees. Read the article and find out how to handle the Fee Issue.

—————————————————–
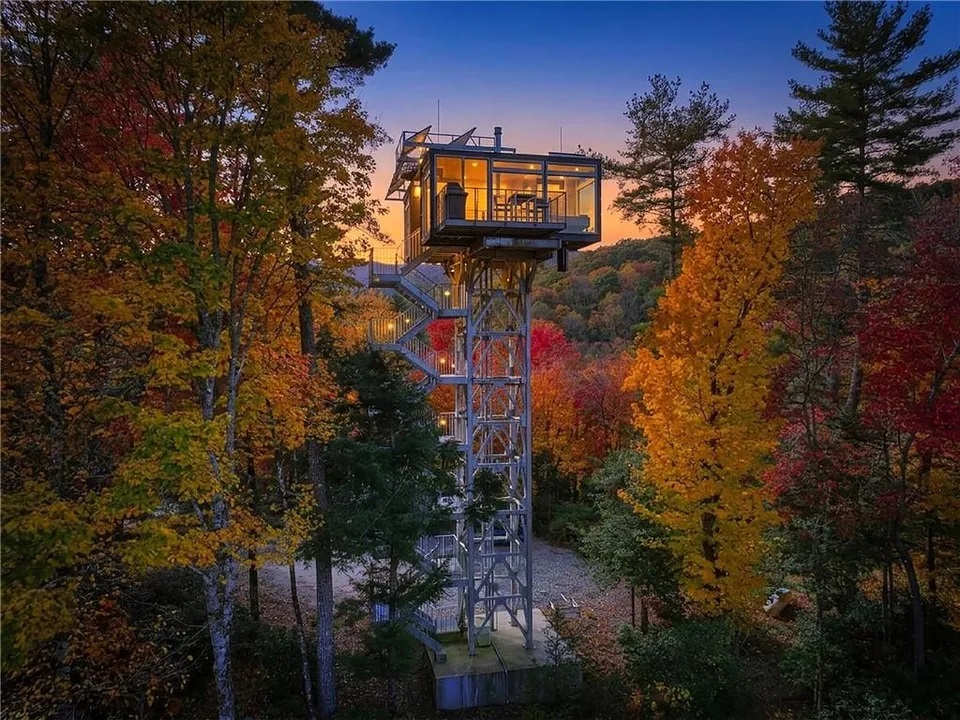
This Off-Grid ‘Treehouse’ Is Perched 60 Feet in the Air—and Built From Shipping Containers Listed for $1.2 million in Epworth Georgia

Excerpts: 1 bedroom, 1 bath, 14.31 acres, built in 2023

The structure itself is very unique. It’s a steel watchtower built to commercial grade but for residential purposes, purely for leisurely enjoyment, for getaways, for the adventurer at heart,” says listing agent Logan Fitts with Mountain Sotheby’s International Realty.

The 60-foot-high tower sits on 14.31 acres of land adjacent to the Chattahoochee National Forest with about 3,000 feet of river frontage. Two shipping containers are perched atop the tower, creating the living space.

“The main structure is the bedroom efficiency with a bed, sitting area, stove, kitchenette. There’s a landing between and then across is the bathroom area with a full shower, toilet, and double vanity,” he explains. “Then there’s a spiral staircase to the rooftop fire pit and lounge area.”

And while there is a lift for things like suitcases and packages, people need to walk up 82 steel-grated stairs, which Fitts admits can be a bit daunting.

“I was actually nervous going up the tower for the first time because it’s high and it is an experience. But once I did it, I said, ‘This is what real mountain experiences are like. This is something that people remember for the rest of their lives.'”

Once up there, the view is everything.

To read the listing with an aerial view and 68 photos, Click Here

My comments: No going up and down the stairs for me! Good exercise though…

—————————————————————–

The Fee Question You Should Stop Asking Other Appraisers

By Dustin Harris

Go into any appraiser group on Facebook right now and scroll for about ninety seconds. You will find some version of this question:

“Are you raising your fees for 3.6?”

It is a fair thing to wonder. The new report takes longer, and every appraiser in the country is doing the same math in their head. The question feels natural. It feels like colleagues comparing notes.

It is the wrong question. And depending on where you ask it, it may be an illegal one.

Here is the part that should get your attention. You do not have to reach an agreement. A discussion about pricing among competitors can itself be treated as an invitation to fix prices. It is a problem even if nobody agrees to anything, even if the number discussed is perfectly reasonable, and even if not one person in the thread ever changes a fee. Violations can carry both criminal and civil exposure, and a private plaintiff who wins one of these can recover three times their damages plus attorney’s fees.

Now let me get to why it is the wrong question even setting the law entirely aside.

When you ask a room full of appraisers whether they are raising fees, you are outsourcing the most important number in your business to a poll of people whose businesses you know nothing about. You do not know their overhead. You do not know their market, their turn times, their software, whether they have a trainee, whether they own their office or rent it, or how fast they personally work.

To read more, Click Here

My comments: When I started my appraisal business in 1986 there was no Internet, but I went to appraisal dinner meetings twice a month. I was warned that discussing fees during the meetings was illegal.

Another appraisal problem was classifying appraisal trainees as independent contractors. Mine were always employees. In the mid-1980s several large appraisal companies locallu were audited by the State labor regulators. Their trainees could not be employees legally. They had big fines.

———————————————————————-

Are you getting too many ad-only emails?

3 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday Posted by noon Friday

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page. NOTE: the popular ads with liability tips are below the first topic on my blog posts.

3. Link to the 10 most recent newsletters from newsletterS posted to my blog www.appraisaltoday.com. Scroll down past the big yellow signup block. The newsletters have abbreviated titles, taken from their blog posts.

To read more about the 3 ways, plus information on why I take ads, etc.

Click here

———————————————-

2026 E and O Update – Claims, Payment Options, Lawsuits, Etc

By Claudia Gaglione, Esq. & Magda Pretorius, Risk and Claims Analyst with LIA Administrators & Insurance Services (LIA)

In the October issue of Appraisal Today

Excerpts:

Artificial Intelligence

A hot topic in the appraisal community is how to integrate the use of AI into

the profession / their day to day business operation.

When working with AI to produce a report, appraisers have to be mindful of

their obligation under USPAP to produce a report that is credible and in no way misleading. They must always review, edit, and take full responsibility for the content of the reports they produce. They cannot simply rely upon AI generated material without ensuring its accuracy. That means double checking and verifying everything they possibly can.

We counsel insureds to take classes to listen to as many viewpoints as

possible. In the meantime, make sure that if your report contains any AI generated content that the workfile shows how and to what extent you took steps to verify that content; public records, calls to real estate agents, whatever it takes.

Appraisers with supervisory authority must also implement reasonable

policies, training, and oversight to ensure that any use of generative AI by trainees does not compromise client confidentiality or replace appropriate analysis or quality control.

There are no AI related claims in our program at this time.

UAD 3.6

The most common concern expressed by our insureds are where/how do

they include the additional language they have traditionally added in the

supplemental addendum of the appraisal report.

It is important that appraisers continue to add this language in their reports,

we suggest that they add the language in the report where/when

relevant.

We don’t have more knowledge than they have about the software and we

are getting to know the software/forms at the same time they are.

To read more about E&O, with many topics in this issue, plus 2+ years of previous issues, subscribe to the paid Appraisal Today at ww.appraisaltoday.com/order .

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason! You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

What’s the difference between the Appraisal Today free Weekly email newsletter and the paid Monthly newsletter? Click here for more info.

———————————————-

If you are a paid subscriber and did not receive the November issue emailed on November 2, 2026, please email info@appraisaltoday.com, and we will send it to you. You can also hit the reply button. Be sure to include a comment requesting it.

————————————————————–

Please hit the reply button if you have any comments or info on any topics. I’m always looking for something new ;>

———————————————-

Class Valuation Faces Class-Action Suit Over Appraiser Payments

By Frank Andorka, Managing Editor, WorkingRE

Excerpts: Class Valuation, one of the largest appraisal management companies (AMCs) in the United States, is the latest AMC to be sued over the issue of appraisal fees and fee transparency.

Clayton Bernholtz, a Florida resident, filed a class-action lawsuit June 11, 2026, in Broward County Circuit Court against Class Valuation and CrossCountry Mortgage, alleging the companies overcharge consumers for home appraisals through undisclosed fees, in violation of the Florida Deceptive and Unfair Trade Practices Act (FDUTPA).

Bernholtz also accuses Class Valuation of unjust enrichment, alleging the company pockets the difference between what it charges consumers and what it actually pays appraisers. He is asking the court to certify the case as a class action on behalf of himself and all others similarly situated, which would allow other affected borrowers to join the suit.

Originally filed in Broward County, Florida, the case was later removed to the U.S. District Court for the Southern District of Florida (Case No. 0:26-cv-61978).

Many appraisers had hoped this issue would be resolved without litigation by the Consumer Financial Protection Bureau (CFPB), which had been expected to issue guidance before the new administration took over. In its current weakened state, it is unlikely such guidance will be coming, which leaves plaintiffs with no alternative (Editor’s Note: until the recent national elections see below.) The focus should be on consumer appraisal fees, not appraisal fees.

Essentially, Bernholtz’s allegations echo the core arguments of the other class-action lawsuits facing AMCs and lenders in this space — CrossCountry Mortgage breached its contract with him, he claims, while Class Valuation, as an appraisal management company, engaged in “unlawful, unfair and deceptive practices relating to the ‘appraisal fees’ they charge mortgage borrowers.”

To read more, Click Here

My comments: With the recent national elections, the CFPB may become more prominent to handle excess fees paid by borrowers. Not many people care about appraisal fees, but borrowers care – a much larger group than appraisers.

——————————————————————–
AMCs – Locked Behind a Digital Iron Curtain

By Desiree Mehbod

Excerpts: Imagine waking up to find your livelihood locked behind a digital iron curtain. That is exactly what happened to an entire panel of appraisers who logged in last week only to find themselves trapped. There were no warnings and no choices.

The Appraisal Management Company held their active assignments and their income hostage behind a mandatory checkbox. Agree to the new terms, or you do not get to work. The kicker is that this company proudly calls these people their appraiser partners, which makes you wonder what they do to their enemies.

The nightmare deepens once you look at what those terms actually demand. The AMC gave themselves full permission to harvest the intellectual property inside every completed appraisal report. They are taking the localized knowledge, the expertise, and the hard work of human professionals and feeding it directly into the maw of their artificial intelligence models. It is a corporate horror story where the machine strips the minds of the appraisers it is actively trying to replace, forcing them to build their own digital executioner for free.

To read more, Click Here

My comments: I recently attended a webinar demo of one of the new UAD 3.6 software vendors. They said they did not take appraisers data.

===================================

MY UAD 3.6 UPDATE

Appraisers are complaining about fees, which seem to vary widely. UAD 2.6 and UAD 3.6. Before AMCs took over around 1980, fees did not vary much over time or among lenders or mortgage brokers. Today’s AMC fee issues is the most significant fee problem that has ever occurred that I know of.

Continuing updates for UAD 3.6 software vendors. A Big Problem. Also, some vendors do not have a functioning, usable inspection app for appraisers who want to significantly decrease the time writing appraisals.

Where to see what appraisers are saying about UAD 3.6 software vendors.

No whining or off topics allowed. My favorite place to keep track of the software mess. Lots of Total posts is:

Most Excellent Facebook Page:

Appraisers Perspective of UAD 3.6

——————————————————————-

HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, Click Here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down. UAD 3.6 few orders. Many appraisers are not busy. Some are busy, usually with non-lender appraisals.

Mortgage applications decreased 1.2 percent from one week earlier

WASHINGTON, D.C. (November 4, 2026) — Mortgage applications decreased 1.2 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 30, 2026.

The Market Composite Index, a measure of mortgage loan application volume, decreased 1.2 percent on a seasonally adjusted basis from one week earlier.  On an unadjusted basis, the Index decreased 2 percent compared with the previous week.  The Refinance Index increased 0.1 percent from the previous week and was 60 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 2 percent from one week earlier. The unadjusted Purchase Index decreased 4 percent compared with the previous week and was 19 percent lower than the same week one year ago.

“Mortgage rates drifted down to their lowest level since September 2026 last week in the wake of the Federal Reserve’s decision to hold on additional rate hikes at its October meeting,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “While the 30-year rate declined to 7.3 percent, activity is still quite slow, with purchase application volume down for the week and refinance volume effectively flat at a very low level. As we have highlighted in recent weeks, more borrowers are choosing ARMs in this environment to lower their initial payments, with the ARM share at its highest level since September 2025.”

The refinance share of mortgage activity increased to 39.8 percent of total applications from 38.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.4 percent of total applications.

The FHA share of total applications decreased to 16.0 percent from 16.6 percent the week prior. The VA share of total applications increased to 11.2 percent from 11.0 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.5 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.30 percent from 7.37 percent, with points decreasing to 0.75 from 0.76 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.20 percent from 7.28 percent, with points decreasing to 0.48 from 0.64 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.02 percent from 7.12 percent, with points remaining unchanged at 1.07 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 6.76 percent from 6.70 percent, with points increasing to 0.98 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.29 percent from 6.41 percent, with points decreasing to 1.00 from 1.20 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

——————————————-

Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
AMC Panel Requirements 10-30-26

Newz: UAD 3.6: Fees, Turn-Time, Software and more, AMC Panel Requirements

October 30, 2026

ARTICLE LIST – In order, scroll down the page to read

  • LIA AD: AMC Panel Requirements
  • UAD 3.6: Inside the Struggle Over Fees, Turn-Time and Software By Frank Andorka, Managing Editor WorkingRE
  • A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market
  • What is Highest and Best Use in Appraisal? (Updated for UAD 3.6) , By Kevin Hecht
  • MY AD: What Enough of UAD 3.6, I Have a Business to Run!, By Doug Smith, MBA, SRA
  • UAD 3.6: A New Era of Accountability in Appraisal Quality, By Gynell Vestal (Administrator) American Valuation Society
  • Flock Camera Blunders and the Privacy Risks of UAD 3.6, By Desiree Mehbod
  • MBA stats: Mortgage applications increased 3.4 percent from one week earlier


Thanks to our Sponsor!!

——————————-————————-

UAD 3.6: Inside the Struggle Over Fees, Turn-Time, Software and more

By Frank Andorka, Managing Editor, Working RE

Excerpts: Editor’s Note: Since this article was written, the GSEs created an exception to UAD 3.6 implementation for sellers who aren’t able to make the full transition to the new standard before Nov. 2. The exception runs through May 19, 2027. The GSEs will also allow resubmissions of UAD 2.6 appraisal reports through June 27, 2027. As of March 1, 2027, UAD 2.6 appraisals will no longer qualify for certain appraisal-related representations and warranties relief. For more, check out our full report at workingre.com:

GSEs Create Exception for UAD 3.6 Deadline: Runs through May 19, 2027.

To read: Click Here

Nov. 2 is usually just another day on the calendar — but not this year

Timeline and Rollout

The rollout of UAD 3.6 has been hampered considerably by two problems: slow software rollouts and lenders dragging their feet. When Working RE covered Valuation Expo in Las Vegas at the end of August, the problems clearly came into view.

While most of the leading software providers received initial approval from the GSEs in late 2025 and early 2026, word on the ground at Valuation Expo (Val Expo) was that there were still plenty of bugs to work out. AMC executives privately shared that they had staff simultaneously testing all the GSE-approved reporting software so they could troubleshoot and support appraisers when they inevitably ran into problems trying to turn in assignments. Some of those bugs were being run back to the software companies in real time, with the appraiser, AMC, lender and software provider working through the problem together.

The bigger problem in August was that lenders had barely begun ordering the 3.6 appraisals at all. Rocket Mortgage staff at Val Expo said they had ordered six UAD 3.6 appraisals. Rocket originates roughly six to seven percent of all residential mortgages in the United States. Several regional AMCs reported completing exactly two assignments apiece — and in each case, one of the two was a test run the AMC had ordered itself.

Scott Reuter, chief appraiser at Freddie Mac, summed up the bind on a panel at the show: “Appraisers cannot do a 3.6 assignment unless somebody orders a 3.6 assignment.”

More Than 900 Data Elements

There were approximately 190 data elements in UAD 2.6. There are now more than 900 in UAD 3.6. Reuter says it’s easy to be overwhelmed if appraisers just hear the number, but he assures the industry that appraisers were in the room when the form was developed.

“I want to make sure they don’t just hear ‘more than 900 elements’ and worry that they won’t be able to do it,” Reuter says. “They won’t have to fill out all those data points for every property. They are never going to touch the lion’s share of them, but we wanted to make sure we accounted for every potential contingency just in case.”

Lyle Radke, senior director of collateral policy at Fannie Mae, says Fannie and Freddie hold, between the two of them, $7 trillion in mortgage debt which, since it’s backed by the U.S. Treasury, is guaranteed by U.S. taxpayers. Therefore, it stands to reason collecting more data than before is important.

“From that perspective, the data is essential,” Radke says. “It’s how we manage risk. UAD 3.6 makes it easier for us to see and understand the data. If we didn’t have 3.6, we could still parse the data, but it would be much more challenging and time consuming.”

Other topics include turn times, liability and fees.

As the industry rushes toward the Nov. 2 deadline, appraisers’ stress levels will continue to rise. The only question is: What will things look like when the smoke clears? Only time will tell.

To read more, Click Here

My comments: Good discussion of the issues with quotes from many people, including GSEs. Not many changes since the August conference, except software vendors are still sending out updates. Fees still unclear.


Read more!! →

UAD 3.6 Fees for Appraisers 10-16-26

Newz: UAD 3.6 Fees, Fun Appraiser Game, Who Can Get Your Appraisal Data?

October 16, 2026

ARTICLE LIST – In order, Scroll down the page to read

  • LIA AD: Problem with An Affidavit
  • UAD 3.6 and the Appraisal Fee Chain: Who Actually Sets the Fee?, By Doug Smith, SRA
  • Lots Under Water
  • Certification 25: The 20-Year Fight Over Who Gets to Use Your Data, By Isaac Peck, WorkingRE, Publisher
  • Appraiser Game – Something FUN, By Dustin Harris
  • MY AD: 2026 E&O Update – Claims, Payment Options, Lawsuits, Etc
  • Inspectors Blocked the Door, Appraisers handed over the Keys By Desiree Mehbod
  • MBA STATS: Mortgage applications decreased 2.7 percent from one week earlier


Thanks to our Sponsor!!!

——————————————————-

UAD 3.6 and the Appraisal Fee Chain: Who Actually Sets the Fee?

By Doug Smith, SRA

“…the higgling and bargaining of the market…”

— Adam Smith, The Wealth of Nations, 1776

There has been considerable discussion about appraisal fees as UAD 3.6 is implemented. Much of the criticism over resistance to fee increases has been directed at Appraisal Management Companies.

But before deciding where responsibility lies, perhaps we need to follow what might be called the appraisal fee chain.

It begins with the borrower

A consumer seeking to purchase or refinance a residence provides information to a lender. The familiar conventional mortgage application is the Uniform Residential Loan Application (URLA), also known as Freddie Mac Form 65/Fannie Mae Form 1003.

For federal mortgage disclosure purposes, an application is considered received once the lender has six pieces of information: the consumer’s name, income, Social Security number, property address, estimated property value, and desired loan amount.

Once those items have been received, the lender generally must provide a Loan Estimate within three business days.

That Loan Estimate includes estimated loan and closing costs, including the anticipated cost of an appraisal when one is required.

This is where the appraisal fee chain gets interesting.

Federal disclosure rules limit how much certain estimated charges can increase between the Loan Estimate and closing. Depending on the circumstances, some required third-party service charges may be subject to a 10% cumulative tolerance, while others are subject to different rules. A valid changed circumstance may also permit a revised Loan Estimate.

So here is the first question:

Does the appraisal amount initially disclosed to the borrower influence the fee that can later be offered to the appraiser?

Once the borrower indicates an intent to proceed, the appraisal ordering process moves forward. Depending on the lender’s business model, the appraisal may be ordered directly from an appraiser or through an AMC.

Eventually, an assignment reaches an appraiser with a proposed fee.

But where in the appraisal fee chain was that number actually established?

Was it established by the lender when estimating the cost of the loan?

Was it established through an existing agreement or fee schedule between the lender and AMC?

Does the AMC determine the fee it offers the appraiser?

For lenders ordering directly, are they expecting UAD 3.6 assignments to be completed for the same fees previously paid for UAD 2.6 assignments?

And when an appraiser responds that the proposed fee is inadequate, how far back up the appraisal fee chain does that information travel?

These questions matter because UAD 3.6 changes the appraisal product and, for many appraisers, the process required to produce it. Appraisers are investing in training, software and equipment. Inspection procedures and data collection are changing. During the transition, the time required to complete an assignment may change as well.

Yet much of the current discussion seems to begin with the assumption that the appraisal fee should remain where it was.

Perhaps the question should not simply be, “Why won’t AMCs increase appraisal fees?”

The better question may be:

Where in the appraisal fee chain is the price of a UAD 3.6 appraisal actually being established—and is there still room for the market to establish a different price?

Nearly 250 years ago, Adam Smith described part of that price-setting process as the “higgling and bargaining of the market.”

Appraisers are participants in that market too.

A proposed fee is a proposal, not necessarily the market price.

Perhaps it is time for a little more higgling and bargaining.

My comments: I had never known about this before. Thanks to Doug Smith for the info!

Read more!! →

Basic Requirements For Appraisal Reports (Updated for UAD 3.6)

Newz: 3 Basic Requirements for UAD 3.6 Appraisal Reports, Good Facebook Page – UAD 3.6 Software

July 31, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Limiting Liability to Third Parties
  • The 3 Basic Requirements for Real Property Appraisal Reports (Updated for UAD 3.6) By Kevin Hecht
  • Bay Area’s wildest house lists at $899K and just hit the market for the first time
  • Am I Being Paranoid, or Is There Another Reason? By Richard Hagar, SRA – GSE data
  • MY AD: Residential appraisal forms from the 1960s to today
  • The Appraisal Fee Lawsuit AMCs Can’t Outrun
  • DATE CORRECTION ON CONFERENCES in last week’s email
  • Excellent Facebook Page for UAD 3.6 Software
  • MBA STATS: Mortgage applications decreased 6.4 percent from one week earlier


The 3 Basic Requirements for Real Property Appraisal Reports (Updated for UAD 3.6) By Kevin Hecht, SRA

Excerpts: As a real property appraiser, you rely on appraisal reports to communicate your opinion of value. One of the most important principles in USPAP is also one of the most misunderstood: forms are not reports.

Filling out a form properly and completely does not automatically mean your report is USPAP-compliant. The content of the appraisal report, not its form or format, determines compliance.

That distinction has never mattered more than it does right now.

The static forms appraisers have relied on for decades, including the 1004, 1073, 1025, and 2055, are being retired and replaced by a single, dynamic, data-driven reporting structure.

This shift does not change the three foundational requirements of USPAP Standards Rule 2-1. But it does change how you meet them. Understanding that distinction is critical to your compliance and your credibility in the new reporting environment.

TOPICS

What Are the Three Basic Requirements for an Appraisal Report?

Standards Rule 2-1(a): Clearly, Accurately, and Not Misleading

SR 2-1(a) builds on the ETHICS RULE requirement that your appraisal reports must not be misleading. You satisfy this requirement by making sure you “clearly and accurately set forth the appraisal.”

As the saying goes, you must tell the truth, the whole truth, and nothing but the truth.

Under the legacy form-based system, appraisers added context and explanation through a free-form General Addendum, which provided flexibility when a standard data field did not fully capture the nuances of a particular property or assignment.

Under UAD 3.6, that flexibility is now built directly into the report structure itself through section-specific commentary fields, which keeps all relevant analysis organized and immediately accessible to reviewers.

Standards Rule 2-1(b): Sufficient Information for Intended Users

What changes under UAD 3.6 is where and how you provide that sufficient information

Standards Rule 2-1(c): Disclosing Assumptions, Extraordinary Assumptions, Hypothetical Conditions, and Limiting Conditions

How UAD 3.6 Supports USPAP Compliance

Preparing for UAD 3.6: Practical Steps for Appraisers

To read more, Click Here

My comments: Comprehensive, well written and worth reading.

Read more!! →

UAD 3.6 Appraisal Fees

New URAR and UAD 3.6 Appraisal Fees, AMC Tech Fees

February 6, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Using trainees – the safe way
  • Will the New URAR and UAD 3.6 Impact Appraisal Fees?
  • It looks like an SF apartment complex. It’s actually a $32M estate.
  • From Dealerships to AMCs: Tech Fees as the New Normal by Desiree Mehbod
  • MY AD: New in the February 2026 issue of Appraisal Today. Book Review: Mein Comp: The Last Appraiser
  • “Because Houses Are Human” AI and Appraisers By David Hyman
  • Architecture Is About to Grow a Nervous System
  • Buildings that are alive
  • MBA: Mortgage applications decreased 8.5 percent from one week earlier

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


———————————————————-

Will the New URAR and UAD 3.6 Impact Appraisal Fees?

Excerpts: With the new URAR and UAD 3.6 rolling out this year, you may be wondering what effect this will have on your fees. While there’s still a lot of uncertainty and speculation around this question, we’re sharing the opinions of professional real estate appraisers who answered our survey, “How do you anticipate the new URAR/UAD 3.6 changes will impact your appraisal fees?”

FEE INCREASES

Over 40% of respondents said they expect their appraisal fees to increase. Still, many respondents (28%) said they anticipate that fees will remain static, and 31% said they are not sure yet. Read their comments below to learn why or why not some appraisers believe their fees will increase with the new URAR and UAD 3.6.

APPRAISER RESPONSES

I Expect Fees to Increase” (41%)

“I have had ample time to practice the new 3.6 through my software and the inspection time will be increasing substantially…. Inspections are going to take some time especially if the dwelling is more than 1,000sf, which most in my market area are well above that. The report cannot be submitted until all sections are 100% complete, so there will be more time contacting agents, homeowners, town facilities, etc. Hoping the learning curve will be quicker than it appears at this point in time.”

I Expect Fees to Stay About the Same” (28%)

FEES REMAIN THE SAME

“I think it will be more labor intensive in the field but easier once you get back to the office.”

“I expect fees to stay the same. There may be less form filling; however, the analysis will remain the same. It’s not about the form or the analytics tools we use; it’s the analysis itself.”

The Bottom Line

While many appraisers anticipate that UAD 3.6 and the new URAR will initially require more time, tighter workflows, and new technology investments, the longer-term outlook is more balanced and, in many ways, promising.

Transitions of this scale often come with short-term growing pains, but clearer data standards, more structured reporting, and modernized tools are designed to create greater consistency and efficiency once the learning curve levels out. As several respondents pointed out, it will take real-world experience to understand where timelines and workloads ultimately settle.

At the same time, the new form offers appraisers a stronger platform to demonstrate the depth of their analysis, judgment, and market expertise.

To read more, Click Here

My comments: THIS IS THE HOTTEST TOPIC IN RESIDENTIAL LENDER APPRAISING. Appraiser opinions are useful but we all want to know what AMCs are planning for fees. I anticipate higher fees by AMCs, borrowers and direct lenders. I have been writing about what is happening since early this year, including details of all the “questions” and uncertainties on the SFR report.

Another significant fee factor is that many appraisers are retiring or quitting because they don’t want to learn the UAD 3.6 for appraisers. Those who stay will have lots of appraisal work as the 11-2-26 mandatory deadline approaches.

UAD 3.6 is not mandatory until November 2, 2026. The Legacy forms will be used during the transition. Will it be done by 11-2-26? Now, software vendors and lenders are way behind. 11-2-27 new mandate date???

On the plus side, 41% of appraisers said fees would go up and are positive about the new reports.

Read more!! →

Appraisers – Disclose When You Did Not Do the Inspection 

Newz: 24 Hour Appraisal, Disclose When Some One Else Did the Inspection

November 7, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: When a Property Owner Wants to Do the Appraiser’s Job
  • The Hazards of Signing a URAR When Another Person Conducts the Inspection
  • Honolulu Diamond Head Estate for $34,000,000
  • The 24-Hour Appraisal Funded by Appraisers
  • How Policy, Data, and Technology Are Reshaping Lending and Valuation: MBA 2025 Recap
  • MBA: Mortgage applications decreased 1.9 percent from one week earlier

———————————————————————–

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

———————————————–


———————————————-

The Hazards of Signing a URAR When Another Person Conducts the Inspection

By Dan Bradley

Excerpts: When using the Uniform Residential Appraisal Report (URAR) to report the results of an appraisal, the appraiser’s signature on the report is not merely a formality, it is a certification. By affixing his or her signature, the appraiser is certifying to (among other things) having personally made an interior and exterior inspection of the subject property.

Clients, AMCs, and state regulatory agencies are reporting that appraisers are increasingly delegating their inspection responsibilities to others yet are signing the URAR certifying they made a personal inspection.

What are the risks if an appraiser signs a URAR report certifying an interior and exterior inspection that was actually conducted by someone else?

Conclusion

Signing a URAR appraisal report that states the appraiser personally inspected the property, when in fact another party performed the inspection, is a serious liability risk. USPAP permits an appraiser to value a property that they did not make an interior and exterior inspection.

However, USPAP does not allow an appraiser to communicate a misleading report. A report that falsely indicates that an individual made an inspection of a property when in fact they did not is misleading, and could result in disciplinary action, civil liability, or other negative consequences.

To read more, Click Here

My comments: Good reminder, especially with the use by the GSEs of alternative valuation methods. Of course, you know nothing about the qualifications of the person doing the inspection. The article did not specifically address UAD 3.6, but I assume it would have the same certification section and requirements.

Read more!! →

ChatGPT for Appraisers

Newz: Appraisers using ChatGPT,
Appraiser Salaries, PAREA Problems

May 16, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA ad: Appraisal Used in Divorce Case – Now What
  • The Power of AI Is Not Absolute Using Chat GTP for Appraisers
  • Retired Maine Railroad Caboose
  • [Updated 2025] What’s the Average Real Estate Appraiser Salary?
  • Indemnification Clauses: What Appraisers Should Know
  • Treasury yields surge, but Fed rate cut odds decline after U.S.-China tariff pause. Mortgage rates may be poised to rise following de-escalation of tariff tensions
  • The PAREA Program: Costly Promises, Empty Support
  • Mortgage applications increased 1.1 percent from one week earlier

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

————————————————————–


——————————————————————-

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


——————————————————–

The Power of AI Is Not Absolute
Appraisers Using ChatGPT

Excerpts: With the great power of artificial intelligence comes the responsibility to fact-check.

Artificial intelligence (AI), particularly ChatGPT, has captured the attention of professionals across various industries, including residential appraisal. With ChatGPT now reaching more than 100 million weekly users, according to OpenAI CEO Sam Altman, it’s clear that AI is poised to become a mainstay in our digital toolkit.

ChatGPT is an AI chatbot, powered by a large language model (LLM), which can comb through a vast amount of information and generate text in response to a question or prompt. This ability led me to explore its potential in “seeing” and evaluating property photos, which ultimately inspired me to create the RoboRater tool.

There were some early hiccups — and a learning curve — when I began prompting the AI tool to apply Uniform Appraisal Dataset (UAD) quality and condition ratings to what it “saw” in property photos. And then, in November 2023, Open AI introduced a feature allowing pro users to develop a custom generative pre-trained transformer (GPT), which led to a breakthrough. It enabled me, with no coding background, to tailor a specific version of ChatGPT that excels at assessing kitchen quality and condition ratings from photos, complete with insightful supporting commentary.

ChatGPT as a Writing and Public Relations (PR) Assistant

ChatGPT can also be an invaluable writing assistant and PR specialist, especially in sensitive communication scenarios like Reconsiderations of Value (ROV). It can skillfully rephrase blunt feedback into professional, constructive commentary.

Other topics:

Enhancing Clarity in Technical Reporting

Optimizing Appraisal Business Operations

Navigating the Limitations

To read more, Click Here

My comments: This is the most practical article I have read for appraisers using ChatGPT with good appraiser examples. I am going to start using it soon! Tim Andersen, the USPAP expert, recently wrote an article for Appraisal Today using ChatGTP.

AI does not always work out well.

For example. State Bar of California admits it used AI to develop exam questions.

Nearly two months after hundreds of prospective California lawyers complained that their bar exams were plagued with technical problems and irregularities, the state’s legal licensing body has caused fresh outrage by admitting that some multiple-choice questions were developed with the aid of artificial intelligence.

Read more!! →

Finding Comps with Few Sales for Appraisers

Newz: Pulling Comps in 2025, Appraiser Union? AMCs Overcharging Consumers

March 7, 2025

  • What’s in This Newsletter (In Order, Scroll Down)
  • LIA ad: Problem with An Affidavit
  • The struggle of pulling comps in 2025 By Ryan Lundquist
  • Op-Ed: Why An Appraiser Union Would Never Work By Dustin Harris
  • The Full Measure: February 2025 Housing Market Snapshot for Appraisers By Kevin Hecht
  • The Trump Administration’s Regulatory Overhaul: The Impact on CFPB, FHA, and the Housing Industry By Rob Chrisman
  • Homebuilders Warn of Rising Building Costs as Trump’s Tariffs on Canada and Mexico Take Effect By NAR
  • AMCs Overcharging Consumers? Morgan & Morgan Investigates
  • Mortgage applications decreased 1.2 percent from one week earlier

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news!


——————————————————————-


———————————————————————————-

The struggle of pulling comps in 2025

By Ryan Lundquist

Excerpts:

1) SALES TELL US ABOUT THE PAST

Comps aren’t easy today. The problem is there aren’t that many sales, so it’s not so simple to figure out value. Lately, I’ve been getting a ton of questions about this, so I wanted to share some things I’m doing on my end….

2) TWO OPTIONS TODAY

We have two choices for comps. Go back further in time in the immediate neighborhood, or go out further to competitive areas. Why not do both?…

3) HOW FAR AWAY CAN YOU GO FOR COMPS?

It’s not how far you can go, but where you should go. Read that again. This is true in any market. And where would buyers go for comps? That’s also a viable question. No matter where you’re getting comps, be sure they are a good substitution…

To read lots more plus see graphs and read appraiser comments, Click Here

My comments: Read This Article! Few sales are common in many areas. I prefer going back in time. I have been doing time adjustments since 1975, when prices were going up 5% per month in a semi-rural Northern California county. The GSEs seem to be making it way more complicated. I do them on every appraisal. If not needed, I always comment that the market is stable. It is the only adjustment I make on my non-lender appraisals, except for features that are unusual.

I have no idea why the GSEs complain that many appraisers are not doing them when needed. Maybe the appraisers never learned how? Many dollar adjustments are needed on the grid and can be much more difficult than time adjustments.

Read more!! →

AI and Appraisers

Newz: AI Limits, VA News, New UAD,
Hurricane Risks

October, 11 2024

What’s in This Newsletter (In Order, Scroll Down)

  • Intended Use and User (LIA Ad)
  • The Limits of AI: When the intelligence is artificial, common sense is a superpower
  • Vila Siena In Bel-Air CA Is The Most Insane Mega-Mansion EVER at $177,000,000
  • The New UAD: Opportunity, Confusion or Threat?
  • What’s New at the VA? A Q&A With Its Chief Appraiser
  • Effects of Hurricane Helene
  • Is Anywhere Safe From Hurricanes? The 10 States With the Lowest Risk of Damage
  • ————————————————————————————–
  • Appraisal Business Tips 


The Limits of AI: When the intelligence is artificial, common sense is a superpower

By John Russell

Excerpts: At some point, all of us will integrate AI tools into our business practices. Whether it automates mundane and repetitive tasks, generates narrative text, or assists with analyses, the power of AI to save time is real.

The good news for valuation professionals is they have lots of experience spotting data points that don’t jibe with what they know. Another way to say this is that they have common sense. It’s a basic requirement for doing the work. Of course this 3-story overbuilt McMansion is probably not a comparable for a Cape Cod two miles away. That sale was under atypical conditions and, at minimum, needs adjustments to even be considered. You get the idea.

Do I trust what the AI is telling me?

Accepting AI outputs without any skepticism is a recipe for disaster. Approach AI like a detective interviewing witnesses: trust, but verify. Basic internet searches can quickly fact-check results — or raise enough red flags that you reject what is being offered. No state board will accept the argument, “But ChatGPT said,” and neither should you….

Should I be using AI for this task?

Just because you can doesn’t mean you should — commit this phrase to memory. You will have to own everything in your report, and if too much of the product is driven by AI tools, you may be asked: “Well, what exactly did you do here?”…

Common sense is a superpower that can protect you from dire consequences as you experiment with AI. It’s tempting to be spellbound by new AI tools that seem miraculous — and to let down your guard of common sense. Instead, I recommend a heightened sense of caution: The tools are only as good as the people who craft them and the inputs provided by the users. AI hallucinations are still unpredictable, inevitable failure points, which means any “facts” and analyses it supplies should always be verified — it’s just common sense

To read more, Click Here

My comments: Good, practical analysis of AI for appraisers.


—————————————————————————————-

Read more!! →

Appraising Factory-Built Houses

Factory-Built Houses: Types, Benefits, and Tips for Appraisers

By Dan Bradley

Excerpts: Factory-built houses are an important, yet often overlooked, part of the American housing market. Approximately 10% to 12% of new housing starts in the United States are factory-built. There are several advantages to building a house in a factory. For example, certain houses can be constructed for 50% less than a similar-sized site-built home, making quality housing more affordable for thousands of Americans. As an appraiser, your knowledge of factory-built housing is key to a credible appraisal.

This article examines several different types of factory-built houses, their five main advantages, and tips for appraising them.

Factory-built house is a term that refers generally to a number of house types that are constructed or fabricated, at least in part, off site. The prefabricated components are transported to the site and finished or reassembled there. By contrast, site-built, or “stick-built,” homes are put together at the building site from thousands of individual pieces (e.g., studs, nails, sheets of drywall, shingles, wires, pipes, electrical outlet boxes).

For appraisers, understanding the specific type of factory-built house you’re dealing with is key. It tells you which building codes apply, gives you clues about the construction process, and impacts how you approach the valuation.

Factory-built homes include:

  •   Mobile homes
  •   Manufactured homes
  •   Modular homes
  •   Panelized homes
  •   Pre-cut or kit homes

To read more, Click Here

My comments: This is worth reading, especially if you appraise these types of homes. It provides ver