
Newz: Changing UAD 3.6 Appraisal Software, Appraiser Survey Results
November 20, 2026
What’s in This Newsletter (in Order, Scroll Down)
Article List
- LIA AD: Completion Certificate Assignment
- Why, After 32 Years, I Am Changing Appraisal Software Companies, By Dustin Harris
- Iconic 1960 Midcentury Modern ‘Wave House’ Is Back on the Market—With a Twist Listed for $1,6 Million in Lambert, NJ
- The Survey Responses Are in & They’re Pretty Eye Opening
- My AD: Make Use of Your Driving Time by Exercising
- Thirty Years of Appraising Homes: What Technology Changed and What It Never Could, By Joseph A. Mier, SRA
- 7 Considerations for a Restricted Appraisal Report, By Kevin Hecht
- MY UAD 3.6 UPDATE: Datamaster has new UAD 3.6 software, link to FCC to get broadband access, by address.
- MBA: Mortgage applications decreased 2.3 percent from one week earlier Plus additional mortgage information and comments.
Why, After 32 Years, I Am Changing Appraisal Software Companies
By Dustin Harris
Excerpts: “Dustin, if you leave TOTAL and marry another software company, you’re going to be unhappy in six months.”
I have heard some version of that more times than I can count since the November 2 mandate for UAD 3.6. And honestly? They might be right. If I were getting married.
I’m not.
Let me back up. For 32 years I have written reports in TOTAL. For most of that time I’ve told appraisers to stay with TOTAL, and my reasoning never changed: it costs more, but nobody has more bells and whistles, so it’s worth it. Full disclosure, TOTAL sponsored my program for years. I was paid to say nice things about them, and every nice thing I said was true.
So when I tell you our office is leaving TOTAL when our subscription runs out on December 15, I want you to hear what I’m saying and what I’m NOT saying. I’m not leaving because TOTAL got worse. When I had to make the call on 3.6, for my office and my timeline, I didn’t feel they were quite ready for the transition… (In fact, I’m still using TOTAL’s mobile app in the field right now, because for the way we work it’s the best one out there.)
I’m leaving because what I need changed.
You’re going to hear that I’m moving to SFREP and their Appraise-It Pro. Technically, that’s true. That’s where my reports will go out the door. But here’s the honest truth: I’m not leaving TOTAL to go to SFREP. I’m leaving TOTAL to go to my own system.
Over the last couple of years I’ve learned how to use AI to build the bells and whistles myself. A comp analysis tool like the ones I used to pay for every month.
To read more, Click Here
My comments: Dustin’s article is worth reading. I have been hearing about frustration with Total for a while. It was the most popular 2.6 software with about a 50% market share since 2.6 started in the early to mid 1980s.
In early 2026 I had a demo of total inspection app. It was great!
I usually suggest using another software program while waiting for Total to finish the 3.6 version. I suggest SFREP as it is easy to learn and AIVRE if you want some AI.
——————————————————-
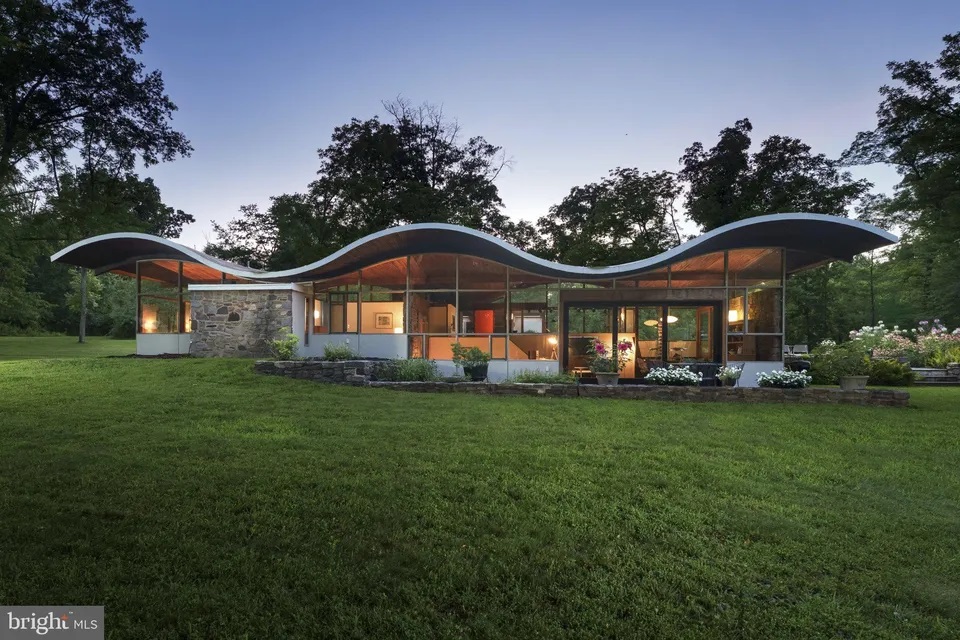
Iconic 1960 Midcentury Modern ‘Wave House’ Is Back on the Market—With a Twist Listed for $1,6 Million in Lambert, NJ
Excerpts: 4 bedrooms, 2 baths, 1,700 sq.ft., Built in 1960
Modernist architect Jules Gregory’s iconic “Wave House,” which was offered together with a sleek studio in Lambertville, NJ, earlier this year is now available for individual purchase.
“The condo status was recently approved, so now you can get the Wave House for $1.65 million, the studio for $995,000, or both for $2.6 million,” says listing agent Grant Wagner of Callaway Henderson Sotheby’s International Realty. “What makes this unique is if you wanted to buy both, you have the option to sell one later.”
Built in 1960, the four-bedroom primary residence, known for its wavy roofline, has 1,700 square feet of midcentury space, including curvy wood ceilings that rise and dip above the rooms, glass walls and doors, exposed beams, stone details, and oversized windows framing the picturesque lot.
To see the listing with a 3D aerial and 29 photos, Click Here
———————————————————
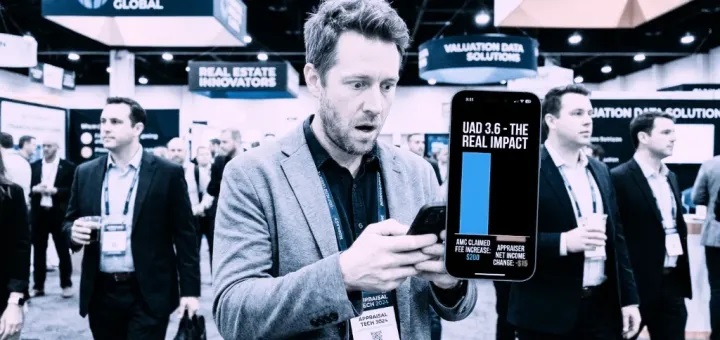
The UAD 3.6 Survey Responses Are in & They’re Pretty Eye Opening
Excerpts: The initial survey responses are officially in, & the preliminary findings are a total eye opener for anyone wondering what’s really happening on the ground.
Two Weeks, 400+ Appraisers, and Some Questions Worth Asking
Two weeks ago, we launched the 2026 Independent Appraiser Survey: UAD 3.6, AMC Fees & Industry Concerns, hoping to get a better understanding of what independent appraisers across the country are experiencing.
We knew we weren’t alone in our frustrations, but we weren’t sure how many others were dealing with the same issues.
Well, the responses are coming in! As of November 9th, we’ve received 415 responses from appraisers in 48 states, and some of the preliminary results are pretty eye-opening.
More Work, Same Pay?
Among 288 respondents who have completed at least one UAD 3.6 appraisal:
Nearly 99% report that comparable assignments take more time to complete.
~89% say they take significantly more time.
Almost 77% of those providing a definite AMC fee comparison report unchanged or lower fees for UAD 3.6 assignments.
And Then There Are the AMCs…
After initially publishing the survey, we added a few questions about the unpaid time appraisers spend reviewing AMC quote requests, researching properties, and submitting bids that often seem to disappear into thin air.
Of the 360 respondents who answered the applicable question, approximately 74% say they often or almost always prepare quotes without receiving a response.
Sound familiar?
To read more, Click Here
My comments: Great to have an appraiser UAD 3.6 survey!
——————————————————————-
Are you getting too many ad-only emails?
4 ways to get only the FREE email newsletters and NOT the ad-only emails.
1. Twitter: https://twitter.com/appraisaltoday Posted by noon Friday
2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page. NOTE: the popular ads with liability tips are below the first topic on my blog posts.
3. Email Archives: https://appraisaltoday.com/archives
(posted by noon Friday) The link is above and to the left of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.
4. Link to the 8 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block. The newsletters have abbreviated titles, taken from their blog posts.
To read more about the 4 ways, plus information on why I take ads, etc.
————————————————–
Make Use of your Driving Time by Exercising
In the March, 2025 issue of Appraisal Today
I keep hearing about the value of exercising for being healthy. But who has time (or wants) to excercise? Exercising also helps reduce stress.
Appraising is a fairly sedentary job, with most of the time spent sitting in a car or at a desk. Do you take time to exercise every day? Do feel stressed out
when you are running late for an appointment? Do you feel stressed as a deadline approaches?
One of the best and worst times in appraising is driving. Working out in the
field is what attracted many of us to appraising, including myself. But the time
spent driving is unproductive time for most of us.
There are so many stresses today. Exercising is a great stress reducer!
Although the exercises below are for driving, many can also be used in your
office. I also keep hearing about how sitting down a lot is not good for your health.
Here are a few driving exercises:
Head and neck exercises
- Tilt your head toward your left shoulder, hold for 2-3 seconds, then tilt toward your right shoulder.
- To relax your jaw and face, pretend you are blowing out candles. Focus on the relaxed feeling.
- Flatten your back against your seat and push your chin down, stretching
- your neck.
- Extent your head forward, then back, keeping it centered.
Shoulder exercises
Do “shoulder shrugs” where you bring your shoulders up to your ears, one at
time, then both. Drop your shoulders quickly, focusing on the relaxed feeling.
Arm and hand exercises
For steering wheel exercises, put your hands in the 10:00 and 2:00 position.
Squeeze the steering wheel tight, pushing inward for 2-3 seconds, then release.
Keep a relaxed grip on your steering wheel, to keep tension from moving up
to your face, neck, and shoulders. One at a time, lift your fingers off the steering wheel, then lightly put them back.
To read more about this topic read the full article, plus 2+ years of previous issues, subscribe to the paid Appraisal Today at www.appraisaltoday.com/order .
Not sure if you want to subscribe?
Sign up for monthly auto renewal for $8.25!
Cancel at any time for any reason! You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
What’s the difference between the Appraisal Today free Weekly email newsletter and the paid Monthly newsletter? Click here for more info.Subscribe to Monthly NewsletterIf you are a paid subscriber and did not receive the November, 2026 issue emailed on November 2, 2026, please email info@appraisaltoday.com, and we will send it to you. You can also hit the reply button. Be sure to include a comment requesting it.
————————————————–
Thirty Years of Appraising Homes: What Technology Changed and What It Never Could
By Joseph A. Mier, SRA
Excerpts: In 1993, I started appraising real estate with a 100-foot tape measure, a DOS computer and paperback MLS books. Yes, paperback MLS books.
I Didn’t Throw Away the Tape Measure
One of the first major pieces of technology that changed how I worked was a laser measuring device. I had been trained using that 100-foot tape measure. When I got the laser, I didn’t immediately trust it. For about nine months, I carried both. I would measure with the laser and verify it. Then I would do it again.
Then Everything Started Changing
The laser was only the beginning. Film cameras became digital cameras. Paperback MLS books disappeared as MLS systems moved online. Paper maps gave way to GPS and digital mapping. Public records became accessible from our computers. Eventually, the phone in my pocket became more powerful than the DOS computer I started with in 1993. Then came mobile data collection, aerial imagery, cloud-based appraisal software, statistical analysis, automated valuation models and increasingly sophisticated quality-control tools.
And now we have AI.
Artificial intelligence is the latest major change, and I believe we are still in the early stages of understanding what it can do for our profession. I use AI. I am excited about its potential. But AI has one characteristic every appraiser needs to understand. It can be confidently wrong. It can produce an answer that looks great, sounds great and is completely unsupported. That means the appraiser needs enough knowledge, competency and experience to recognize when the answer doesn’t make sense.
Fast Forward to recent Las Vegas National Conference – Technology Changing Again
There were a number of startup technology companies introducing innovative software and new approaches to collecting data, analyzing information and producing appraisal reports. Some of what I saw was impressive.
Some was very different from the traditional appraisal workflow many of us have used for years.
Walking through the Expo, I couldn’t help but think about where I started. A 100-foot tape measure. Paperback MLS books. A DOS database. Now I am standing in Las Vegas looking at AI-driven platforms and technology that may completely change how an appraisal report is produced.
Technology is changing. The appraisal process isn’t.
Our responsibilities under USPAP don’t disappear because the software becomes more sophisticated.
Test It. Test It. Test It.
So what should appraisers do with all this new technologyUse it. I’m certainly going to.
But test it. Test it. Test it. Test it.
Don’t reject technology simply because it changes the way you’ve always done something. But don’t blindly trust software because it is new, fast or has the letters “AI” attached to it either.
To read more, Click Here
My comments: Worth reading. Some good analyses and ideas.
7 Considerations for a Restricted Appraisal Report
By Kevin Hecht
Excerpts: What Is a Restricted Appraisal Report?
A Restricted Appraisal Report is a type of appraisal report that is limited in content and intended use. It is a written statement setting forth the appraiser’s analyses and conclusions but does not provide as much detail or explanation as an Appraisal Report.
A Restricted Appraisal Report may be appropriate when the client, and any named intended users, don’t need the level of detail in an Appraisal Report and the intended use allows for it. However, according to Advisory Opinion 38 (AO-38), it is not appropriate to issue one solely because the client is the only intended user. It is typically not used for mortgage lending.
TOPICS INCLUDE:
Key Considerations for Using a Restricted Appraisal Report
1. Appraisal Report vs. Restricted Appraisal Report
2. Reporting Requirements
3. Which Is Appropriate?
4. Clients and Intended Users
5. Use Restriction Statement
A Restricted Appraisal Report may contain less detail than an Appraisal Report, but it still requires care and diligence to ensure USPAP compliance. Make sure your workfile is sufficient to produce an Appraisal Report. And remember, a well-documented workfile is your best defense should your work come under scrutiny.
To read more, Click Here
My comments: Finally something about appraising that many appraisers have not done! UAD 3.6 is not relevant!!
Unfortunately, the article does not discuss when you would use a Restricted Report. It is typically not used for mortgage lending. I have never done a Restricted Report but know residential (and commercial) appraisers who do them.
Here are a few examples for residential appraisers:
• Dispute Resolution & Divorce Settlements: When co-owners, divorcing parties, or legal representatives need an independent value for negotiation or mediation rather than a formal, comprehensive narrative report for a lending institution.
• Estate Planning & Internal Accounting: When family members, trustees, or estate planners need a baseline asset valuation for internal distribution or trust management where all parties are named intended users.
• Recurring or Portfolio Valuations: When an appraiser who has valued the same or similar residential property many times in the past performs a repeat or update evaluation for a repeat client who knows the property well.
• Preliminary Tax Dispute Assessment: When a homeowner or investor wants a preliminary value opinion to decide whether it is worth formally disputing local property taxes.
———————————————————————
MY UAD 3.6 UPDATE
Datamaster is added to the GSE validation list for UAD 3.6 software. Their UAD 3.6 software is available at www.datamasterusa.com . I check this list regularly.
FCC Broadband map for UAD 3.6
displays addresses where high speed internet services are available across the United States, as reported by Internet Service Providers (ISPs) to the FCC. The map will be updated continuously to improve its accuracy using FCC verification efforts, new data from internet providers, updates to the location data, and information from the public.
https://broadbandmap.fcc.gov/home
This database does not have every address, but it is better than guessing or making a lot of calls. GSEs are considering adding Starlink and other options not on Earth.
——————————————————————–
HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, Click Here.
My comments: Rates are going up and down. Many appraisers are not busy. Some are busy, usually with non-lender appraisals. We are all hoping for lower mortgage interest rates in 2027!
Mortgage applications decreased 2.3 percent from one week earlier,
According to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending November 13, 2026.
The Market Composite Index, a measure of mortgage loan application volume, decreased 2.3 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 5 percent compared with the previous week. The Refinance Index decreased 2 percent from the previous week and was 54 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 3 percent from one week earlier. The unadjusted Purchase Index decreased 7 percent compared with the previous week and was 18 percent lower than the same week one year ago.
“Treasury yields rose last week amid data showing inflation accelerated in October and Fed officials acknowledging that additional rate hikes may be needed in the coming months. Mortgage applications dipped as mortgage rates moved higher, with the 30-year fixed mortgage rate up to its highest level in three weeks at 7.35 percent,” said Joel Kan, CMB, MBA’s Vice President and Deputy Chief Economist. “Purchase applications were down 18 percent from a year ago, as renewed affordability challenges from elevated mortgage rates have pushed prospective homebuyers to the sidelines. Overall refinance activity was down over the week, but FHA refinances increased almost 7 percent. The FHA rate was around 30 basis points below the conforming rate, which supported refinance opportunities for some homeowners.”
The refinance share of mortgage activity increased to 41.1 percent of total applications from 39.8 percent the previous week. The adjustable-rate mortgage (ARM) share of activity decreased to 10.8 percent of total applications.
The FHA share of total applications increased to 16.1 percent from 15.5 percent the week prior. The VA share of total applications increased to 12.8 percent from 12.4 percent the week prior. The USDA share of total applications remained unchanged at 0.5 percent from the week prior.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 7.35 percent from 7.21 percent, with points increasing to 0.79 from 0.75 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) increased to 7.31 percent from 7.21 percent, with points increasing to 0.56 from 0.47 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 7.06 percent from 6.98 percent, with points increasing to 1.07 from 1.06 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 15-year fixed-rate mortgages remained unchanged at 6.64 percent, with points increasing to 1.03 from 0.97 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 5/1 ARMs increased to 6.38 percent from 6.28 percent, with points decreasing to 1.07 from 1.14 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.
————————————————–
 Ann O’Rourke, MAI, SRA, MBA
Appraiser and Publisher Appraisal Today
1826 Clement Ave. Suite 203 Alameda, CA 94501
Phone: 510-865-8041
Email: ann@appraisaltoday.com
Online: www.appraisaltoday.com
We want to know what you think!! Please leave a comment.