
Newz: UAD 3.6: Fees, Turn-Time, Software and more, AMC Panel Requirements
October 30, 2026
ARTICLE LIST – In order, scroll down the page to read
- LIA AD: AMC Panel Requirements
- UAD 3.6: Inside the Struggle Over Fees, Turn-Time and Software By Frank Andorka, Managing Editor WorkingRE
- A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market
- What is Highest and Best Use in Appraisal? (Updated for UAD 3.6) , By Kevin Hecht
- MY AD: What Enough of UAD 3.6, I Have a Business to Run!, By Doug Smith, MBA, SRA
- UAD 3.6: A New Era of Accountability in Appraisal Quality, By Gynell Vestal (Administrator) American Valuation Society
- Flock Camera Blunders and the Privacy Risks of UAD 3.6, By Desiree Mehbod
- MBA stats: Mortgage applications increased 3.4 percent from one week earlier
Thanks to our Sponsor!!
——————————-————————-
UAD 3.6: Inside the Struggle Over Fees, Turn-Time, Software and more
By Frank Andorka, Managing Editor, Working RE
Excerpts: Editor’s Note: Since this article was written, the GSEs created an exception to UAD 3.6 implementation for sellers who aren’t able to make the full transition to the new standard before Nov. 2. The exception runs through May 19, 2027. The GSEs will also allow resubmissions of UAD 2.6 appraisal reports through June 27, 2027. As of March 1, 2027, UAD 2.6 appraisals will no longer qualify for certain appraisal-related representations and warranties relief. For more, check out our full report at workingre.com:
GSEs Create Exception for UAD 3.6 Deadline: Runs through May 19, 2027.
To read: Click Here
Nov. 2 is usually just another day on the calendar — but not this year
Timeline and Rollout
The rollout of UAD 3.6 has been hampered considerably by two problems: slow software rollouts and lenders dragging their feet. When Working RE covered Valuation Expo in Las Vegas at the end of August, the problems clearly came into view.
While most of the leading software providers received initial approval from the GSEs in late 2025 and early 2026, word on the ground at Valuation Expo (Val Expo) was that there were still plenty of bugs to work out. AMC executives privately shared that they had staff simultaneously testing all the GSE-approved reporting software so they could troubleshoot and support appraisers when they inevitably ran into problems trying to turn in assignments. Some of those bugs were being run back to the software companies in real time, with the appraiser, AMC, lender and software provider working through the problem together.
The bigger problem in August was that lenders had barely begun ordering the 3.6 appraisals at all. Rocket Mortgage staff at Val Expo said they had ordered six UAD 3.6 appraisals. Rocket originates roughly six to seven percent of all residential mortgages in the United States. Several regional AMCs reported completing exactly two assignments apiece — and in each case, one of the two was a test run the AMC had ordered itself.
Scott Reuter, chief appraiser at Freddie Mac, summed up the bind on a panel at the show: “Appraisers cannot do a 3.6 assignment unless somebody orders a 3.6 assignment.”
More Than 900 Data Elements
There were approximately 190 data elements in UAD 2.6. There are now more than 900 in UAD 3.6. Reuter says it’s easy to be overwhelmed if appraisers just hear the number, but he assures the industry that appraisers were in the room when the form was developed.
“I want to make sure they don’t just hear ‘more than 900 elements’ and worry that they won’t be able to do it,” Reuter says. “They won’t have to fill out all those data points for every property. They are never going to touch the lion’s share of them, but we wanted to make sure we accounted for every potential contingency just in case.”
Lyle Radke, senior director of collateral policy at Fannie Mae, says Fannie and Freddie hold, between the two of them, $7 trillion in mortgage debt which, since it’s backed by the U.S. Treasury, is guaranteed by U.S. taxpayers. Therefore, it stands to reason collecting more data than before is important.
“From that perspective, the data is essential,” Radke says. “It’s how we manage risk. UAD 3.6 makes it easier for us to see and understand the data. If we didn’t have 3.6, we could still parse the data, but it would be much more challenging and time consuming.”
Other topics include turn times, liability and fees.
As the industry rushes toward the Nov. 2 deadline, appraisers’ stress levels will continue to rise. The only question is: What will things look like when the smoke clears? Only time will tell.
To read more, Click Here
My comments: Good discussion of the issues with quotes from many people, including GSEs. Not many changes since the August conference, except software vendors are still sending out updates. Fees still unclear.
——————————————————–
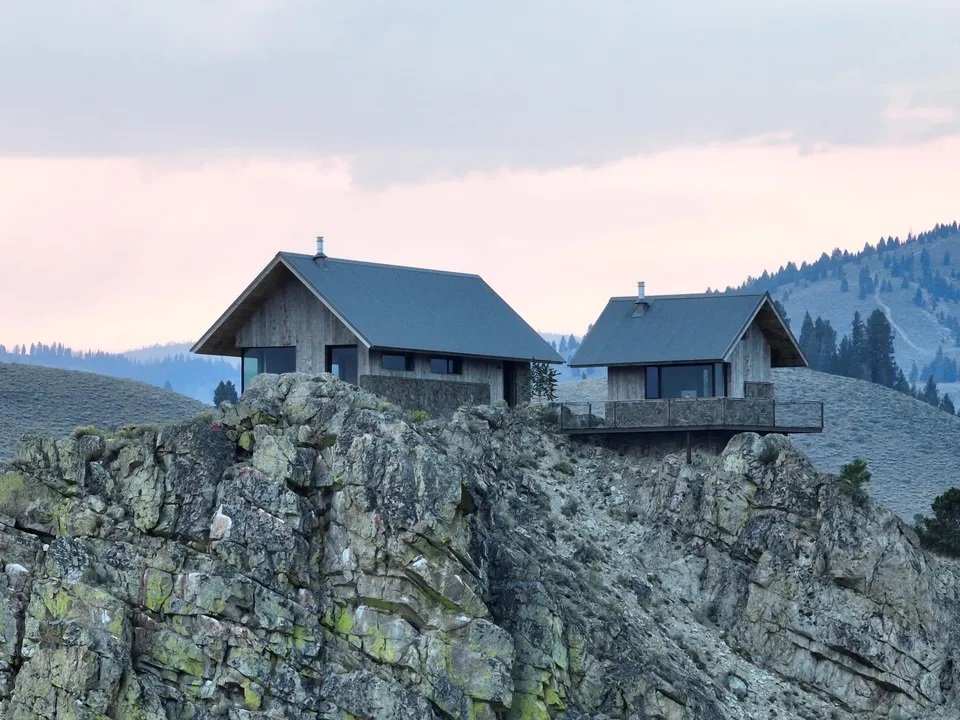
A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market for $2,299,000
Excerpts: 1 bedroom, 1 bath, 306 sq.ft., 3.06 Acre lot, Built in 2026
It’s all about location, location, location for two newly built mountain cabins perched atop a cliff outcropping in Idaho that have just hit the market.
Located on 3.06 acres in Stanley, where “snowmobiling, hiking, and mountain biking adventures begin right outside your door,” The sleek residences are surrounded by sweeping views of the Stanley Basin, the Sawtooth Mountains, Valley Creek, and the Salmon River. They come with “direct access to vast stretches of surrounding wilderness.”
A primary 900-square-foot cabin features a vaulted wood ceiling, wood-burning stove, heated flooring, modern kitchen, full bathroom, and sleeping loft.
The secondary structure has a loft and wraparound deck. It also offers flexible space that could be used for guest accommodations, a studio, home office, or fitness center.
Just minutes from downtown Stanley, the gated property also borders 465,000 acres of National Forest land.
To see the listing with 45 photos and an aerial view, Click Here
——————————————————–
What Is Highest and Best Use in Appraisal? (Updated for UAD 3.6)
By Kevin Hecht
Excerpts: What’s New: Fannie Mae’s HBU Policy Under UAD 3.6
For residential appraisers, highest and best use is more than a valuation concept. It is also a GSE eligibility requirement, and in September 2026, Fannie Mae changed it.
In Selling Guide Announcement SEL-2026-08, Fannie Mae updated its HBU policy for appraisals completed on the redesigned Uniform Residential Appraisal Report (URAR) under Uniform Appraisal Dataset (UAD) 3.6.
What Changed
Residential use, not present use. Under the prior guidance, the present use of the property generally had to be its highest and best use. Now the property’s HBU, as improved or as proposed, must be a residential use. It no longer has to be the present use.
Primarily residential 1-4 unit properties. The property must be primarily a one- to four-unit residential property, and any non-residential use must be subordinate to the residential use. This replaces the earlier “residential in nature” standard. Fannie Mae’s UAD 3.6 Policy Supplement defines present use, residential use, and subordinate use for this purpose.
A path for properties that fail an HBU test. The update sets eligibility criteria and reporting requirements for one- to four-unit residential properties whose present use fails one or more of the four HBU tests.
When It Applies
The policy applies to appraisals completed on UAD 3.6. It does not apply to appraisals completed on the legacy forms. As of November 2, 2026, UAD 3.6 is required for new submissions to the Uniform Collateral Data Portal (UCDP), so most Fannie Mae appraisals now fall under the new policy.
Some lenders have more time. Under a temporary exception announced September 30, 2026, approved sellers that requested it from Fannie Mae or Freddie Mac can keep submitting UAD 2.6 appraisals on the legacy forms through May 19, 2027. UAD 3.6 becomes mandatory for everyone on May 20, 2027. Until then, you may get assignments in both formats. The new HBU policy applies only to UAD 3.6 reports, so confirm your client’s UAD requirements before you accept an assignment.
Freddie Mac has not made the same HBU change. As of its September 2026 guide update, Freddie Mac still requires the present use to be the highest and best use. Because the two GSEs now differ, confirm with your client which guidelines apply when the present use is not the HBU.
What It Means in Practice
Consider an older single-family home on a lot that was recently rezoned for townhomes. The existing house may no longer be the maximally productive use of the site. Under the old approach, that conflict could raise an eligibility problem. Under UAD 3.6, the HBU is still residential, so the property may remain eligible if it meets Fannie Mae’s criteria and the appraisal reports the analysis as required.
The redesigned URAR also puts more weight on narrative, evidence-based support for the HBU conclusion than the legacy forms did. Be ready to explain why the market supports a residential use, whether any non-residential use (such as a home-based business or agricultural outbuildings) is subordinate, and, when the present use fails a test, which test it fails and why.
For exact definitions and reporting requirements, read the UAD 3.6 Policy Supplement.
Topics also included:
Many general HBU topics.
Survey: What’s the Most Common Error Appraisers Make When Performing an HBU Analysis?
To read more, Click Here
My comments: THIS IS A SIGNIFICANT HBU CHANGE ONLY FOR UAD 3.6!
My November 2026 Appraisal Today issue has a long article about Fannie’s HBU changes written by Denis Desaix, MAI, SRA, a HBU expert.
After reading Denis’ detailed article, I had difficulty understanding what has changed and what it means. The Playbook (below) helped me significantly.
Be sure to read these documents:
MOST IMPORTANT DOCUMENT
The Highest and Best Use Playbook – An excellent presentation of the “big picture” for this New HBU requirement for UAD 3.6
https://singlefamily.fanniemae.com/media/47851/display
—————-
Highest and Best Use Frequently Asked Questions
https://singlefamily.fanniemae.com/media/48061/display
—————————————————————–
UAD 3.6 Policy Supplement
https://singlefamily.fanniemae.com/media/42571/display
—————————————————————-
Why did Fannie do this?
To make more properties eligible for Fannie mortgage loans. No more clicking the NO box for conforms to HBU requirements. UAD 3.6 does not have a No box. Today, in many areas, there are few homes available for purchase with high prices.
——————————————————–
Are you getting too many ad-only emails?
4 ways to get only the FREE email newsletters and NOT the ad-only emails.
1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters
2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.
3. Email Archives: https://appraisaltoday.com/archives
(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.
4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.
To read more about the 4 ways, plus information on why I take ads, etc. Click here
——————————————————–
Enough of UAD 3.6, I Have a Business to Run!
Revenue Strategy: Managing the Business (Part 1)
By Doug Smith, MBA, SRA
In the November 1, 2026 issue of Appraisal Today
Excerpts:
“A time of turbulence is a dangerous time, but its greatest danger is a temptation to deny reality.” – Peter F. Drucker
The transition to UAD 3.6 is proving to be one of the most disruptive
changes many appraisers have experienced in their professional careers.
What initially appeared to be a change in reporting requirements has become a far more extensive transformation of the appraisal process.
Established workflows are being reconsidered. Familiar software
procedures are changing. New equipment, training, and additional expenditures may be required. Even experienced appraisers are discovering that the time and effort needed to complete an assignment may no longer resemble what they have come to expect.
The full economic consequences remain uncertain. But one thing is
becoming clear: That realization presents an opportunity.
Rather than concentrating exclusively on adapting our reports, perhaps this
is the appropriate time to reconsider something more fundamental: What do we want from our careers as professional appraisers?
Peter Drucker encouraged organizations to begin with a fundamental
question: What is our mission?
For appraisers, the answer must recognize our responsibility to the public
trust. Our work supports decisions by people and institutions relying on credible opinions of value. Our professional obligations extend beyond satisfying the company ordering the appraisal.
We are appraisers. Our responsibility is to analyze real estate markets,
interpret market evidence, and develop credible opinions of value.
Our primary purpose is not to make a software program work.
To read more about this topic in Part 2, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.
If this article helped you understand your business better, it is worth the subscription price!
—————————————————————-
Not sure if you want to subscribe?
Sign up for monthly auto renewal for $8.25!
Cancel at any time for any reason!
You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
To purchase the Monthly Appraisal Today newsletter:
www.appraisaltoday.com/order or call 510-865-8041
What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info
Cancel at any time for any reason!
You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
To purchase the Monthly Appraisal Today newsletter:
www.appraisaltoday.com/order or call 510-865-8041
——————————————————–
UAD 3.6: A New Era of Accountability in Appraisal Quality
October 26, 2026
By Gynell Vestal (Administrator) American Valuation Society
How standardized appraisal data could transform secondary market risk management, lender oversight, and the future of appraisal development.
Excerpts: What happens when the secondary mortgage market can evaluate appraisal quality with a level of consistency, transparency, and sophistication that wasn’t previously possible at scale?
I believe this is where UAD 3.6 has the potential to fundamentally change the valuation industry.
Not simply by changing how appraisals are reported, but by creating greater accountability throughout the entire valuation process, from the secondary market to lenders, AMCs, and ultimately the appraiser developing the opinion of value.
The Real Significance of Standardized Appraisal Data
UAD 3.6 is fundamentally a reporting standard. It doesn’t change the principles of appraisal development or the appraiser’s responsibility to produce a credible opinion of value.
What it changes is how appraisal information is structured, communicated, and made available for analysis.
Historically, appraisal reports have contained a significant amount of narrative information, often presented with varying levels of detail and consistency. While lenders and secondary market participants have long employed automated collateral review tools, the limitations of legacy reporting formats have constrained how comprehensively certain appraisal information can be analyzed across large volumes of reports.
UAD 3.6 introduces a more structured, standardized dataset that creates opportunities for increasingly sophisticated automated analysis.
And that has implications far beyond the appraiser’s reporting software.
Structured data can make it easier to identify inconsistencies, evaluate reported property characteristics, compare appraisal information against external datasets, and flag potential deficiencies for further review.
As analytical technology and artificial intelligence continue to advance, these capabilities can become even more powerful.
But the real significance isn’t simply that more appraisal data can be analyzed.
It’s who can analyze it, how consistently it can be evaluated, and what happens when weaknesses are identified.
The Secondary Market: Where Accountability Begins
Consider the implications for the government-sponsored enterprises and other secondary mortgage market participants.
Their exposure to collateral risk makes the quality of the underlying appraisal an important component of mortgage risk management.
With more standardized and machine-readable appraisal data, secondary market participants have an opportunity to enhance their existing review systems, develop more sophisticated risk indicators, and identify potential appraisal deficiencies with greater consistency.
Rather than relying primarily on individual report reviews or limited automated checks, increasingly advanced analytical systems can evaluate patterns across large volumes of appraisal data.
Additional topics
- The Accountability Effect: From Secondary Market to Lender
- As the secondary market becomes better equipped to evaluate valuation risk, lenders have a stronger incentive to strengthen the quality-control processes that identify and address those risks before loan delivery.
- That accountability will naturally extend to the valuation service providers supporting those lenders.
What This Means for AMCs and Appraiser Performance
A Changing Landscape for Appraiser Panels
There’s another development worth considering, particularly from the lender and AMC side.
UAD 3.6 is already creating opportunities for appraisers who prepared early for the transition.
We Cannot Simply 2.6 the 3.6
I’ve been thinking about this distinction between reporting and development for some time.
UAD 3.6 changes the way appraisal information is reported, but the principles of credible appraisal development remain the same.
Appraisers must still identify and analyze relevant market data, select appropriate comparable properties, develop supportable adjustments, and reconcile their findings into credible opinions of value.
Better Data Must Lead to Better Quality Control
The Next Chapter of Appraisal Quality
The secondary market can use standardized data to strengthen valuation risk analysis. That creates greater accountability for lenders, which in turn creates stronger incentives for meaningful appraisal quality control and AMC oversight. Ultimately, those expectations reach the appraiser and the quality of the underlying appraisal development.
This accountability already exists in various forms. UAD 3.6 creates an opportunity to make it more consistent, more data-driven, and potentially more effective.
The real promise of UAD 3.6 isn’t simply a more modern appraisal report.
It’s the possibility of a valuation ecosystem in which better data supports better risk management, stronger accountability, and greater recognition of credible appraisal development.
That’s the opportunity I believe the industry should be preparing for.
To read more, Click Here
My comments Definitely worth reading. I had never read about this topic or even knew about the topic. Appraisers often forget about the lender side of UAD 3.6 and all lender appraisals.
——————————————————–
Flock Camera Blunders and the Privacy Risks of UAD 3.6
By Desiree Mehbod
A shocking Flock camera mistake triggered a midnight police raid on an innocent mother, exposing the dangerous reality of automated data overreach heading our way under UAD 3.6.
Excerpts: The Richmond police department just handed real estate appraisers the ultimate warning story about the dangers of automated data and algorithmic overreach. On July 29th, just before two in the morning, Richmond police officers woke up Rosalyn Crump, a mother of three, and towed her 2012 Hyundai Elantra right out of her driveway over a shooting she had absolutely nothing to do with.
The justification for this midnight raid was a hit from a Flock safety license plate reader camera. Body camera footage later revealed that officers walked up to the car, shined flashlights through the glass, and noticed children’s car seats buckled into the back.
The homeowner came outside and explicitly told the officers they had the wrong car, explaining her exact timeline for the day and the fact that the vehicle had been sitting idle. Instead of using human logic, looking at the physical evidence, or listening to the homeowner, an officer decided her story did not match the machine’s data and declared on camera that she was definitely not telling the truth.
We are watching a dangerous cultural shift where institutional systems place blind faith in digital data repositories while completely discarding human expertise and physical reality. In the Richmond towing case, a computer screen told an officer that a vehicle was involved in a crime, and that digital output instantly overrode the physical presence of children’s car seats and a mother’s direct testimony.
Appraisers are being forced into a parallel trap under the new UAD 3.6 data demands. Fannie Mae and Freddie Mac are demanding that we sweep through private residential spaces, capturing high-resolution interior photographs of bedrooms, living areas, hallways, and security setups, and then funnel that data into centralized, standardized databases accessible to unknown third parties.
When appraisers object to signing Certification 25, which strips away our core confidentiality defense and allows this private property data to be aggregated, corporate pragmatists tell us we are being dramatic. They claim the data is secure and meant only for secondary market functions.
But the Richmond incident proves that once a massive, standardized digital database exists, it will inevitably be hooked up to automated scanning tools and surveillance networks.
To read more, and watch the video of the encounter (near the bottom of the article)
To read more, Click Here
My comments: Worth reading. I had never thought (or read about) this aspect of UAD 3.6 increased data availability. Scary.HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.
Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.
My comments: Rates are going up and down in 2026.
—————————————————————————
Mortgage applications increased 3.4 percent from one week earlier
WASHINGTON, D.C. (October 28, 2026) — Mortgage applications increased 3.4 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 23, 2026.
The Market Composite Index, a measure of mortgage loan application volume, increased 3.4 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 3 percent compared with the previous week. The Refinance Index increased 3 percent from the previous week and was 61 percent lower than the same week one year ago. The seasonally adjusted Purchase Index increased 4 percent from one week earlier. The unadjusted Purchase Index increased 3 percent compared with the previous week and was 18 percent lower than the same week one year ago.
“Mortgage rates declined for the second week in a row, with the 30-year fixed rate decreasing to 7.37 percent, the lowest in three weeks. The decline in rates gave borrowers some relief, with applications rebounding slightly, particularly conventional applications,” said Joel Kan, CMB, MBA’s Vice President and Deputy Chief Economist.
“Mortgage rates are still more than a percentage point higher than the same week last year and most homeowners still have rates much lower than prevailing market rates. The ARM share of applications increased to 11.3 percent, the highest level in more than a year, as more borrowers applied for ARM loans to lower their monthly payments.”
Added Kan, “While purchase applications increased over the week, they were 18 percent behind last year’s pace as many homebuyers have put their purchase plans on hold. Similarly, refinance applications were down more than 60 percent from a year ago, as most borrowers have little to gain from refinancing.”
The refinance share of mortgage activity decreased to 38.9 percent of total applications from 39.0 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.3 percent of total applications.
The FHA share of total applications increased to 16.6 percent from 16.3 percent the week prior. The VA share of total applications decreased to 11.0 percent from 11.5 percent the week prior. The USDA share of total applications remained unchanged at 0.5 percent from the week prior.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.37 percent from 7.41 percent, with points increasing to 0.76 from 0.75 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.
The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.28 percent from 7.33 percent, with points increasing to 0.64 from 0.60 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.
The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.12 percent from 7.13 percent, with points decreasing to 1.07 from 1.15 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.
The average contract interest rate for 15-year fixed-rate mortgages decreased to 6.70 percent from 6.73 percent, with points increasing to 0.85 from 0.73 (including the origination fee) for 80 percent LTV loans. The effective rate remained unchanged from last week.
The average contract interest rate for 5/1 ARMs decreased to 6.41 percent from 6.46 percent, with points increasing to 1.20 from 1.11 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.
The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.
———————————————————–
 Ann O’Rourke, MAI, SRA, MBA
Appraiser and Publisher Appraisal Today
1826 Clement Ave. Suite 203 Alameda, CA 94501
Phone: 510-865-8041
Email: ann@appraisaltoday.com
Online: www.appraisaltoday.com
We want to know what you think!! Please leave a comment.