Appraisal Fees for Appraisers 11-13-26

Newz: Handling Low Fees, Fee Questions, Fees: AMC Class Action Lawsuit

August 13, 2026

Article List – in order. Scroll down the page to the topics.

    • LIA AD: When a property owner wants to do the appraisers job
    • UAD 3.6 Survival Guide: How to Set Your Fee and Push Back on Low Offers By Chase Pursley
    • This Off-Grid ‘Treehouse’ Is Perched 60 Feet in the Air—and Built From Shipping Containers Listed for $1.2 million in Epworth Georgia
    • The Fee Question You Should Stop Asking Other Appraisers, By Dustin Harris
    • MY AD: 2025 E&O Update – Claims, Payment Options, Lawsuits, Etc.
    • Class Valuation Faces Class-Action Suit Over Appraiser PaymentsBy Frank Andorka, Managing Editor, WorkingRE
    • AMCs – Locked Behind a Digital Iron Curtain, By Desiree Mehbod
    • MY UAD 3.6 Update: Fees vary widely, software vendors working on finishing software details and inspection apps. Excellent Facebook page on UAD 3.6, mostly software issues.
    • MBA STATS: Mortgage applications decreased 1.2 percent from one week earlier
Thanks to our Sponsor!!!

–———————————————

UAD 3.6 Survival Guide: How to Set Your Fee and Push Back on Low

By Chase Pursley

Excerpts: Stand Up for Your Fee on UAD 3.6 Orders

If your UAD 3.6 reports are taking longer at the same fee, you don’t have to absorb that. Compare the hours on similar assignments, then quote a fee that covers the work.

This post has no going rates and no fee surveys, and nobody here can tell you what a client will pay. Use your own records to explain what the assignment requires and what you charge.

Turn Logged Hours Into a Cost Per Report

Multiply your report hours by what you need to earn per hour, then add the costs tied to that report.

Set an hourly figure that covers your pay, taxes, and annual overhead. Then add only assignment expenses it doesn’t already cover, such as travel or a separate data purchase.

Here’s an illustration using $100 an hour and $50 in assignment expenses. These numbers are made up, and none of them is a suggested rate or fee. Substitute your own.

MORE TOPICS

      • Confirm the Scope and Fee Before You Accept an Order
      • Tell the AMC or lender what the report requires, then state your fee. A client can’t do much with “my costs went up.”
      • “This assignment is a UAD 3.6 report on a two-unit, and here is my fee for that scope” is something they can answer.

How to Answer a Low Fee

When an Order Offers Less Than Your Fee

AND MORE EXELLENT TOPICS WITH HOW TO RESPOND

To read more, Click Here

My comments: Definitely the best article I have read on AMC fees. Read the article and find out how to handle the Fee Issue.

—————————————————–
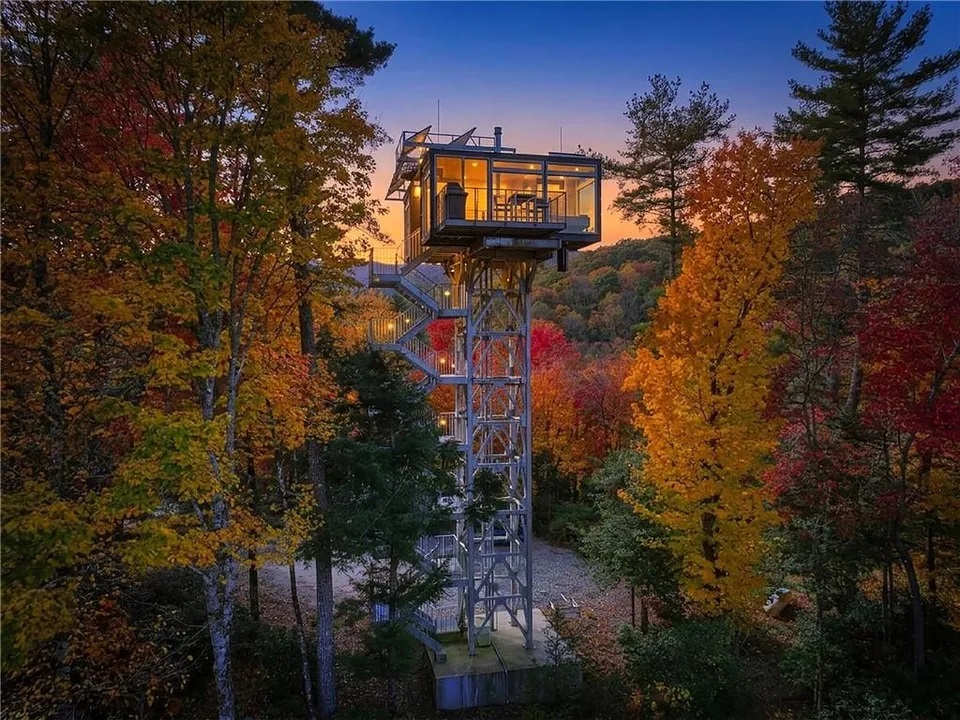
This Off-Grid ‘Treehouse’ Is Perched 60 Feet in the Air—and Built From Shipping Containers Listed for $1.2 million in Epworth Georgia

Excerpts: 1 bedroom, 1 bath, 14.31 acres, built in 2023

The structure itself is very unique. It’s a steel watchtower built to commercial grade but for residential purposes, purely for leisurely enjoyment, for getaways, for the adventurer at heart,” says listing agent Logan Fitts with Mountain Sotheby’s International Realty.

The 60-foot-high tower sits on 14.31 acres of land adjacent to the Chattahoochee National Forest with about 3,000 feet of river frontage. Two shipping containers are perched atop the tower, creating the living space.

“The main structure is the bedroom efficiency with a bed, sitting area, stove, kitchenette. There’s a landing between and then across is the bathroom area with a full shower, toilet, and double vanity,” he explains. “Then there’s a spiral staircase to the rooftop fire pit and lounge area.”

And while there is a lift for things like suitcases and packages, people need to walk up 82 steel-grated stairs, which Fitts admits can be a bit daunting.

“I was actually nervous going up the tower for the first time because it’s high and it is an experience. But once I did it, I said, ‘This is what real mountain experiences are like. This is something that people remember for the rest of their lives.'”

Once up there, the view is everything.

To read the listing with an aerial view and 68 photos, Click Here

My comments: No going up and down the stairs for me! Good exercise though…

—————————————————————–

The Fee Question You Should Stop Asking Other Appraisers

By Dustin Harris

Go into any appraiser group on Facebook right now and scroll for about ninety seconds. You will find some version of this question:

“Are you raising your fees for 3.6?”

It is a fair thing to wonder. The new report takes longer, and every appraiser in the country is doing the same math in their head. The question feels natural. It feels like colleagues comparing notes.

It is the wrong question. And depending on where you ask it, it may be an illegal one.

Here is the part that should get your attention. You do not have to reach an agreement. A discussion about pricing among competitors can itself be treated as an invitation to fix prices. It is a problem even if nobody agrees to anything, even if the number discussed is perfectly reasonable, and even if not one person in the thread ever changes a fee. Violations can carry both criminal and civil exposure, and a private plaintiff who wins one of these can recover three times their damages plus attorney’s fees.

Now let me get to why it is the wrong question even setting the law entirely aside.

When you ask a room full of appraisers whether they are raising fees, you are outsourcing the most important number in your business to a poll of people whose businesses you know nothing about. You do not know their overhead. You do not know their market, their turn times, their software, whether they have a trainee, whether they own their office or rent it, or how fast they personally work.

To read more, Click Here

My comments: When I started my appraisal business in 1986 there was no Internet, but I went to appraisal dinner meetings twice a month. I was warned that discussing fees during the meetings was illegal.

Another appraisal problem was classifying appraisal trainees as independent contractors. Mine were always employees. In the mid-1980s several large appraisal companies locallu were audited by the State labor regulators. Their trainees could not be employees legally. They had big fines.

———————————————————————-

Are you getting too many ad-only emails?

3 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday Posted by noon Friday

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page. NOTE: the popular ads with liability tips are below the first topic on my blog posts.

3. Link to the 10 most recent newsletters from newsletterS posted to my blog www.appraisaltoday.com. Scroll down past the big yellow signup block. The newsletters have abbreviated titles, taken from their blog posts.

To read more about the 3 ways, plus information on why I take ads, etc.

Click here

———————————————-

2026 E and O Update – Claims, Payment Options, Lawsuits, Etc

By Claudia Gaglione, Esq. & Magda Pretorius, Risk and Claims Analyst with LIA Administrators & Insurance Services (LIA)

In the October issue of Appraisal Today

Excerpts:

Artificial Intelligence

A hot topic in the appraisal community is how to integrate the use of AI into

the profession / their day to day business operation.

When working with AI to produce a report, appraisers have to be mindful of

their obligation under USPAP to produce a report that is credible and in no way misleading. They must always review, edit, and take full responsibility for the content of the reports they produce. They cannot simply rely upon AI generated material without ensuring its accuracy. That means double checking and verifying everything they possibly can.

We counsel insureds to take classes to listen to as many viewpoints as

possible. In the meantime, make sure that if your report contains any AI generated content that the workfile shows how and to what extent you took steps to verify that content; public records, calls to real estate agents, whatever it takes.

Appraisers with supervisory authority must also implement reasonable

policies, training, and oversight to ensure that any use of generative AI by trainees does not compromise client confidentiality or replace appropriate analysis or quality control.

There are no AI related claims in our program at this time.

UAD 3.6

The most common concern expressed by our insureds are where/how do

they include the additional language they have traditionally added in the

supplemental addendum of the appraisal report.

It is important that appraisers continue to add this language in their reports,

we suggest that they add the language in the report where/when

relevant.

We don’t have more knowledge than they have about the software and we

are getting to know the software/forms at the same time they are.

To read more about E&O, with many topics in this issue, plus 2+ years of previous issues, subscribe to the paid Appraisal Today at ww.appraisaltoday.com/order .

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason! You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

What’s the difference between the Appraisal Today free Weekly email newsletter and the paid Monthly newsletter? Click here for more info.

———————————————-

If you are a paid subscriber and did not receive the November issue emailed on November 2, 2026, please email info@appraisaltoday.com, and we will send it to you. You can also hit the reply button. Be sure to include a comment requesting it.

————————————————————–

Please hit the reply button if you have any comments or info on any topics. I’m always looking for something new ;>

———————————————-

Class Valuation Faces Class-Action Suit Over Appraiser Payments

By Frank Andorka, Managing Editor, WorkingRE

Excerpts: Class Valuation, one of the largest appraisal management companies (AMCs) in the United States, is the latest AMC to be sued over the issue of appraisal fees and fee transparency.

Clayton Bernholtz, a Florida resident, filed a class-action lawsuit June 11, 2026, in Broward County Circuit Court against Class Valuation and CrossCountry Mortgage, alleging the companies overcharge consumers for home appraisals through undisclosed fees, in violation of the Florida Deceptive and Unfair Trade Practices Act (FDUTPA).

Bernholtz also accuses Class Valuation of unjust enrichment, alleging the company pockets the difference between what it charges consumers and what it actually pays appraisers. He is asking the court to certify the case as a class action on behalf of himself and all others similarly situated, which would allow other affected borrowers to join the suit.

Originally filed in Broward County, Florida, the case was later removed to the U.S. District Court for the Southern District of Florida (Case No. 0:26-cv-61978).

Many appraisers had hoped this issue would be resolved without litigation by the Consumer Financial Protection Bureau (CFPB), which had been expected to issue guidance before the new administration took over. In its current weakened state, it is unlikely such guidance will be coming, which leaves plaintiffs with no alternative (Editor’s Note: until the recent national elections see below.) The focus should be on consumer appraisal fees, not appraisal fees.

Essentially, Bernholtz’s allegations echo the core arguments of the other class-action lawsuits facing AMCs and lenders in this space — CrossCountry Mortgage breached its contract with him, he claims, while Class Valuation, as an appraisal management company, engaged in “unlawful, unfair and deceptive practices relating to the ‘appraisal fees’ they charge mortgage borrowers.”

To read more, Click Here

My comments: With the recent national elections, the CFPB may become more prominent to handle excess fees paid by borrowers. Not many people care about appraisal fees, but borrowers care – a much larger group than appraisers.

——————————————————————–
AMCs – Locked Behind a Digital Iron Curtain

By Desiree Mehbod

Excerpts: Imagine waking up to find your livelihood locked behind a digital iron curtain. That is exactly what happened to an entire panel of appraisers who logged in last week only to find themselves trapped. There were no warnings and no choices.

The Appraisal Management Company held their active assignments and their income hostage behind a mandatory checkbox. Agree to the new terms, or you do not get to work. The kicker is that this company proudly calls these people their appraiser partners, which makes you wonder what they do to their enemies.

The nightmare deepens once you look at what those terms actually demand. The AMC gave themselves full permission to harvest the intellectual property inside every completed appraisal report. They are taking the localized knowledge, the expertise, and the hard work of human professionals and feeding it directly into the maw of their artificial intelligence models. It is a corporate horror story where the machine strips the minds of the appraisers it is actively trying to replace, forcing them to build their own digital executioner for free.

To read more, Click Here

My comments: I recently attended a webinar demo of one of the new UAD 3.6 software vendors. They said they did not take appraisers data.

===================================

MY UAD 3.6 UPDATE

Appraisers are complaining about fees, which seem to vary widely. UAD 2.6 and UAD 3.6. Before AMCs took over around 1980, fees did not vary much over time or among lenders or mortgage brokers. Today’s AMC fee issues is the most significant fee problem that has ever occurred that I know of.

Continuing updates for UAD 3.6 software vendors. A Big Problem. Also, some vendors do not have a functioning, usable inspection app for appraisers who want to significantly decrease the time writing appraisals.

Where to see what appraisers are saying about UAD 3.6 software vendors.

No whining or off topics allowed. My favorite place to keep track of the software mess. Lots of Total posts is:

Most Excellent Facebook Page:

Appraisers Perspective of UAD 3.6

——————————————————————-

HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, Click Here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down. UAD 3.6 few orders. Many appraisers are not busy. Some are busy, usually with non-lender appraisals.

Mortgage applications decreased 1.2 percent from one week earlier

WASHINGTON, D.C. (November 4, 2026) — Mortgage applications decreased 1.2 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 30, 2026.

The Market Composite Index, a measure of mortgage loan application volume, decreased 1.2 percent on a seasonally adjusted basis from one week earlier.  On an unadjusted basis, the Index decreased 2 percent compared with the previous week.  The Refinance Index increased 0.1 percent from the previous week and was 60 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 2 percent from one week earlier. The unadjusted Purchase Index decreased 4 percent compared with the previous week and was 19 percent lower than the same week one year ago.

“Mortgage rates drifted down to their lowest level since September 2026 last week in the wake of the Federal Reserve’s decision to hold on additional rate hikes at its October meeting,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “While the 30-year rate declined to 7.3 percent, activity is still quite slow, with purchase application volume down for the week and refinance volume effectively flat at a very low level. As we have highlighted in recent weeks, more borrowers are choosing ARMs in this environment to lower their initial payments, with the ARM share at its highest level since September 2025.”

The refinance share of mortgage activity increased to 39.8 percent of total applications from 38.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.4 percent of total applications.

The FHA share of total applications decreased to 16.0 percent from 16.6 percent the week prior. The VA share of total applications increased to 11.2 percent from 11.0 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.5 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.30 percent from 7.37 percent, with points decreasing to 0.75 from 0.76 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.20 percent from 7.28 percent, with points decreasing to 0.48 from 0.64 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.02 percent from 7.12 percent, with points remaining unchanged at 1.07 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 6.76 percent from 6.70 percent, with points increasing to 0.98 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.29 percent from 6.41 percent, with points decreasing to 1.00 from 1.20 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

——————————————-

Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
Paired Sales Analysis

Newz: Paired Sales Analysis, The Last Appraiser,
24 Hour Turn Times?

September 12, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Why do Claims get Settled?
  • Paired Sales Analysis: Tips and Tools for Appraisers
  • Home on rare stretch of California’s Lost Coast hits market for $11M in Ferndale, CA Some Assembly Required
  • Combining Tools for Appraisals By Brent Bowen
  • The 24-Hour Appraisal Diet: Slim on Time, Light on Credibility
  • A Review of MEIN COMP: The Last Appraiser by Desiree Mehbod
  • Mortgage applications decreased 1.2 percent from one week earlier

—————————————————————–

Tools To Support Appraisal Adjustments

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

———————————————————————

Paired Sales Analysis: Tips and Tools for Appraisers

By Kevin Hecht

Excerpts: As a professional real estate appraiser, you know that paired sales analysis is a reliable and popular method for determining the value of specific property features and providing market-based evidence to support appraisal adjustments.

Though not without challenges, paired sales analysis is a valuable technique to have in your appraisal toolkit. Mastering this method will help you develop more accurate, credible, and defensible appraisals.

Uses

Primarily used in the sales comparison approach, paired sales analysis is particularly useful for estimating the value of unique property attributes such as:

  • Location advantages (corner lots, cul-de-sac positions, or waterfront access)
  • Scenic views or privacy features
  • Property upgrades (pools, finished basements, luxury kitchens)

Importance

For property appraisers, paired sales analysis is an essential tool because it helps ensure that appraisal adjustments are supported by quantitative data. Rather than relying on cost estimates or subjective opinions, you can use actual sales data to support your value conclusions. This evidence strengthens your appraisal’s defensibility and helps you comply with USPAP.

Additional Topics

  • Step-by-Step Methodology of a Paired Sales Analysis
  • Paired Sales Analysis Tips and Best Practices

My comments: Paired sales has been used for decades by appraisers. Now, statistical analysis including graphs is available plus software that can determine adjustments. In the 8/25 issue of this newsletter, an appraiser survey of appraisal adjustments said that paired sales was the number one adjustment method used by appraisers.

I use paired sales for unusual adjustments, such as discussed above. For example, for many years I lived in waterfront homes, which is not unusual in my city. One of my homes was in a small development of similar homes built in the 1940s. Matched paired sales was very easy. Another non tract home built in the 1940s did not have similar homes nearby and paired sales did not work very well there.

To read more, Click Here

Read more!! →

Appraisal Regulator Chaos

Newz: Appraisal Regulator Chaos , Cat and Raccoon Damages, Wildfire Risks

September 5, 2025

What’s in This Newsletter (In Order, Scroll Down)
NOTE: Scroll down to see Appraisal Regulator Chaos

  • LIA AD: Legal Request for Old Appraisal
  • The Kitty Litter Duplex: An Appraisal I Wish to Not Remember
  • $300K Maryland Home Is Overrun by Feral Cats and Raccoons
  • The Full Measure August 2025: Navigating Rates, Inventory, and Affordability
  • Appraisal Regulatory Chaos
  • The Town With No Bank: How Rural America Lost Its Mortgage Lifeline By Dallas T. Kiedrowski, MNAA
  • New Cotality Wildfire Risk Report finds more than 2.6 million homes are exposed to moderate or greater wildfire risk
  • Mortgage applications decreased 1.2 percent from one week earlier
    —————————————————————

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

————————————————-

———————————————————–

The Kitty Litter Duplex: An Appraisal I Wish to Not Remember

Excerpts: How one property’s furballs left an unforgettable impression on an apartment and an appraiser

Introduction

In the world of real estate, surprises abound. Industry professionals, especially appraisers, all expect the unexpected, but even the most seasoned professionals can stumble across situations that test the limits of their experience, composure, and their judgement. There are stories of haunted houses, collapsing ceilings, and outlandish tenant actions and decorative choices (Live, Laugh, Love), but the tale of the cat-soiled duplex stands out for its sheer yuck-factor. This is the story of what should be a routine property appraisal, which became cemented in my experience stories, due to its unfathomability and coated in an unmistakable, noxious layer of feline mischief.

The Setting: An Unimposing Duplex with a Dirty Little Secret…

The Appraisal Appointment: An Unforgettable First Impression

…I could only see the flooring in the opening and a few other spots around the living room from about a foot outside the threshold, the rest of the floor was completely caked with cat poop. The walls, ceiling, and windows were all enveloped by heavy spider webs in a variety of states, while some were fresh looking, others clearly blackened from a long life filled with dust, dirt, fur, and of course fecal matter. Also, you could see multiple patches of orange mold scattered throughout the walls and ceiling. I quickly replied I would not be going in there, because it was a danger to my health and safety, which somehow surprised her….

Financial and Health Implications: When Cleanliness Becomes a Value Killer

Hygiene, general maintenance, and property values parallel each other. This may be why we have condition codes for our appraisals. Just saying…. I made sure to thoroughly explain the situation and how the value was determined in the report. I did not want this rolling back downhill and getting me. Luckily, a very gracious Fresno Construction, was able to give me a quote very quickly, which came just over $100,000 for an estimate to redo the unit in its entirety.

Conclusion

The Kitty Litter Unit stands as a testament to both the resilience of a property and the unpredictability investors face. Especially in this case, since it was for an estate of a deceased former owner.

To read more, Click Here

My comments: I appraised a house for a relocation company – one story with 3 bedrooms. There were cats on every surface above the floor, such as dressers, – all staring at me of course. In the rear of the home was a very large cat enclosure. They were rescue cats, temporarily at the home. I did not ask the owner where the cats would go when she relocated – back to the shelter or with go with her.  I will never forget about all those cat eyes staring at me!

I had another relocation appraisal where the male cat had sprayed urine along several walls in the living room. I told the relocation company to replace the drywall.

Of course, I could fill up a book with dog stories. Such as two Dobermans that broke down the door of a trailer to get to me. I somehow made it to my car and I will never forget it. Or the small dogs who bit my ankles as I was trying to get through the front door (home was owned by an appraiser I knew). For both appraisals, I told my lender client to get another appraiser.

Read more!! →

Appraisal Adjustments

Newz: Appraisal Adjustments, How Freddie and Fannie Inflated Home Prices, FHA to Adopt UAD 3.6

August 29, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD Navigating Value Revisions in Appraisals
  • Appraisal Adjustments: Types, Methods, and Cheat Sheet Appraisal By Kevin Hecht
  • Inside Artificial Heart Inventor’s $4.8 Million Midcentury Modern Salt Lake City Utah Home
  • Inflated Prices, Taxed to Death, by Jeremy Bagott
  • Can the direction a home faces affect its value? By Ryan Lundquist
  • The Competence to Perform an Assignment, by Timothy C. Andersen, MAI
  • FHA to adopt UAD 3.6
  • MBA: Mortgage applications decreased 0.5 percent from one week earlier

————————————————-

Time Adjustment Changes for Appraisers

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

———————————–

————————————————-

Appraisal Adjustments: Types, Methods, and Cheat Sheet Appraisal By Kevin Hecht

Excerpts:

Types of Appraisal Adjustments

Appraisal adjustments can take several forms, depending on the property characteristics being compared. Each type of adjustment addresses a different element that may influence value. Below are descriptions of common adjustment categories and their uses, followed by a “cheat sheet” chart with examples.

  • Qualitative Adjustments
  • Quantitative Adjustments
  • Transactional Adjustments
  • Market Conditions Adjustments
  • Property Adjustments
  • Locational Adjustments

Common Methods for Making Appraisal Adjustments

A long list, from matched paired sales to Cost Analysis

Appraiser Survey: What’s Your Go-To Method for Adjustments?

Paired sales/matched pair analysis (Most popular answer!)

“I typically cover rural areas where sales are scarce and there is not enough data for meaningful statistical analysis to be performed. Due to this, paired sales analysis is the most reasonable and defensible analysis position available.”

“I use linear regression to understand market changes and to calculate any necessary market change adjustments.”

“Depends on what item is being adjusted. If it is site or GLA, it is usually a percentage of the per acre or per square foot sales price. Other items are usually paired sales analysis or consideration for depreciated cost.”

To read more, Click Here

My comments: Comprehensive lists and interesting appraiser comments. I quit doing grid dollar adjustments many years ago. A person from our state regulator, speaking at a local appraisal meeting, said they would require support for all adjustments. I started by doing Plus and Minus grid adjustments and then went to “total property comparison” with a value. I do a qualitative analysis comparing the comps.

The only supported dollar adjustments I make are for market conditions and high dollar features such as a fantastic view of the Golden Gate Bridge from very high up a hill.


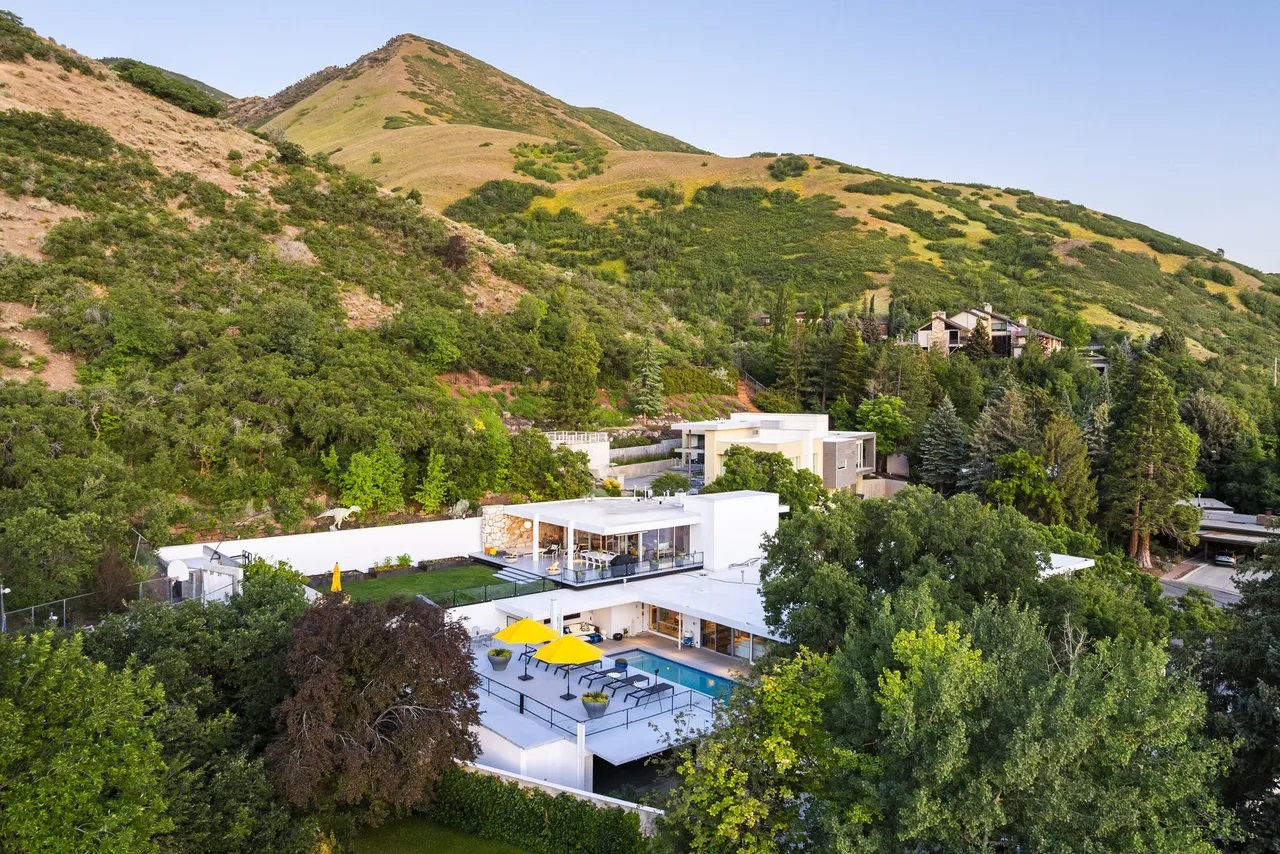
Inside Artificial Heart Inventor’s $4.8 Million Midcentury Modern Salt Lake City Utah Home

Excerpts: 4 bedrooms, 4.5 baths, 5,447 sq.ft., 0.55 acre lot, built in 1957

The mastermind behind the one-of-a-kind estate was none other than Swiss architect Eduard Dreier, who brought Bauhaus principles to the modernist movements of Utah and Nevada.

Lovingly restored and awarded the Utah Heritage Award for Restoration and Renovation, this 5, 447 sq ft architectural gem blends timeless Dreier elements-exposed steel beams, walls of glass and cantilevered roof line, granite rock walls-with warm modern luxury. The 1,110 sq ft glass-and-steel attached guest house, designed by Dreier protge Brent Groesbeck in 2016, floats above the main home, expanding living where entertaining is elevated to an art form.

To read more, Click Here

To see the listing with 43 photos and a video tour, Click Here

Read more!! →

What AI Means For Appraisers

Newz: AI and Appraisers, FHA Handbook Updated,
History of Residential Appraisal Regulations

August 22, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Should I consider this an actual claim?
  • 7.5 Things Appraisers Can Do That Artificial Intelligence Cannot, By Mark Buhler
  • Home Made Entirely Out of Shipping Containers Hits the Market for $5.2 Million in New Hampshire
  • FHA Handbook Updated
  • The New Appraisal Report: How One Company Is Rethinking Appraisal Software
  • A Primer on Regulations and the Practice of Residential Property Appraisal
  • Mortgage applications decreased 1.4 percent from one week earlier

AI and Appraisals – the Future

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

———————————–

————————————————-

7.5 Things Appraisers Can Do That Artificial Intelligence Cannot

By Mark Buhler

Excerpts: Artificial intelligence is making waves in nearly every industry — and real estate appraisal is no exception. Computer generated algorithms and valuations promise quick results and lower costs, and some headlines are already asking the question: “Will appraisers be replaced by AI?”

The short answer? Not even close.

What appraisers can do

1. Judge Condition and Quality

An AVM might see a listing that says “4 bedrooms, 3 baths, 2,400 square feet.” What it won’t know is that one of those bedrooms hasn’t been updated since the Nixon administration and still sports avocado-green shag carpet. Appraisers evaluate condition, quality of construction, level of maintenance, and updates — all of which have a direct impact on value. Without physically inspecting a property, AI misses these nuances entirely.

2. Interpret Unique Features

3. Spot Red Flags the Data Misses

4. Smell the House

5. Explain and Defend Adjustments

6. Testify in Court

7. Apply Professional Judgment

7.5 Half Point: Remember to Knock

How to Start Leveraging AI in Your Practice – 7 ways

AI won’t replace appraisers — but appraisers who embrace it will leave others behind. Here are a few easy ways to get started:

1. Use AI‑Driven Comp Tools: Platforms now exist that can quickly identify potential comparables based on similarity scoring. Use them to save time — but always vet the comps yourself.……………

To read more, Click Here

My comments: Worth reading the entire article. What AI can do.

What Appraisers can do, with and without AI.


Read more!! →

Humor What is an appraiser?

What is an Appraiser? Humor, Upzoning,
New UAD Quality Ratings

August 15, 2025

What’s in This Newsletter (In Order, Scroll Down

  • LIA AD: A Family feued and Intended Use
  • Upzoning: What It Is and What Appraisers Need to Know
  • Off-Grid ‘Stilt Home’ That Hovers Above a St. Augustine Beach Hits the Market for $1.35 Million
  • What Is An Appraiser? Humor
  • The New UAD Quality Equation: Interior + Exterior = Overall Rating
  • The Harbor Model: Where Appraisers Take the Helm
  • Mortgage applications increased 3.1 percent from one week earlier,

——————————————————————————-

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

—————————————————————————


Upzoning: What It Is and What Appraisers Need to Know

Excerpts: Upzoning is a powerful but often misunderstood tool in urban planning and real estate. In this post, we’ll break down what upzoning is, why it’s becoming more prevalent, and what appraisers need to know about its potential impact on property values.

What Is Upzoning?

Upzoning is the process of modifying zoning laws to allow for higher-density development in areas that previously had stricter land-use regulations. This might include permitting multi-family housing where only single-family homes were allowed, increasing building height limits, or reducing minimum lot sizes. The goal is often to promote more efficient land use and address housing shortages.

What to Be Aware of as an Appraiser

It’s important for real estate appraisers to stay informed about changes in local zoning laws, as these can significantly affect property valuations. Upzoning, in particular, can alter what is legally permissible on a parcel of land, shifting development potential and land use expectations.

When upzoning occurs, the highest and best use of a property may change—from a single-family home to a multi-family development, for example—requiring appraisers to reassess the property’s value accordingly.

How to Address Upzoning in Your Appraisal Report

If you find that a property has been upzoned, how do you tackle that in your actual appraisal report? “I think the place to start is building permitting,” says Dobbs. “A lot of cities have pretty decent permitting websites. You can go in there and look at what types of permits are being pulled in the area.”

More topics:

  • How to Address Upzoning in Your Appraisal Report
  • Opportunities for Real Estate Appraisers
  • How to Prepare for Future Upzoning

To read more, Click Here

My comments: Excellent, understandable article about this important topic. There are rental housing shortages in many areas in U.S. Today there is pressure to allow upzoning to make more rental housing available.

Residential appraisers did not receive much education on this topic. You don’t want to get into trouble with the state board by using the incorrect highest and best use on a property or not recognizing and reporting on upzoning.

I do commercial appraisals. HBU issues occur regularly in my city, so I keep up on zoning changes.

Don’t forget local regulations. In my city, regulations (not in zoning regs) restricts the number of rental units on a property (downzoning) after many Victorians were demolished and ugly modern apartment buildings constructed in the early 1960s. Appraisers only looking at zoning for HBU would make a very big mistake.

—————————————————————————————-

Off-Grid ‘Stilt Home’ That Hovers Above a St. Augustine Beach Hits the Market for $1.35 Million

Excerpts 4 bedroom 3 baths,3,374 square feet, 0.41acre lot, built in 1980

Beachfront homes that offer instant access to white sand and a crystal-clear ocean are a rare find—but even rarer is a dwelling that sits directly atop that beachfront, mere feet away from the water.

Yet one such property has just washed ashore in St. Augustine, FL, listed for $1.35 million, 19 years after it last changed hands for less than a sixth of that price.

This unique dwelling is situated on large wooden stilts that have been hammered into the sand, providing the perfect perch overlooking the water, ensuring 24/7 beach access—a rare amenity that comes with its fair share of complications.

Unsurprisingly, given its location, the home is classified as being at “extreme” risk of flooding, according to the Realtor.com® Flood Factor rating, which notes that the dwelling has a “100% risk of flooding” over the next 30 years.

Additionally, the “stilt house” has an extreme wind factor rating, as well as an extreme risk of hotter-than-average temperatures.

To read more Click Here

To read the listing with 59 photos and a video tour, Click Here

————————————————————————-

What Is An Appraiser? Humor

An appraiser is one who compiles and analyzes voluminous data of problematical accuracy from sources of dubious veracity and derives therefrom a numerical quantification of unquestionable necessity,

analogous to a nebulous and euphemistic concept representational of value commensurate with ambient configurations of the open market

and promulgates thereby a precise written declamation which delineates his observation, deliberations and conclusions all done while he feigns absolute ignorance of the avaricious machinations of Buyers, Sellers, Brokers and Lenders, compensated only by that penurious stipend known as the professional fee.

This joke is from Bill Sparks. Bill doesn’t know where this joke originated, but Thanks for sending it to us!

My comments: We all need a little appraiser humor!

Read more!! →

12 APPRAISAL MYTHS

Newz: 12 Appraisal Myths, Appraisal Bias Lawsuit

August 8, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Legal Request for Old Appraisal
  • 12 Common Appraisal Myths/Misconceptions by Tom Horn
  • $750K Hobbit-Style Bunker in Tennessee Puts a Unique Spin on Underground Living
  • The Appraiser’s Market Compass: Navigating the Summer 2025 Housing Landscape By Kevin Hecht, Appraiser and Economist
  • Appraiser questions answered: Interview with Craig Capilla, Attorney
  • No, Appraisers Didn’t Cause America’s Racial Wealth Gap by Jeremy Bagott
  • Mortgage applications increased 3.1 percent from one week earlier

————————————————

————————————————–

12 Common Appraisal Myths/Misconceptions

By Tom Horn

Excerpts:

1. Appraisers Rely Primarily on Price Per Square Foot

This is probably the most common misunderstanding I run into.

Yes, price per square foot is one of many tools we use to analyze value—but it’s not the whole story.

2. Appraisals Are Just a Quick Comparison of Recent Sales

Some folks think appraisers pull the three most recent sales and call it a day.

In reality, it’s much more involved. We look at a wide range of comparable sales, analyze market trends, make adjustments for differences between properties, and apply professional judgment.

3. Appraisals and Home Inspections Are the Same

This is a big one for homeowners and buyers.

Home inspections focus on the condition and function of the property—things like the roof, HVAC, plumbing, and safety issues. The inspector is looking for problems.

Appraisals, on the other hand, are focused on value. We observe the overall condition, yes, but we don’t test systems or check for code compliance.

4. Automated Valuation Models (AVMs) Like Zillow Zestimates Are Equivalent to Appraisals

Zillow can be helpful for a ballpark estimate, but it’s not an appraisal.

AVMs use algorithms, public data, and sometimes outdated or incorrect info. They don’t know if your kitchen was remodeled last year or if the neighbor’s home was a distressed sale.

5. The Purpose of the Appraisal Changes the Value

This one trips people up sometimes.

They’ll ask, “What’s the value for a refinance?” or “How much is it worth for a divorce?” as if the answer changes depending on why we’re appraising it.

To read the details and all 12 reasons, Click Here

My comments: Read this blog post. It can help you keep out of hassles and problems when appraising. When you get asked these questions you will know how to respond.  Written for real estate agents, buyers, sellers and many other people but excellent tips for appraisers.

————————————————————————————–

$750K Hobbit-Style Bunker in Tennessee Puts a Unique Spin on Underground Living

Excerpts: 3 bedrooms, 3 baths, 3,024 sq.ft., built in 2010, 38.84 acre lot

When you think of a bunker, you probably don’t imagine a three-bedroom abode that’s brimming with modernity—which is just one of the reasons that a newly listed dwelling in Tennessee comes as a surprise.

Tucked into the hillside like a doomsday bunker, this Bethel Springs residence was originally built in 2010, yet it boasts a historic Hobbit-style feel akin to the quaint homes depicted in J.R.R. Tolkien’s picturesque Shire.

But much like Tolkien’s books, this home should not be judged by its cover.

Despite its bunker-esque setting and Hobbit-inspired exterior, inside the dwelling is a modern marvel, having been thoughtfully remodeled by its current owners to include an open floor plan and design-forward finishes like granite countertops and luxury vinyl plank flooring.

To read more plus photos, Click Here

To read the listing with 50 photos, Click Here

Read more!! →

AI and Appraisals – the Future

Newz: Future of AI in Appraisals,
Comps in Today’s Market

August 1, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA ad: Code violations and expertise
  • The Future of AI in Real Estate Valuations: Understanding Tomorrow’s Appraisal Standards By Leland Trice
  • New York City’s Famous ‘Bubble House’ Hits the Market for the First Time in 50 Years With an Asking Price of $5.8 Million
  • The problem with comps in today’s housing market By Ryan Lundquist
  • Divorce Appraisal: A Guide for Real Estate Appraisers By Kevin Hecht
  • For sale signs multiply: Inventory hits 5-year high, price cuts surge What’s happening with markets all over the country?
  • Mortgage applications increased 0.8 percent from one week earlier

———————————————————————–

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

—————————————————————–


The Future of AI in Real Estate Valuations: Understanding Tomorrow’s Appraisal Standards

By Leland Trice

Excerpts: The real estate valuation industry stands at a pivotal moment. After decades of relying on manual processes that are inefficient, error-prone, and costly, we’re witnessing a fundamental shift toward AI and technology enabled solutions that don’t replace human expertise but amplify them.

The future of real estate valuations will likely involve increasing integration of human expertise with artificial intelligence capabilities. This evolution isn’t about replacing professional judgment with automated systems it’s about creating hybrid approaches that leverage the strengths of both human analysis and machine processing.

Opteon’s new AI-powered quality control tool, built in collaboration with technology partner Jaro, illustrates this broader evolution across our industry.

It’s important to clarify a common misconception: AI-powered tools like Intara, don’t replace appraisers or QC functions. Instead, they enable Appraisers to focus on what they do best, expert analysis and decision-making, while automating repetitive, administrative and time-consuming tasks that add little analytical value.

The “magic” of AI is its ability to look holistically at a file. We have moved past the days of checklist data review and can now examine unstructured data and images simultaneously and in conjunction with discrete data points.

A critical factor in successful AI implementation is the flexibility to meet varying requirements. Intara demonstrates this principle by embedding lender-specific criteria into quality control processes, automatically identifying discrepancies, and ensuring consistency before reports reach final review.

To read more, Click Here

My comments: This article sometimes reads as a “marketing promotion”. But, worth reading to see how one company uses AI for appraisals and how it is used.

This article goes way beyond Chat GPT. It shows how custom AI applications can work for appraisals. The author, Leland Trice, is Managing Director at Opteon USA.


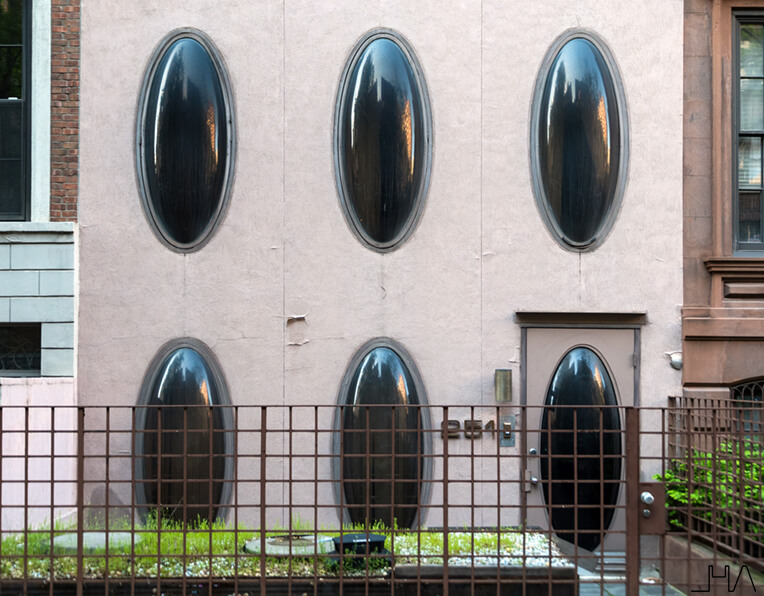
New York City’s Famous ‘Bubble House’ Hits the Market for the First Time in 50 Years With an Asking Price of $5.8 Million

Excerpts: 4 bedrooms, 5 baths, 4,763 sq.t. Townhouse

The distinctive bubbly residence has become a somewhat divisive hot spot in its Lenox Hill neighborhood, where it was built in 1969, with architect Maurice Medcalfe transforming a traditional brownstone into the eye-popping modernist masterpiece.

Medcalfe’s unique window design was intended to be “a sculptural interpretation of the classic bay window,” according to reports.

There is plenty to play with in the four-story interior, which boasts 4,736 square feet of space and includes four bedrooms, an office, and five bathrooms that are “all in need of renovation,” according to the listing.

To read the listing with 13 photos