AMCs: Survey, How Tech Sabotages Appraisers

Newz: Appraiser AMC Survey, AMCs: How Tech Quietly Sabotages Appraisers

November 6, 2026

ARTICLE LIST – In order, Scroll down to read

  • LIA AD: Read The Fine Print
  • Independent Appraiser Voices plus Survey: More in Common Than We Think
  • Inside a Marvel Showrunner’s $2.4 Million Topanga California Compound Featuring a 1970s Geodesic Dome and Private Oak Grove
  • Helping Appraisers Get Paid for What They’ve BuiltBy Isaac Peck, Publisher, WorkingRE
  • My Ad: Major Changes in Fannie Mae’s HBU Property Eligibility Requirements (Effective With UAD 3.6), By Denis Desaix, MAI, SRA
  • Countdown in Chicago: UAD 3.6, AI, and Rates Going Up? MBA 2026 Recap, By Jim Morrison
  • The Full Measure: October 2026 Housing Market Update, By Kevin Hecht, Appraiser and Economist
  • The Ghost in the Machine: How Tech Quietly Sabotages Appraisers, By Desiree Mehbod
  • Appraisers face stagnant pay and rising costs as AMCs defend their fees and new technology reshapes the industry
  • Mortgage Applications Decrease 1.2 Percent in Latest MBA Weekly Survey

Thanks to our Sponsor!!!

Very reasonable prices and good open rates!
———————————————————————–

Independent Appraiser Voices: More in Common Than We Think and and AMC Appraiser Survey

Independent Appraiser Voices is breaking the silence on unfair AMC fees and UAD 3.6 struggles to prove that while we may work independently, we don’t have to face these industry battles alone.

Excerpts: Independent Appraiser Voices is breaking the silence on unfair AMC fees and UAD 3.6 struggles to prove that while we may work independently, we don’t have to face these industry battles alone.

If you’ve been an independent appraiser for any length of time, you’ve probably asked yourself, more than once, “How much more am I expected to take on without being compensated for it?”

Between rising business expenses, increasingly complex assignments, unrealistic deadlines, and AMC fees that often seem disconnected from the work involved, there’s plenty to be frustrated about.

And now we have UAD 3.6. We can probably all agree that the UAD 2.6 forms were due for an update, but is this really the improvement we needed?

We know these frustrations because we’re dealing with them, too. And they’re exactly what inspired Independent Appraiser Voices (IAV). BookAppraisals

IAV is a brand-new, independent grassroots initiative created by working appraisers who believe it’s time to do more than vent about these problems individually. We’re boots-on-the-ground appraisers, just like you, trying to make a living while navigating the same challenges.

There are already people around the country advocating for change in our profession, and we share those goals. We want to bring independent appraisers together, identify the concerns we have in common, and turn our shared experiences into a stronger, more unified voice.

Our first step is the 2026 Independent Appraiser Survey: UAD 3.6, AMC Fees & Industry Concerns.

The survey is anonymous and covers compensation, UAD 3.6, AMC practices, unpaid time, and other industry concerns. There’s no membership, no fee, and nothing being sold. We simply want to hear directly from appraisers across the country.

The survey is anonymous and covers compensation, UAD 3.6, AMC practices, unpaid time, and other industry concerns. There’s no membership, no fee, and nothing being sold. We simply want to hear directly from appraisers across the country.

Our intention is to use the findings to document common concerns, support advocacy for meaningful change, and encourage greater cooperation among independent appraisers. We’ll share the results with the appraisal community and be transparent about what the data does and doesn’t tell us.

To read more, Click Here

To take the survey, Click the link in the article.

My comments: The survey seems like a good idea. I always like to read the survey results. I have never worked for an AMC so did not take the survey.
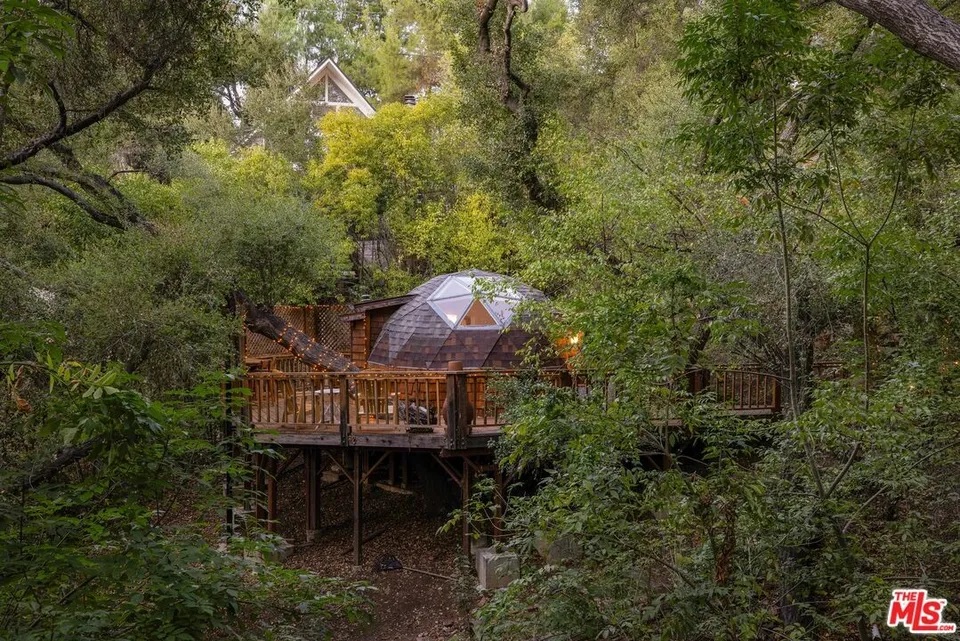

Inside a Marvel Showrunner’s $2.4 Million Topanga California Compound Featuring a 1970s Geodesic Dome and Private Oak Grove

Excerpts: 4 bedrooms, 4 baths, 1,547 sq.ft., 0.76 acre lot, Built in 1935

Built in 1935, the “thoughtfully cared for” 1,547-square-foot sanctuary boasts stone pathways, footbridges, and a seasonal creek. It is located in the Post Office Tract near Topanga State Park.

“What makes this property so special is its setting within a private oak grove,” says listing agent Nina Kurtz of Compass. “It genuinely feels like having your own private park.”

That private-park feel extends across the compound, which includes a two-bedroom primary residence and additional living space.

According to public records, the four-bedroom property is currently owned by Hollywood writer and producer Andrew Guest, co-creator, showrunner, and executive producer of Marvel’s “Wonder Man.” Guest purchased the property for $2.75 million in 2022.

Expansive windows were designed to frame the lushly landscaped lot and bring the outdoors into the living spaces.

To see the listing with an aerial view and 54 photos, Click Here

My comment: I would love to live in a private Oak Grove fully landscaped with a seasonal creek, house, and a Geodesic Dome. Before the Gold Rush from 1848 to 1855 my city was full of oak trees. Over time, most were torn down and Alameda became a suburb of San Francisco, 10 miles away with access via ferry boats.

I often think of the original native inhabitants, the Ohlone, who traveled to Alameda for oak tree acorns and access to San Francisco Bay with fish and shellfish.

Our pickleball courts are in a park and used to have a large oak tree that offered shade when it was hot. A large branch broke off and fell on part of our courts. We miss the large oak branch with the shade it provided. Large umbrellas are not the sameI

————————————————————-

Helping Appraisers Get Paid for What They’ve Built

by Isaac Peck, Publisher, WorkingRE

Excerpts: Most appraisal shops are one-person operations. The specter of the lone appraiser running their business in a spare bedroom and not socializing much with their peers has persisted for decades — and there’s certainly some truth to it.

However, one of the downsides to a solo-operator business model, especially with service businesses like appraisal, is that when it comes time to retire, these types of businesses are rarely saleable. With no (or few) assets, no staff and little goodwill outside of the name of the principal, most solo appraisers build their businesses for decades and then simply flip the light switch and shut the door on their business.

Bryan Reynolds wants to change all that.

A certified general appraiser, partner at Appraiser eLearning, host of The Appraisal Update Podcast, owner of Reynolds and Associates, and a partner at his two newest ventures — Legacy Appraisal and Consulting and Legacy Advisors and Consulting — Reynolds is a serial entrepreneur.

His latest ventures are particularly interesting and arguably well-timed, given everything the profession is facing.

Entering and Exiting the Profession

Reynolds sees real opportunity in simultaneously helping folks enter the profession, as well as working with appraisers who are about to step back and retire.

“Our vision is to help appraisers enter the profession and exit the profession,” Reynolds says. “What do most appraisers do when they’re ready to retire is they turn their light off and close the door. Their book of business, which in many cases represents 30 to 40 years of careful nurturing, just evaporates. They don’t get paid for it or rewarded in any way. We would like to help keep their legacies alive.”

Instead of just shutting the door, Reynolds explains that Legacy Advisors and Consulting is working with appraisers to set up an exit strategy that allows them to receive compensation for the first three to five years of retirement.

“We will ask them to stay with the company for a prescribed period of time,” Reynolds says. “Then we will put someone in their market, as well as our administrative and support team based out of western Kentucky. Basically, we want to see another appraiser step in and become them in that local market.”

Reynolds’ strategy requires the exiting appraiser to remain with the company for 12 to 18 months. If they want to retire, however, Reynolds requests they call a year in advance. Several interested appraisers have already reached out.

“I just talked to an appraiser who asked me, ‘What about the VA? I’m a VA appraiser. VA selects me to do the appraisal. How can I transition this business?’” Reynolds says. “Our position is that for every problem there is a solution.

Helping Train New Appraisers, Too

Reynolds also wants to help new entrants to the profession find their feet and get started. Legacy Advisors and Consulting is also licensing Melissa Bond’s MPact Practicum coursework, a successful appraiser curriculum.

Appraisers thinking about an exit strategy, and anyone looking at the training pathway, can find more at LegacyAppraisalandConsulting.com and LACappraiserpathway.com, or email info@LACappraiserpathway.com. Reynolds can be reached directly at Bryan@theLegacyAG.com.

To read more, Click Here

My comments: When I have written about selling your appraisal business (or spoken with appraisers), I have always said the best people are those working for you. Selling a one person appraisal business seldom happens. Sometimes if you’re in a vacation location an appraiser may be interested in locating. Or, a competitor may want to purchase it.

I have spoken with buyers and sellers of appraisal businesses. It is not easy for the buyer or the seller, even if you have employees and are well established. Staying over for a transition period is very common.

Selling a Commercial may be easier than residential. Over the years I have seen many larger commercial appraisal companies that expand by buying (or merging with) other local commercial appraisal companies.

Since I have been writing about this, over time several national appraisal firms merged with other commercial appraisal firms.

————————————————————-

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent weekly newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.

To read more about the 4 ways, plus information on why I take ads, etc. Click here

———————————————————

Major Changes in Fannie Mae’s HBU Property Eligibility

Requirements (Effective With UAD 3.6),

By Denis Desaix, MAI ,SRA

In the November 2026 issue of Appraisal Today

Excerpts: In September of 2026, Fannie Mae (FNMA) announced major changes in their property eligibility standards regarding highest and best use (HBU) conclusions reported in the appraisal.

I was asked by Fannie to be a Policy Advisor on this matter and had a preview of the changes that have since been announced. I say this so I can affirm, with credibility, that a lot of thought has gone into the changes and

how they affect not only the appraisal process but the entire 1- to 4-unit residential lending production process.

In this article, I will discuss the new HBU policy and review the examples that Fannie uses to illustrate how the new policy can affect property eligibility which, in turn, can affect how we analyze and report our value opinions in our appraisal reports.

Please note that these changes apply to UAD 3.6 Appraisal Assignments only!!

The impact on lending is easy to describe: Certain properties that were previously ineligible for Fannie purchase are now eligible.

The impact on appraisers is also easy to describe:

To conclude a credible HBU opinion for some properties, a deeper level of analysis will be necessary.

This is not a bad thing for appraisers as the more complex the property, the less likely an alternative valuation tool can be used

To read more about this new UAD 3.6 change, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.

If this article helped you understand this Fannie change, it is worth the subscription price!

—————————————————————-

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

————————————————–

Countdown in Chicago: UAD 3.6, AI, and Rates Going Up? MBA 2026 Recap – October 11-14, 2026

By Jim Morrison

Excerpts: he Mortgage Bankers Association Annual is always one of the best places to find out what is coming for the industry.

This year in Chicago, one topic was on almost every agenda: UAD 3.6. With the mandate only weeks away, lenders, GSEs, AMCs, and technology providers spent the week comparing notes on what is working, what isn’t, and what happens next. Add a market that still hasn’t turned the corner, a lot of conversation about AI, and a former President on the main stage, and it made for a busy few days.

Here are the sessions that matter most for lenders and appraisers. On UAD 3.6, Williamson confirmed November 2nd is still the date, but lenders that need more time can request an exception. About 25,000 UAD 3.6 appraisals have been submitted so far, roughly 10% of October volume.

Readiness Check: A Countdown to UAD 3.6

Low volume has been the biggest readiness gap. Some appraisers have been running test files on their own homes because the orders haven’t come in yet. Downing said appraisers typically see efficiency gains after three to five reports and are back on par with UAD 2.6 after about ten.

Review teams are learning too. Scarpa said his reviewers had never seen a 3.6 report and are training on the software alongside appraisers….

AI came up in almost every room. The largest lenders are leading the investment, and some are building custom models to help with review. Scarpa shared a story from another lender where a loan was nearly closed before they discovered the house was condemned and the photos had been generated by AI. Lenders now need to verify that images haven’t been altered, and appraisers need to protect the integrity of their own work.

To read more, Click Here

My comments: In the past, I went to several of the MBA National conferences as a reporter. I hung out in the reporters room with free lunch and snacks and had dinner with other reporters. It was definitely worthwhile attending as an appraiser to see what the speakers say.

————————————————————-

The Full Measure: October 2026 Housing Market Update

By Kevin Hecht, Appraiser and Economist

The rate is the headline. The spread is the story.

October brought a sharper version of the challenge that has defined the housing market all year: buyers are still interested, but payments are setting a hard limit on what many can buy.

Sales haven’t stopped, and prices haven’t moved in one national direction. Yet higher financing costs are giving buyers more leverage, increasing the importance of concessions, and making sellers and builders work harder to meet the market.

Topics include:

• The Mortgage Rate Is More Than a Treasury Yield

• The Fed Held, but Mortgage Rates Follow a Different Market

• The Economy Is Providing Support, But Not a Free Pass

• Existing Homes: More Choice, More Negotiation

• New Construction Has Its Own Price Signal

• Policy May Help at the Margin, But It Does Not Reset Today’s Market

For appraisers, the headline is not simply that the 30-year mortgage rate remains above 7%. The more useful question is why a mortgage rate can remain elevated even when the 10-year Treasury yield is lower.

The Appraiser’s Assignment

The market rewards an approach that is both current and specific.

• Review the financing terms and concessions, not just the sale price.

• Track whether competing listings are accumulating, expiring, or selling after reductions.

• Separate a price cut from a rate buydown.

• Identify whether new construction is competing directly with the subject or simply sharing the same broad geography.

• The appraiser’s job is not to force a national rate story onto a neighborhood. It is to determine how that neighborhood is responding to the financing environment using the best available evidence as of the effective date.

The national message is clear: the economy still offers support, but mortgage pricing is tightening the market’s filter. The local conclusion will depend on which properties still pass through it.

My comments: READ THIS ARTICLE! This is the only real estate market comments I read every month because it is written by an appraiser/economist for appraisers. You have probably had people (and clients) ask you about the topics above because you are an appraiser.

I took a economics class as preparation for my MBA classes. I had been appraising for 5 years. I was a much better appraiser after taking just the economics class. After I got my MBA I was an even better appraiser.

To read more, Click Here

—————————————————————-
The Ghost in the Machine: How Tech Quietly Sabotages Appraisers

By Desiree Mehbod

The real estate appraisal industry is being quietly rewritten by corporate tech platforms that automate blacklisting and manipulate home values behind the scenes.

Excerpts: For anyone working on the ground in the appraisal industry today, the real estate market does not feel like a fair playing field. It feels like an automated ecosystem designed to squeeze out local expertise in favor of corporate volume. While outsiders look at recent data and express shock, those of us in the trenches know the truth: bias, exploitation, and automated blacklisting are literally hardcoded into the platforms we are forced to use every day. BookAppraisals

To understand how broken things have gotten, you only have to look at what happened to a seasoned independent appraiser out West. After years of building direct relationships with lenders, his entire workflow evaporated into thin air over a matter of days. For six grueling months, his phone stopped ringing, and no new appraisal requests came through. He reached out to a trusted lender he had done business with for years, only to receive a shocking answer: “We have been sending you work orders for months, but you never responded. We thought you were ghosting us, so we removed you from our panel.”

What actually happened was not a lack of interest or an economic downturn. It was deliberate, systemic sabotage.

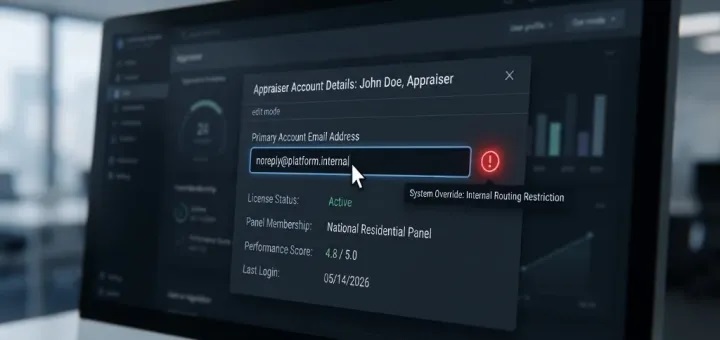
The appraiser had grown tired of receiving a nonstop, daily barrage of automated AMC bid spam flooding his inbox. When he pushed back against the platform handling the communications, an employee at the appraisal tech platform retaliated by quietly changing his account’s primary email contact to an internal “noreply” address. Because the system never sent out a bounced notification, lenders genuinely believed he was ignoring them. A single unlicensed tech employee effectively deactivated a small business with a few clicks, and it took a random, autopopulated form months later for the appraiser to discover the truth.

This is not just a horror story about bad tech support. It is a window into the unchecked power that tech platforms and Appraisal Management Companies (AMCs) hold over our livelihoods.

The software running this industry is built to control and discipline independent appraisers. Take the concept of appraiser grading metrics.

Appraisers are under the illusion that their performance ratings are private between them and an individual client. In reality, bad star ratings or panel removals from a single vindictive AMC are secretly shared across wider platform networks, like Mercury via the VMP suite. It creates a permanent, hidden anchor that ruins future work opportunities with other clients, with no shelf life expiration date and zero opportunity for a fair rebuttal.

This infrastructure directly explains the numbers people are starting to notice. A recent National Mortgage Professional article highlighted a stat showing that AMC appraisals are more likely to match a home’s contract price exactly, hitting it at 26.41% compared to 22.67% for non-AMC appraisals. To a data scientist, that might look like a statistical anomaly. To an independent appraiser, it is just Tuesday. See below for more information on the National Mortgage Professional Article see below.

To read more of the article above and read the appraiser comments,

Click Here.

My comments: I remember when AMCs took over appraisal management after the 2008 housing crash. A hot appraisal topic was how to be taken off the AMCs “do not use list”. Before AMCS took over lenders managed their own appraisal lists, often for overflow from their staff appraisers. Reportedly they shared their l “Do not Use” lists.

===========================================================

Appraisers face stagnant pay and rising costs as AMCs defend their fees and new technology reshapes the industry

From National Mortgage News

TOPICS:

  • Where The Appraisal Fee Goes
  • How AMCs Became The Status Quo
  • The Bidding Process
  • A New Appraisal Format, An Old Fight Over Fees
  • Who Manages The Work?
  • Outsourcing The Work Doesn’t Outsource the Responsibility
  • What Does The Research Say About Quality?

A few quotes:

“Appraisal management companies — although they’ve been around for many, many years — have morphed into this cottage industry.”

Marc Savitt, president of NAIHP and former NAMB president

—————————————————————–

“Appraisers are just getting nickeled and dimed, and we have no way to fight back.”

Joshua Tucker, chairman and co-founder of the

Appraisal Regulation Compliance Council

To read this article, Click Here

My comments: One appraiser’s AMCs story and comprehensive analysis of Where The Appraisal Fee Goes.HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down in 2026 and probably in 2027 but no one knows for sure.

Mortgage Applications Decrease in Latest MBA Weekly Survey

WASHINGTON, D.C. (November 4, 2026) — Mortgage applications decreased 1.2 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 30, 2026.

The Market Composite Index, a measure of mortgage loan application volume, decreased 1.2 percent on a seasonally adjusted basis from one week earlier.  On an unadjusted basis, the Index decreased 2 percent compared with the previous week.  The Refinance Index increased 0.1 percent from the previous week and was 60 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 2 percent from one week earlier. The unadjusted Purchase Index decreased 4 percent compared with the previous week and was 19 percent lower than the same week one year ago.

“Mortgage rates drifted down to their lowest level since September 2026 last week in the wake of the Federal Reserve’s decision to hold on additional rate hikes at its October meeting,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “While the 30-year rate declined to 7.3 percent, activity is still quite slow, with purchase application volume down for the week and refinance volume effectively flat at a very low level. As we have highlighted in recent weeks, more borrowers are choosing ARMs in this environment to lower their initial payments, with the ARM share at its highest level since September 2025.”

The refinance share of mortgage activity increased to 39.8 percent of total applications from 38.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.4 percent of total applications.

The FHA share of total applications decreased to 16.0 percent from 16.6 percent the week prior. The VA share of total applications increased to 11.2 percent from 11.0 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.5 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.30 percent from 7.37 percent, with points decreasing to 0.75 from 0.76 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.20 percent from 7.28 percent, with points decreasing to 0.48 from 0.64 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.02 percent from 7.12 percent, with points remaining unchanged at 1.07 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 6.76 percent from 6.70 percent, with points increasing to 0.98 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.29 percent from 6.41 percent, with points decreasing to 1.00 from 1.20 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

———————————————–

Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
AMC Panel Requirements

Newz: UAD 3.6: Fees, Turn-Time, Software and more, AMC Panel Requirements

October 30, 2026

ARTICLE LIST – In order, scroll down the page to read

  • LIA AD: AMC Panel Requirements
  • UAD 3.6: Inside the Struggle Over Fees, Turn-Time and Software By Frank Andorka, Managing Editor WorkingRE
  • A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market
  • What is Highest and Best Use in Appraisal? (Updated for UAD 3.6) , By Kevin Hecht
  • MY AD: What Enough of UAD 3.6, I Have a Business to Run!, By Doug Smith, MBA, SRA
  • UAD 3.6: A New Era of Accountability in Appraisal Quality, By Gynell Vestal (Administrator) American Valuation Society
  • Flock Camera Blunders and the Privacy Risks of UAD 3.6, By Desiree Mehbod
  • MBA stats: Mortgage applications increased 3.4 percent from one week earlier


Thanks to our Sponsor!!

——————————-————————-

UAD 3.6: Inside the Struggle Over Fees, Turn-Time, Software and more

By Frank Andorka, Managing Editor, Working RE

Excerpts: Editor’s Note: Since this article was written, the GSEs created an exception to UAD 3.6 implementation for sellers who aren’t able to make the full transition to the new standard before Nov. 2. The exception runs through May 19, 2027. The GSEs will also allow resubmissions of UAD 2.6 appraisal reports through June 27, 2027. As of March 1, 2027, UAD 2.6 appraisals will no longer qualify for certain appraisal-related representations and warranties relief. For more, check out our full report at workingre.com:

GSEs Create Exception for UAD 3.6 Deadline: Runs through May 19, 2027.

To read: Click Here

Nov. 2 is usually just another day on the calendar — but not this year

Timeline and Rollout

The rollout of UAD 3.6 has been hampered considerably by two problems: slow software rollouts and lenders dragging their feet. When Working RE covered Valuation Expo in Las Vegas at the end of August, the problems clearly came into view.

While most of the leading software providers received initial approval from the GSEs in late 2025 and early 2026, word on the ground at Valuation Expo (Val Expo) was that there were still plenty of bugs to work out. AMC executives privately shared that they had staff simultaneously testing all the GSE-approved reporting software so they could troubleshoot and support appraisers when they inevitably ran into problems trying to turn in assignments. Some of those bugs were being run back to the software companies in real time, with the appraiser, AMC, lender and software provider working through the problem together.

The bigger problem in August was that lenders had barely begun ordering the 3.6 appraisals at all. Rocket Mortgage staff at Val Expo said they had ordered six UAD 3.6 appraisals. Rocket originates roughly six to seven percent of all residential mortgages in the United States. Several regional AMCs reported completing exactly two assignments apiece — and in each case, one of the two was a test run the AMC had ordered itself.

Scott Reuter, chief appraiser at Freddie Mac, summed up the bind on a panel at the show: “Appraisers cannot do a 3.6 assignment unless somebody orders a 3.6 assignment.”

More Than 900 Data Elements

There were approximately 190 data elements in UAD 2.6. There are now more than 900 in UAD 3.6. Reuter says it’s easy to be overwhelmed if appraisers just hear the number, but he assures the industry that appraisers were in the room when the form was developed.

“I want to make sure they don’t just hear ‘more than 900 elements’ and worry that they won’t be able to do it,” Reuter says. “They won’t have to fill out all those data points for every property. They are never going to touch the lion’s share of them, but we wanted to make sure we accounted for every potential contingency just in case.”

Lyle Radke, senior director of collateral policy at Fannie Mae, says Fannie and Freddie hold, between the two of them, $7 trillion in mortgage debt which, since it’s backed by the U.S. Treasury, is guaranteed by U.S. taxpayers. Therefore, it stands to reason collecting more data than before is important.

“From that perspective, the data is essential,” Radke says. “It’s how we manage risk. UAD 3.6 makes it easier for us to see and understand the data. If we didn’t have 3.6, we could still parse the data, but it would be much more challenging and time consuming.”

Other topics include turn times, liability and fees.

As the industry rushes toward the Nov. 2 deadline, appraisers’ stress levels will continue to rise. The only question is: What will things look like when the smoke clears? Only time will tell.

To read more, Click Here

My comments: Good discussion of the issues with quotes from many people, including GSEs. Not many changes since the August conference, except software vendors are still sending out updates. Fees still unclear.


Read more!! →

Defending Adjustments for Appraisers

Newz:  GSEs Request Feedback on UAD 3.6, Defending Adjustments

September 4 , 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Too Late for a Reconsideration of Value
  • How to Defend Adjustments in Appraisal Reports
  • $112 Million Laguna Beach Mansion With a Private Library and a Rotating Bed in Primary Suite Could Become Priciest Home Ever Sold in Orange County
  • GSEs Request Appraiser Feedback on UAD 3.6
  • MY AD: How AI Can Help Residential Appraisers and Why Appraisers Will Always be Needed By By David Galatto
  • First the Borrower Fee. Now the Appraiser Compensation in Court By Kenneth J. Mullinix
  • The part of the process appraisers never see, and the reason your file keeps coming back
  • UAD 3.6 UPDATE – Inspection Checklist, New Survey: UAD 3.6 mandate is Nov. 2nd. Are you ready for it?,
  • MBA STATS: Mortgage applications increased 0.8 percent from one week earlier

————————————————————————–

How to Defend Adjustments in Appraisal Reports

When someone questions an adjustment, many appraisers respond, “It’s based on market data” or “my experience in the market.” These statements might be true, but they don’t support the adjustment. They just state where it came from.

Appraisal reports are similar to scientific papers. A scientist can’t write “Based on my experiments, the hypothesis is correct” and expect peer review to accept it. Scientists need to share their methodology, summarize their analysis, and support their conclusions.

The same applies to appraisal adjustments. Saying you used market data is like saying you conducted an experiment. It’s just the starting point. Your report needs to summarize how you analyzed the data and how it supports that specific adjustment.

Without this documentation, you haven’t provided credible analysis. You’ve stated an unsupported opinion, regardless of your experience.

You need a clear path from market evidence to the number on your grid. Defending appraisal adjustments isn’t one perfect technique. It’s about using multiple, credible methods, explaining your logic, and sequencing your work so it aligns with how the market behaves and with USPAP.

Below is a practical, step-by-step approach you can put to work right away.

Start with the Right Sequence

Before you calculate any adjustment, get the order right. In practice, you should follow this sequence:

  • Apply transactional adjustments:
  • Real property rights conveyed
  • Financing terms
  • Conditions of sale
  • Expenditures made after purchase
  • Market conditions (time)
  • Apply property adjustments:
  • Location
  • Physical characteristics (e.g., finished square footage, bathrooms, garages, condition, quality)

Transactional adjustments affect the overall transaction price, and each adjustment creates a new base for the next one. They answer the question, “What would this comparable have sold for under typical terms on my effective date?”

These adjustments normalize the sales by removing distortions from unusual financing, non-market conditions, or time differences.

Equalize Market Conditions Before You Compare

Read more!! →

Nobody is Ready for UAD 3.6 Today

Newz:  Nobody is Ready for UAD 3.6,

Time to Take Out the AMC Junk

August 28, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Think carefully before signing a Records Affidavit
  • Nobody is Ready for UAD 3.6 by Isaac Peck, Publisher WorkingRE
  • The famed rotating round house at 4 Harkle Road in Novato is for sale for the first time
  • It’s Time to Take Out the Junk: AMC Practices Exposed by Logan Dorman
  • MY AD: How to reduce stress to be more productive in business and a happier life
  • Becoming an Appraiser: Courage to Grow Beyond Training by Timothy Andersen, MAI
  • UAD 3.6 UPDATE – Comp Photos, Any Future for Residential Appraisers?
  • MBA STATS: Mortgage applications decreased 1.0 percent from one week earlier

Nobody is Ready for UAD 3.6

by Isaac Peck, Publisher WorkingRE

I just got back from Valuation Expo, the nation’s largest and most dynamic conference for real estate appraisers and valuation industry stakeholders. More than 800 people made it to Las Vegas this year.

Appraisers, chief appraisers at appraisal management companies (AMCs), lenders, regulators, software developers, service providers, insurance professionals and more convened to talk about the latest technology and explore where the profession is headed.

The mood was elevated and positive—many attendees were genuinely invigorated and excited about the future. And yet, despite all the positivity, another reality was plainly clear from the conversations: Nobody is ready for UAD 3.6.

While many of the leading software providers received initial approval from Fannie Mae and Freddie Mac (the GSEs) in late 2025 and early 2026, word on the ground is that there are still plenty of bugs to work out.

AMC executives privately shared that they have staff simultaneously testing all the GSE-approved appraisal reporting software so they can troubleshoot and support appraisers when they inevitably run into bugs and errors trying to turn in an assignment. Some of those bugs are being run back to the software companies in real time, as appraisers, AMCs, lenders and software providers work together to find a solution.

In other words, while the GSEs tested the main appraisal report software providers on several different types of assignments, there are so many nuances, data fields and report settings that bugs are surfacing rapidly now that appraisers are finally doing live assignments.

In addition to the software challenges, part of the problem is that most lenders haven’t begun ordering UAD 3.6 reports at all.

I spoke with several regional AMCs. Each had completed just two UAD 3.6 assignments—and in each case, one of the two was a test run the AMC had ordered itself.

If one of the largest mortgage lenders in the country has only done six UAD assignments, how many appraisers have actually completed a UAD 3.6 assignment? The answer is very, very few.

An appraisal software executive shared with me privately that he fears appraisers may be (wrongly) blamed if the rollout goes poorly and the market is disrupted. It would be easy to sell a narrative that “appraisers weren’t ready,” or that appraisers can’t handle the new report format. Such a view clearly misses the point. After all, appraisers don’t control the development of the software, nor do they control when UAD 3.6 reports start getting ordered, to Reuter’s point.

Will we see an avalanche of UAD 3.6 orders in September and October, and will the transition happen smoothly by mid-October? It seems unlikely.

Many thanks to Isaac Peck for “in person” realistic reporting on the Most Popular Topic in appraising – Future of UAD 3.6 and GSEs.

To read more, Click Here

My comments: Definitely worth reading the full article!!! I was unable to attend this conference but have attended many webinars and two “boot camps” via zoom since early 2025. Plus I have written about the problems.

This article was no surprise to me. It puts all the pieces together and has quotes from knowledgeable people, plus what appraisers said.

Read more!! →

Surplus vs. Excess Land for Appraisers

Newz: Surplus vs. Excess Land,
Easement Issues and Liability

August 14, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Easements: Issues and Appraiser Liability
  • Surplus Land vs. Excess Land: What Appraisers Need to Know, By Kevin Hecht
  • Built Different: How the Ranch-Style Home Went from 1930s Architectural Rebel to America’s Favorite Floor Plan
  • Let’s Talk About Letters of Engagement, By Jeff Whaley
  • MY AD: UAD 3.6 Software Evaluation Checklist
  • An Abridged History of the Appraiser Profession, By Kendra Budd, Editor Working RE
  • My UAD 3.6 Tips of the Week
  • MBA: Mortgage applications increased 3.6 percent from one week earlier

———————————————————

Surplus Land vs. Excess Land: What Appraisers Need to Know

By Kevin Hecht

Excerpts: Land valuation is a fundamental aspect of real estate appraisal, influencing property transactions, development decisions, and investment strategies. A key part of the process involves distinguishing between the land that supports the property’s current use and any additional land that may or may not have independent value.

Commonly, a square footage adjustment is made based on lot size differences among comparable properties without one key distinction: whether the difference in land is surplus or excess land. This fails to consider whether the extra land has value independent of the subject property.

Surplus land generally does not contribute value beyond its association with the primary parcel, though it may still add some contributory value in certain market conditions. Excess land, by contrast, has value because it can be divided and sold separately.

Understanding this distinction is essential for developing a credible appraisal.

Surplus Land vs. Excess Land at a Glance

Surplus Land – Cannot be separated and sold independently

Excess Land – Can be divided and sold separately

Surplus Land – No independent highest and best use

Excess Land – May have a different highest and best use

Surplus Land – Typically contributes limited additional value

Excess Land – Has independent value and should be analyzed separately

Surplus Land – Remains part of the primary property

Excess Land – Can potentially support separate development

Key Differences Between Surplus and Excess Land

Surplus and excess land apply to commercial and residential properties. Before determining whether land is surplus or excess, appraisers must consider zoning, highest and best use, surrounding properties and their use, property improvements, and supply and demand for the property and any proposed improvements.

Why the Distinction Matters in Appraisal

Choosing the correct land type has an effect on the final value of the property. Excess land adds value to the subject property and creates future potential. Thus, a higher price per square foot should be assigned to excess land over surplus land.

Ultimately, identifying land type is about more than just checking if a property can be split. It’s about understanding the property’s most productive use under current legal and economic conditions.

To read more, Click Here

My comments: Read this article!! The best comprehensive article I have read on this issue. Understanding Surplus vs. Excess Land is critical in appraising. I have encountered this issue mostly in commercial and agricultural appraisals. It can happen in any type of property.

Unfortunately, residential lender appraisers sometimes encounter this but don’t know much about it. I have appraised it on single family properties. Not understanding what this is of the many ways residential appraisers end up trouble at the state appraisal board because of lack of knowledge and experience.

Read more!! →

AQB Exposure Draft Removes College Degree Requirement

Newz: Appraisal Stress Test, AQB Exposure Draft Removes College Degree Requirement

June 26, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: State Board Complaint Frustrations
  • The Appraisal Profession Is Being Stress-Tested. That’s Not the Same as Being Replaced By Jessica Sturm
  • All About the Brownstone: How the Iconic Design Went From Humble Row House Roots to Million-Dollar Metropolis Luxury
  • MY AD: UAD 3.6 Software Evaluation Checklist By Doug Smith
  • Include E&O in Appraisal Reports? Just Say No By Isaac Peck
  • AQB second exposure draft removes college degree requirement
  • MBA STATS: Mortgage applications increased 1.0 percent from one week earlier     
  • ———————————————————


The Appraisal Profession Is Being Stress-Tested.

That’s Not the Same as Being Replaced

A frank conversation about UAD 3.6, waiver expansion, and where the real opportunity lies.

By Written by : Jessica Sturm, EVP of Property Services at Opteon.

Excerpts:

What UAD 3.6 Actually Changes (And What It Doesn’t)

UAD 3.6 changes the infrastructure around how appraisal judgment is captured, structured, and delivered. It does not change what a great appraiser does and the value they bring. Your ability to walk a property and know, as a trained professional, that the finished basement wasn’t permitted, that the kitchen renovation was done on the cheap or that the comparable three streets over sold under pressure. None of that local, industry expertise lives in a data schema.

What the new standard demands is that the mechanics around that judgment are handled cleanly and consistently. Field data capture, structured commentary, condition ratings, quality flags, all in a format that downstream systems can use. That’s not a threat to expertise. We see this as a long-overdue investment in the infrastructure that supports our industry.

What the Stress Test Is Really Asking

Every industry stress test asks the same question: who is built for what comes next?

UAD 3.6 is asking whether the profession can operate with greater rigor and efficiency. Waiver expansion is asking whether appraisers can own the complex, high stakes, advisory end of the market with real authority. The mature appraiser pipeline is asking whether the profession can retain experience and retrain while bringing in and developing new people. These are hard questions, but the profession has more tools, more data, and more support to answer them than at any point in its history.

Accounting faced the same reckoning. When tax software arrived and then matured, the prediction was that it would hollow out the profession. Routine compliance work did automate and what happened next was the opposite of collapse.

To read more, Click Here

My comments: Interesting analysis. I think the new reports are much better than the old forms for reviewers and borrowers. If I was doing GSE appraisals I would look forward to doing them.

Read more!! →

24 Hour Appraisals

Newz: 24 Hour Appraisals, Bias Accusation Collapses, Easements and Appraiser Liability

May 15, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Easements and Appraiser Liability
  • 24-Hour Appraisals: The Future or a Gimmick? By Shawn Telford , Chief Appraiser and Valuation Officer at Cotality
  • $28 Million ‘Pavilion’ House in Los Angeles Boasts ‘Once-in-a-Generation’ Design—and a Sunken Conversation Pit
  • Freddie/Fannie UAD and Forms Redesign: Enhanced Timeline and Updated FAQs
  • MY AD: Appraisal forms software in September, 1993 – a glance at the past
  • AQB Releases White Paper on Experience Requirements
  • Bias Accusation Collapses as HUD Clears the Appraiser by Desiree Mehbod
  • MBA: Mortgage applications increased 1.7 percent from one week earlier


—————————————————————————

24-Hour Appraisals: The Future or a Gimmick?

By Shawn Telford , Chief Appraiser and Valuation Officer at Cotality,

Rethinking Quality and Risk in Modern Valuations: Why Faster Can be Risky

Excerpts: side from the opinion of value, speed is often the next loudest talking point in any conversation about appraisals—but it’s also one of the most misleading. While accelerated appraisal procurement models promise faster turn times, they do little to address the concerns that matter most to lenders: inaccurate valuations, which lead to appraisal defects that create buyback exposure and margin pressures for lenders, ultimately contributing to delays and additional costs.

This isn’t to say that the prospect of 24-hour appraisals is not appealing: after all, who doesn’t like faster? But is it a game-changer or merely a gimmick?

Today, lenders are facing greater scrutiny from the GSEs and investors over loan quality, in general, and collateral valuations in particular. Recently, Fannie Mae reported that collateral defects – like property damage, appraisal condition & quality rating inflation, and inappropriate comparable sale selection—are now accounting for nearly half of discretionary loan review defects. Solving for the Right Problems

Pressuring appraisers to work faster is hardly going to address these issues.

The Economic Impact of Quality

Getting an appraisal quickly can be a plus. But if the valuation requires extensive rework, it can create friction and delays and add operational costs to the underwriting process. One of the biggest slowdowns in the appraisal process is the back-and-forth between the appraiser and an AMC’s lender over administrative “corrections” that often don’t affect the opinion of value. In fact, recent Cotality data shows that nearly half of all appraisals are returned for some type of correction, and the vast majority of those returned do not have their value changed when resubmitted.

To read more, Click Here

My comments: very good analysis with many excellent comments. Very knowledgeable author. Worth reading.


Read more!! →

The Appraiser Exodus and How to Fix It

Newz: Expanded Intended Users?

The Appraiser Exodus and How to Fix It.

May 8, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Expanding Intended Users? Not So Fast
  • Under Pressure: What’s Driving the Appraiser Exodus and How to Fix It, By David Massey
  • Historic Tudor Estate With English Gardens and Prairie Views Is Listed for $4.7 Million Near Chicago
  • What is a Pre-listing appraisal? Written for Home Owners But Has Good Tips for Appraisers, By Tom Horn
  • MY AD: What Happened When Government Decided That Appraisers Needed Protection, By Cindy Chance, PhD
  • How to See the Potential in Homes That Don’t Look Perfect. Written for Home Owners But Has Good Tips for appraisers
  • More Than 60% of America Is Covered by Drought and Millions of Homes Are at Risk
  • UAD 3.6 Bootcamp, LIVE in Chicago, IL and on Zoom, Wednesday – Friday, May 13th-15th
  • MBA STATS: Mortgage applications decreased 4.4 percent from one week earlier


——————————————————————-

Under Pressure: What’s Driving the Appraiser Exodus and How to Fix It,

By David Massey

Ask any veteran appraiser or physician what has changed most over the past twenty years, and the answer is usually the same: paperwork.

Professions once centered on skill, judgment, and service are now dominated by portals, compliance layers, and third-party control. Burnout rises, independence falls, and a quiet exodus follows.

The American Medical Association reports that physicians now spend nearly two hours on documentation for every hour of patient care.

The appraisal profession is now well into that cycle.

According to the Appraisal Institute’s 2023 Fact Sheet, the number of practicing appraisers in the United States has declined by roughly 8,000 in recent years. The Conference of State Bank Supervisors shows a longer-term drop from about 120,000 appraisers in 2008 to fewer than 96,000 by 2017, a 21 percent decline in less than a decade. IBISWorld reports another six percent employment drop between 2018 and 2023. The U.S. Bureau of Labor Statistics projects only modest growth through 2034, far short of what is needed to replace retirees.

The pipeline is shrinking while demand remains steady.

The National Association of Realtors ® 2023 Appraisal Survey found that more than half of appraisers are now asked monthly, or more often, to complete assignments outside their normal geographic or property-type expertise. More telling, 54 percent cited Appraisal Management Companies as the single greatest challenge to their business. That statistic alone explains much of what has gone wrong.

When I started in this profession, appraisal centered on analysis, interpretation, and professional opinion. I studied neighborhoods, walked properties, and applied experience to market behavior. Today, much of the job revolves around compliance portals, redundant uploads, and layers of review by people who have never inspected a property.

AMCs were created after the 2008 crisis to protect appraiser independence. The idea made sense. The execution has failed. Today, borrowers commonly pay $600 to $700 for an appraisal, while the appraiser often receives about half of that after AMC fees. Turn times lengthen. Panel depth shrinks. Geographic competency erodes. And experienced appraisers quietly step away.

What was meant to reduce pressure has become a system of control. Communication between lenders and appraisers is filtered. Pricing is dictated by algorithms. Scope interpretations are issued by third parties removed from the field. Judgment is slowly replaced by checklist compliance.

Healthcare has already traveled this road.

A 2025 Annals of Internal Medicine study showed nearly five percent of U.S. physicians left clinical practice in a single year, driven largely by burnout and administrative burden. The American Medical Association reports that physicians now spend nearly two hours on documentation for every hour of patient care.

Appraisers now operate inside the same imbalance. More time formatting reports than analyzing markets. More time satisfying review protocols than developing defensible opinions. Judgment yields to process.

This is not a workforce inconvenience. It is a structural market risk.

The fix is not complicated, but it does require courage.

First, appraisal fee transparency must be mandatory. If a borrower pays $650 and the appraiser receives $325, both parties deserve to know. Transparency restores accountability and allows market forces to function.

To read more, Click Here

My comments: Worth reading, especially how to fix it. We all know what is happening to residential lender appraisers.

For doctors, corporate medicine has taken over. For example, primary care physicians are allowed only 15 minute visits with patients. Large insurance companies make it very difficult for patients to get the care they need by denying what the patient needs. Doctors don’t like it, plus the excessive paperwork.

I play pickleball with a retired doctor. He had to sell his medical practice as he was underbid on fees by large health insurance companies.

Read more!! →

Avoiding Court: A Common Sentiment Among Appraisers

Newz: Cyber Attack Risk for Appraisers,

Avoiding Court: A Common Sentiment Among Appraisers

May 1, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Avoiding Court: A Common Sentiment Among Appraisers
  • Cyber Insurance: Why It’s Time for Appraisers to Protect Themselves By Isaac Peck, Senior Broker at OREP.org
  • Electrochemist’s Exclusive Private Island Escape With 9-Hole Golf Course and Helipad Hits the Market in Florida for $89 Million
  • Hype Heretics – Twisting the narrative to create hype. By JoAnn Apostol
  • MY AD: What is a Good Appraiser?
  • April 2026 Housing Insights: A Market Searching for Stability, By Kevin Hecht, Appraiser and Economist
  • A new Scope of Work, By George Dell, MAI
  • MBA: Mortgage applications decreased 1.6 percent from one week earlier

——————————————-


—————————————————

Cyber Insurance: Why It’s Time for Appraisers to Protect Themselves

By Isaac Peck, Senior Broker at OREP.org

Excerpts: You log in, expecting to send a report or check your schedule for the coming week, only to find your system locked, client files gone, and a message blinking on the screen:

“YOUR FILES ARE ENCRYPTED

To regain access, you must pay a ransom. Do not attempt to decrypt or modify the files yourself.

Any unauthorized action will result in permanent data loss.

Payment instructions are below. You have 72 hours.”

Directly below the words, a clock begins counting down.

You feel panic setting in.

To make matters worse, you had committed to delivering a rush appraisal to the lender/AMC this morning for a time-sensitive closing. You can’t access reports, contact clients, or meet deadlines. You’re losing money, time, and worst of all, your clients’ trust.

Directly below the words, a clock begins counting down.

This type of mentality only compounds the problem. According to recent national data, more than half of U.S. cyberattacks now target small businesses, not large corporations. Firms with fewer than 100 employees are significantly more likely to be targeted than larger companies, largely because they lack dedicated IT staff, formal security protocols, and incident-response plans. In other words, they’re easier targets.

The financial consequences are not theoretical. According to Verizon’s 2024 Data Breach Investigations Report, small business data breaches can cost anywhere from $120,000 to over $1.2 million, depending on severity. Other industry studies released this summer put the average cost of a single cyber incident at roughly $25,000—far more than most appraisal businesses can absorb without serious disruption.

Unique Risks for Appraisers

Home appraisers face unique cyber risks that make them especially vulnerable to digital attacks. Unlike larger firms with dedicated IT teams, most appraisers operate as solo practitioners or small businesses.

Nevertheless, even the smallest appraisal offices handle highly sensitive data every day: property details, borrower information, lender communications, and access credentials all flow through their systems, often via unsecured emails or cloud-based platforms.

The Role of Insurance

When a cyber incident hits, speed matters. For appraisers, the real damage often isn’t just the ransom demand or the technical cleanup—it’s the downtime, the missed deadlines, and the loss of client confidence that follows.

Cyber insurance exists to help businesses recover quickly and responsibly. For appraisers, that means having access to technical experts who can investigate what happened, contain the breach, and restore systems so work can resume. It also means guidance on how to communicate with lenders, clients, and other parties if sensitive information is compromised.

To read more, Click Here

My comments: Read this article. I have received information from several appraiser E and and O companies about cyber insurance. And read about the risks online. This article is definitely the best I have read as it explains the details of what a cyber attack means for appraisers. Since it was from an E and O carrier I did not know how much useful information it had. I’m glad I read it and wrote about it.

Read more!! →