FHA new manual 9/15/15 – no changes or USPAP problems?

FHA says no significant changes from previous requirements
My comment: I have heard from knowledgeable appraisers and instructors that there are few changes from the old handbook.
Recent posting by Coleen Morrison on a Facebook group
I heard back from my contact at HUD, and here is what she said: “Ms. Conde [the author of the article] (Ed note: see below) and I have had multiple conversations. FHA has not changed any of its requirements regarding the items that she discusses. If an FHA appraiser was compliant prior to September 14, the appraiser is going to be compliant after. The language has changed a bit, mostly for clarity and format, but the requirements are the same.”
I have written back and asked specifically about their thoughts regarding the Competency Rule. I have been saying the same thing … that nothing has really changed… but I never thought about the Competency Rule. It seems very contradictory when the HUD manual states the appraisal is not to be considered a home inspection;
The handbook states: “FHA appraisals are not a guarantee that the property is free from defects. The appraisal establishes the value of the property for mortgage insurance purposes only. Buyers need to secure their own home inspections through the services of a qualified inspector and satisfy themselves about the condition of the property.”
Adding the statement from the manual into your appraisals, and referencing Assumption and Limiting Condition #5 are 2 steps you can take to help protect yourself. I don’t know how much of a fight we can have against HUD, so if you choose to do FHA appraisals, and you were not doing the extent of inspection which is very clear in the 4001 now, you will need to step it up; add what the HUD manual states above in big bold letters to your report; or choose not to do FHA appraisals. The ultimate choice is yours.
My comment: I quit doing FHA appraisals in 1988, after 2 years on the roster. Too many requirements as compared with conventional. Plus… our local property values had skyrocketed way above the FHA limits… not much work.
————————————–
FHA vs USPAP – Appraisers Caught in Catch 22
By Joanne Conde
Excerpts:
The new FHA Handbook will become effective on September 14, 2015. There has been much discussion of the implications of changing “should” to “must” in thousands of examples in the Handbook. As a Board member of the Arizona Association of Real Estate Appraisers as well as being on the FHA Roster, I have taken a good hard look at these requirements and then, it hit me as I was teaching the Uniform Standards of Professional Appraisal Practice (USPAP) which is the basis of appraisal standards for every appraiser in the United States. The FHA assignment conditions, whether under “should” to “must” force appraisers into a Catch 22 or turn down the FHA appraisal assignments. FHA is essentially making it a condition of employment that appraisers violate the Competency Rule. Why did I not see this before? I guess because the two never converged in my mind at the same time and I expect that is what has also happened to other appraisers.
It is an FHA assignment condition that appraisers make the following statement within the report: “The utilities were on and functioning at the time of inspection and the home meets 4150.2 & 4905.1 HUD Requirements,” and “Other intended users[of the report] are HUD/FHA.”
Click here to read more and read appraisers’ comments

Are you or your firm planning on any hiring trainees within the next 5 years?

Are you or your firm planning on any hiring trainees within the next 5 years?


My comment: I wonder what the response would be if lenders allowed trainees to sign on their own… remember the mortgage broker days? I sure wish there was a survey on trainee commercial appraisers as I see lots of them where I am. I am hearing that it is back to the “old days” when fee appraisers only hired relatives (because most appraisers were staff appraisers at lenders).


Appraisal Today newsletter

21 Reasons Why Corner Lots Are For Suckers

To keep up on what is happening in appraisal businesses, mortgage lending, USPAP, etc. , Plus humor and strange homes, sign up for my FREE weekly appraisal email newsletter, sent since June 1994. Go to Home on the left side of the menu at the top of this page or go to www.appraisaltoday.com
Sign up in the Big Yellow Boxes

Excerpt:

1. Noise, noise, noise. Double street and sidewalk frontage means double the noise from pedestrian and car traffic. Pull up a chair and crack open a cold one; I’m just gettin’ started.

2. Unconventional configurations. For example, the front yard of a home on a corner lot is usually bigger than the back, and the garage may be located around the corner.

My comment: I have always wondered why there was a checkbox on the 1004 for corner lot… a mystery to me;> Maybe it was a factor in the 1960s/1970s, when the first forms were developed and used. Maybe it has been taken off some of the forms…

Click here to see the other 19 reasons!!

http://time.com/money/3980951/corner-lots-are-for-suckers


Appraisal Today newsletter

AMC/lender now accepts trainees signing on appraisal reports

Be sure to check your state’s requirements, as they vary widely among the states.

This is the first one I know of. Maybe they have been reading my free emails where I suggest this is the only solution to the appraiser shortage, now and in the future, that can start immediately. FYI, Red Sky is owned/affilated with U.S. Bank

Excerpts from an email (Appraiser Partner News) sent to appraisers on its panel June 11, 2015

======================================

Supervisory Appraiser Change

Upon review, Red Sky Risk Services, LLC has refined its expectations regarding the involvement of appraiser trainees. Important to note, the following change DOES NOT override specific state statute(s) or appraiser training requirements.

Effective immediately, Red Sky is no longer requiring supervisory appraisers to be physically present with trainee appraisers at all subject property inspections and driving comparable sales.

My comment: There is a short additional list of specific requirements. But, they are nothing new – Supervisor to review report, responsible for report, etc.


Appraisal Today newsletter

Are You a Tier 1 or Tier 2 Appraiser?

by Richard Hagar, SRA

Excerpt:

Nordstrom or Walmart? Mercedes or Yugo? Are you a Tier 1 or Tier 2 appraiser? Appraisers have two different business models to choose from.

I have seen that many lenders classify appraisers into two or three different tiers based on their perception of the quality of your product. Which tier are you? The amount of business you have and the amount you are paid is very likely based on how lenders classify you.

There is a lot of appraisal business right now and lenders are begging for high-quality appraisals. Many firms are buried in business, quoting three-plus weeks out in turn time, with high fees; here in the Northwest we are earning $550 for a standard home. If your company is not busy or you are making far less than this, here are some tips.

My comment: Appraiser tiers have been around for a long time. They were used when I started my appraisal business in 1986. In the past, they were referred to as “preferred” or “private banking”, etc. Prior to HVCC they were often used for high dollar properties. After HVCC, lenders placed the appraisal orders directly, not through AMCs they used.

Read the full article. Worth reading!!

http://www.workingre.com/tier-1-tier-2-appraiser/


Appraisal Today newsletter

Appraiser shortage – for AMCs (Appraisal Management Companies), not other clients

Appraiser shortage – for AMCs, not other clients

There is a significant shortage of appraisers willing to work for AMCs with low fees and escalating Scope Creep.

AMCs whose business model is based on low fees to appraisers are having difficulty finding anyone willing to accept their appraisals. They keep calling and calling trying to find someone to work for their low fees.

Direct lenders or the few “good” AMCs are not experiencing an appraiser shortage. Appraisers who work for them turn down AMC work.


Appraisal Today newsletter

Comp Photos and MLS, Fannie, USPAP, etc.

To keep up on what is happening in appraisal businesses, mortgage lending, USPAP, etc. , Plus humor and strange homes, sign up for my FREE weekly appraisal email newsletter, sent since June 1994. Go to Home on the left side of the menu at the top of this page or go to www.appraisaltoday.com
Sign up in the Big Yellow Boxes

I regularly write about hot topics in appraising and appraisal business management issues
in my paid Appraisal Today monthly newsletter.
$99 per year or (credit card only) $8.25 per month, $24.75 per quarter, or $89 per year.
For more info, go to https://www.appraisaltoday.com/products


Appraisalport polls on comp photos from June 2015

By Steve Costello,

This month I want to discuss three recent polls dealing with comp photos. In the first poll, we asked “With the availability of MLS photos, do you still feel it is necessary to drive by and photograph every comp?” We had a total of 3819 responses and the top two answers were very close. The winner, with 40 percent of the vote, was “Sometimes, it depends on the complexity of the specific assignment.” Coming in a close second was “Yes, I always want to see any property I use in a report” with 38 percent of the vote. The final answer of “No, I would rather just use MLS photos” only scored about half the votes as the first two answers, finishing with 22 percent. This makes sense because I think most appraisers want to look at a comp before they include it in a report, especially if they aren’t already familiar with the property. I can also see where some appraisers are very familiar with the properties in their area, use many of the same comps over and over again, and don’t feel a need to drive by and photograph them every time they use them.

In the next poll, we asked “In your opinion, with MLS, Google, and other photo sources available to clients, the main reason original comp photos are required from the appraiser is:” This poll had 3986 responses and had a pretty clear winner. A full 63 percent of the appraisers chose the answer “To make sure the appraiser actually drives by the comps.” So it looks like most appraisers don’t think their clients care as much about the actual photo compared to just making sure the appraiser actually visited the comp. The answer we expected to be very popular, “To provide the client with up-to-date photos of the comps – ensuring they exist in the stated condition,” only received 22 percent of the vote. A third response of “So the clients won’t have to take the time to look up the photos from one of the sources noted above” didn’t do well, only pulling in 3 percent of the vote. Not a surprise — we didn’t really expect many appraisers to choose that answer. Finally, 13 percent of appraisers went with “Other reason” as the best choice for this question. We really don’t know if there were one or many “other reasons” or what they are.

Finally, we asked “Would you be in favor of eliminating the requirement to include an original photo of every comp as long as a recent MLS photo of the property could be included with your report?” This question was very popular with 4770 total votes. It also produced a landslide vote with 79 percent of the appraisers selecting the answer “Yes.” Only 15 percent answered “No” and would not want to use an MLS photo instead of an original if it were available. A final 6 percent were “Not sure” how they felt about this issue. So, from this poll it is clear that appraisers feel that an original photo is not a necessity to produce a quality appraisal as long as a good representative photo is available from another source like an MLS.

My comment: As we all know, a photo taken at the time of listing from the MLS is often better than one taken later and USPAP does not require comp photos. Fannie Mae certifications require that the appraiser inspect the exterior of the comp, not take a photo. What about re-using a comp photo? Why the requirement of an “original” photo? To be sure appraisers drive by the comps.

Appraisal Humor

Appraisal business tips

A very, very funny appraiser video!

What does it cost to take appraisal comp photos?(Opens in a new browser tab)

Poll – Taking comp photos?(Opens in a new browser tab)

Appraisal Today newsletter

FHA extends deadline for new Handbook 4000.1 to June 15, 2015

Handbook Implementation Date Extended 90-days to Give Lenders More Time to Operationalize

On April 30, 2015, the Federal Housing Administration (FHA) announced that it has extended the effective date for the policies contained within its new Single Family Housing Policy Handbook (SF Handbook; HUD Handbook 4000.1) from June 15, 2015 to September 14, 2015.

FHA recognizes that there currently are a number of competing initiatives occurring simultaneously in the mortgage industry that may be challenging mortgagee and other industry partner resources. For this reason, FHA is extending the SF Handbook effective date by 90 days with the expectation that this additional time will enable mortgagees and others to be fully compliant with the new effective date.

Link to new handbook 4000.1http://portal.hud.gov/hudportal/documents/huddoc?id=40001HSGH.pdf

The bulk of the appraisal section starts on pdf page 441 and runs through pdf page 507.

My comment: We love to procrastinate ;> For appraisers, this means there will be opportunities for webinars and seminars. Also, written explanations. The June issue of the paid Appraisal Today newsletter will have an article on the changes written by Doug Smith, SRA, Montana appraiser. Doug has been writing for the paid newsletter for many years. To subscribe, click on the ad below.

Yes, you can start using the new criteria now. Some people like to get ready ahead of time ;>

Appraisal Today newsletter

Appraisals-how long to write/how many per week

To keep up on what is happening in appraisal businesses, mortgage lending, USPAP, etc. , Plus humor and strange homes, sign up for my FREE weekly appraisal email newsletter, sent since June 1994. Go to Home on the left side of the menu at the top of this page or go to www.appraisaltoday.com
Sign up in the Big Yellow Boxes

I regularly write about hot topics in appraising and appraisal business management issues
in my paid Appraisal Today monthly newsletter.
$99 per year or (credit card only) $8.25 per month, $24.75 per quarter, or $89 per year.
For more info, go to https://www.appraisaltoday.com/products

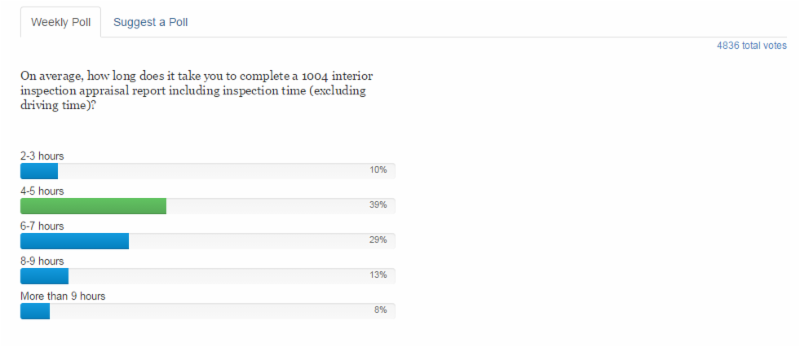
On average, how long does it take you to complete a 1004 interior inspection appraisal report including inspection time (excluding driving time)?

Another Very Interesting poll from May 2015

 My comment: I have been hearing about scope creep causing increased appraisal report writeup times but now there is some data. Significantly increased, and still increasing from pre-AMC days. My non-lender report writing time has not changed since before HVCC. Appraisalport is a lender portal, so I guess there are some appraisers that write fast and others that write slow. Or, maybe it depends on your clients. AMCs tend to combine the requirements of multiple lenders into very long lists of requirements.
—————————-

On average, how many “interior inspection” appraisals reported on a 1004 do you normally produce in a week?

My comments: Starting with a conforming tract home close to your office, the time increases, depending on driving time, use of an assistant and client requirements.

Appraisal Humor

Appraisal business tips

A very, very funny appraiser video!

Limiting Conditions and Assumptions Appraiser Humor(Opens in a new browser tab)

Appraisal Today newsletter

It’s Not a Comp, It’s a Sale – Lies, Damn Lies…and FNMA 'statistics'

Another “good one” by Dave Towne, Washington appraiser and commentator

Something’s been gnawing at my craw ever since January when FNMA’s wonderful CU was unleased to the world.  And before that, which still continues, is the AQM process they still use to judge the work of appraisers.

No one else has written about this, or even mentioned it, so I will: It has to do with the word “Comp” which is used liberally by FNMA.

What exactly is a “Comp?”

In FNMA’s world, it’s any property that they obtain, either by their vast AVM process which examines millions of property transactions, or properties that have been extracted from appraisal reports submitted by appraisers……..yes, your work.  In their fuzzy logic, it’s a “Comp” considered for your report if they say it is.  It is not!

A true “Comp” is a property viewed and/or analyzed by a real living, breathing, mirror fogging appraiser who compares that sold property against the subject property in terms of multiple features, characteristics and amenities.  It is not determined by an AVM or algorithm within the vast bowels of FNMA.  Until the property has such analysis done by an appraiser, it is merely a SALE……it is not a “Comp.”

This FNMA lie really became evident to me on 4/20/15 when FNMA released a news release about how CU has been integrated into their on-line Desktop Underwriter software mortgage lenders use, which you can read here:  http://www.fanniemae.com/portal/about-us/media/corporate-news/2015/6239.html?p=Media&s=News+Releases&from=RSS

Within that news release is this quotation from a VP at a mortgage lender:  “The collateral information that CU provides is invaluable and simply staggering,” said Breck Tyler, Executive Vice President, Trustmark Mortgage Services. “CU has aided in providing important comparable data that was previously unavailable or very difficult to get. CU messages in DU will help streamline appraisal review and make the underwriting of an appraisal a much more informed process.”

Then, FNMA released info directed to Correspondent Lenders who intend to use the CU process in UCDP, but don’t intend to sell the loan to FNMA:  https://www.fanniemae.com/content/fact_sheet/collateral-underwriter-non-seller-implementation-guide.pdf

That has this statement:  “Fannie Mae does not instruct or suggest to lenders that they ask appraisers to address all or any of the up to 20 comparables that are provided by CU for most appraisals.”

I want to repeat what I said above…in case you missed the point:  A PROPERTY IS NOT A “COMP” UNLESS YOU DETERMINE IT IS AND INCLUDE IT IN AN APPRAISAL REPORT.  Otherwise it’s just a ‘sale.’

If you’re an appraiser who liberally uses the word “Comp” in place of a ‘property sale’ I would ask that you be more careful.  If you receive info from a lender, AMC or anyone else who asks you to look at the “Comp” they have provided, correct them and use the words “sale property” until you have determined that it truly is a “Comp.”

I’m also asking members of appraisal organizations and associations to communicate your concern about this lie perpetrated by FNMA directly with them, and ask FNMA to change the word “Comp” used in their CU Reports, news releases, instructional materials, etc. to ‘Property Sales’ so that there is no misunderstanding about the significance of this issue.

If organizations and associations won’t do that on behalf of appraisers, then we might as well kiss the profession of residential real property appraising goodbye. Because if a list of ‘sales’ are considered “Comps” then an actual human appraiser won’t be needed to provide supportable property analysis and market value reports.

Dave Towne
dtowne@towneappraisals.com

www.towneappraisals.com
Mount Vernon, WA

My comment: I have been aware of the difference between a sale and a “comp” for a very long time. I try not to mix them up. It is very important when communicating with lenders and real estate agents, who should already know the difference. I am glad that Dave Towne points out this very big difference.

I have not found it to be an issue with non-lender clients, where I use “comparable sales” which is a much clearer term to use, since few are familiar with the term “comp”.

Appraisal Today newsletter