
Newz: Freddie ADU Guide, AMCs, AI and Appraisal Photos, FHA QC Changes
September 18, 2026
What’s in This Newsletter (In Order, Scroll Down)
- LIA AD: Expanding Intended Users? Not So Fast
- A Practical Guide to Appraising Accessory Dwelling Units (ADUs) By Freddie Mac
- Artificial Intelligence Will Not Replace Appraisers By Tony Pistilli
- Former 1847 Ohio Jail Goes Under Offer for $400K: How One Family Turned Inmate Cells Into Pantries and Closets
- MY AD: The Appraisal Triangle: Knowledge. Experience, Aptitude and Attitude
- HUD Rewrites FHA Appraisal Quality Control by Kenneth J. Mullinix
- If the Management Model Is So righteous, Spread It Around (AMCs)
- MY UAD 3.6 UPDATE How the get the list of GSE validated UAD 3.6 software vendors, Facebook page to read appraiser comments on UAD 3.6 software.
- MBA stats: Mortgage applications decreased 4.1 percent from one week earlier
A Practical Guide to Appraising Accessory Dwelling Units (ADUs)
By Freddie Mac
Excerpts: Sample Topics:
Appraisal Considerations:
Firstly, an appraiser can’t simply ignore an ADU. If the determination is made that additional finished area qualifies and meets the definition of an ADU, there are some practical steps the appraiser must take in the analysis.
Appraisal Development:
The appraiser will need to determine any effect the ADU has on the market value or marketability of the subject property. The appraiser’s analysis must be documented in the appraisal report and conclude whether an adjustment is supported for the ADU (remembering that the conclusion for no adjustment also requires market support).
Allowable Flexibility:
A good best practice for any appraiser is to reference and use Freddie Mac resources and published appraisal guidelines, which detail the steps an appraiser may take when valuing a property with an ADU. If a subject property ADU complies with zoning and land use requirements, the appraisal report must include at least one comparable sale with an ADU. If not available, then the appraiser may consider an older sale from the subject’s market or a competing market. The appraiser may also expand the search and comparison beyond just three sales, including pending contract sales or listings to justify the support for adjustments.
My comments: If you appraise ADUs, or are just curious, read this article from Freddie Mac!
To read more, Click Here
My comments: If you appraise properties with ADUs, read this detailed and practical advice for appraisers.
————————————————————-
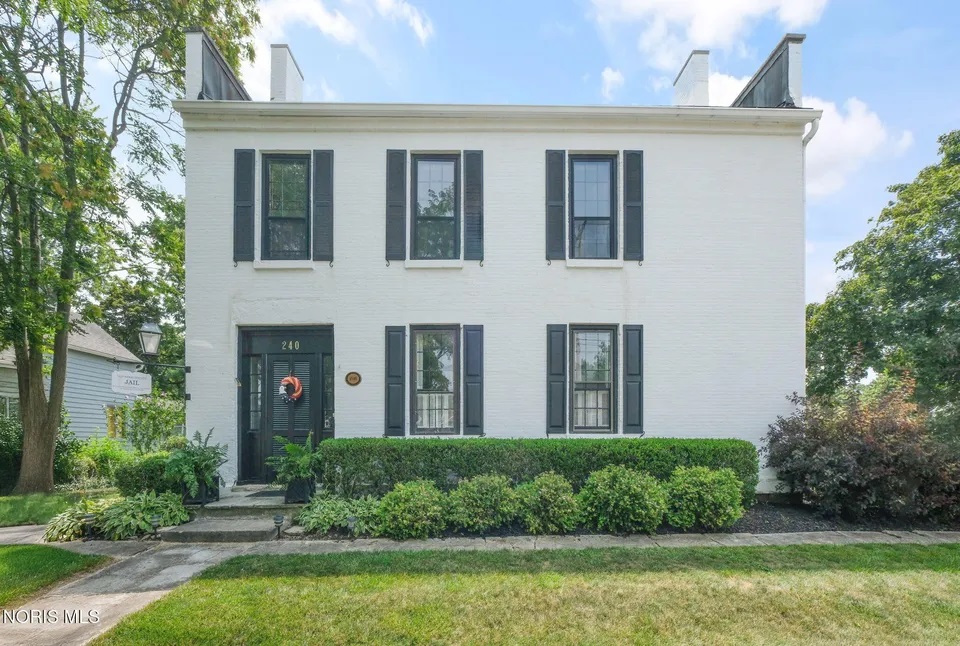
Former 1847 Ohio Jail Goes Under Offer for $400K: How One Family Turned Inmate Cells Into Pantries and Closets
Excerpts: 3 bedrooms, 3 baths, 2,690 sq.ft., 0.5 acre, built in 1947
When most people sit down for Sunday dinner, they aren’t staring directly into 19th-century jail cells. But for listing agent Caroline Hoffmann, having remnants of 19th-century law enforcement in the dining room was just part of normal family life.
The historic Old Wood County Jail at 240 W Indiana Ave in Perrysburg, OH—currently under contract with a contingent offer on its $400,000 listing—isn’t just an unusual piece of real estate to Hoffmann. It’s her family’s legacy.
“I think the fact that it still has the original jail cells intact is what really gets people’s attention all the time,” Hoffmann says. “Everybody wants to know if it’s haunted. It’s not.”
While the 2,960-square-foot brick property was originally constructed in 1847 and functioned as a county lockup until 1870, its modern history is deeply personal. The building served as the city jail until 1899, after which the public record goes quiet until 1918. That’s when Hoffmann’s family history with the structure began.
“My great-great-grandfather bought it from his brother-in-law in 1924. His brother-in-law had purchased it in 1918,” Hoffmann explains.
The structure was subsequently converted into three individual apartments—one on the lower level and two on the upper floor, each configured with one bedroom, a bathroom, and a small kitchen. Over the decades, it operated as a steady investment property.
To read the listing, with a floor plan and photos, Click Here
————————————————————
Artificial Intelligence Will Not Replace Appraisers
But appraisers who understand and use it responsibly will replace those who do not
By Tony Pistilli
Artificial intelligence has officially moved from the magical and mysterious into the mainstream of appraisal practice. Among the most significant forms of artificial intelligence entering the appraisal profession today is computer vision. This technology allows computer models to “see” pictures in ways that once, only human eyes could.
For many appraisers, this will raise understandable questions: How does this technology actually work? What are my obligations under USPAP? And how do I use artificial intelligence without getting in trouble with the state board?
And of course, many will also ask: If I use this, am I only contributing to the elimination of appraisers?
The answers point to a simple conclusion: Artificial intelligence does not replace appraisers. It rewards those who understand and use it well.
How Computer Vision Is Trained to “See” What We See
Computer vision is a subset of artificial intelligence that enables computers to extract information from pictures. This is much like what appraisers do today: We see a fireplace, write it down, and eventually type it into the form.
The Enduring Relevance of Appraisers
Virtually every respected profession has faced similar technological sea changes. Accountants weren’t replaced by Excel spreadsheets, radiologists weren’t replaced by imaging software, and attorneys weren’t replaced by online databases. These professionals got better, faster, and more accurate at analysis, diagnostics, and legal research. Their value remained intact.
Appraisers will be no different.
To read more, Click Here
My comments: Good analysis. The author has a software company using AI on photos and is very knowledgeable.
—————————————–
Are you getting too many ad-only emails?
4 ways to get only the FREE email newsletters and NOT the ad-only emails.
1. Twitter: https://twitter.com/appraisaltoday Posted by noon Friday
2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page. NOTE: the popular ads with liability tips are below the first topic on my blog posts.
3. Email Archives: https://appraisaltoday.com/archives
(posted by noon Friday) The link is above and to the left of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.
4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block. The newsletters have abbreviated titles, taken from their blog posts.
To read more about the 4 ways, plus information on why I take ads, etc.
—————————————————————-
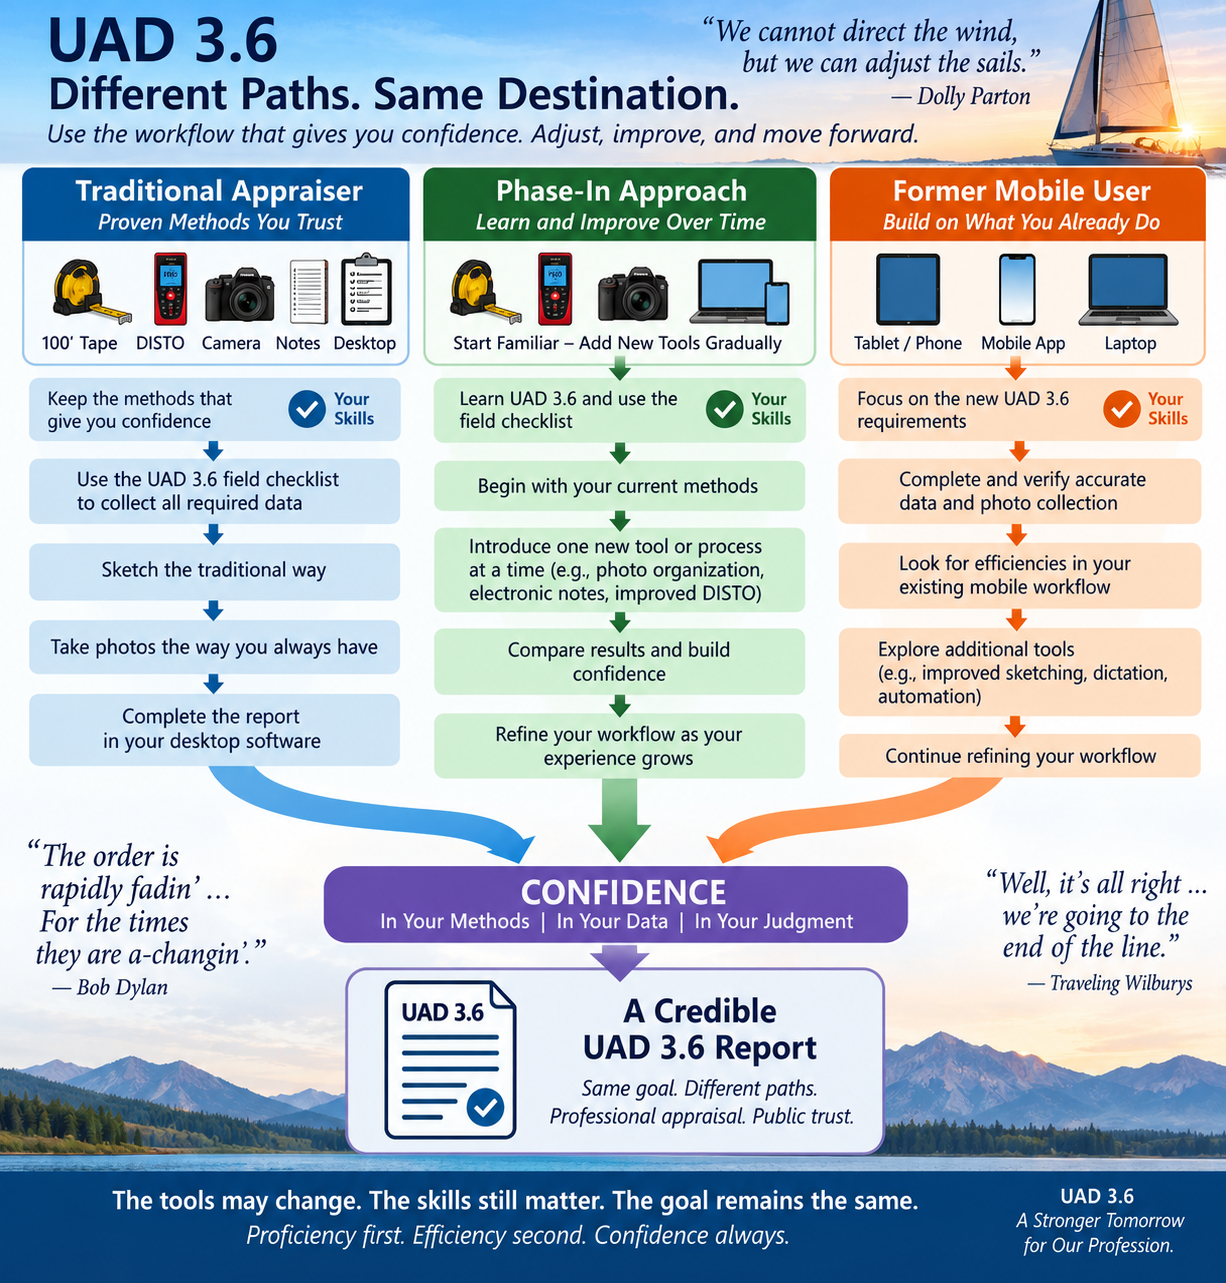
Appraisers, at this time must accept that “the order is rapidly fadin” and the whole appraisal world is headed to new horizons. The traditional elements of knowledge, experience and aptitude qualities require sharpening and enhancement,
By Doug Smith, SRA
In the September 2026 issue of Appraisal Today
Editor’s comment: Doug did the above very good image himself in Chatgpt!
He will be writing a very understandable article on how to use Chatgpt for appraisers for the November 2026 issue.
Excerpts: The traditional appraisal practice is represented by a three-sided triangle with two sides of knowledge and experience on a foundation of aptitude.
As important as all three of these are in a successful practice, attitude
remains the driving force. Attitude is the main requirement at this moment in time as the profession has always rewarded those willing to learn.
Appraisers, at this time must accept that “the order is rapidly fadin” and the
whole appraisal world is headed to new horizons. Appraisers, at this time must accept that “the order is rapidly fadin” and the
whole appraisal world is headed to new horizons.
The traditional elements of knowledge, experience and aptitude qualities require sharpening and enhancement,
Artificial Intelligence, UAD 3.6, new inspection technology, cloud computing, tablets, mobile workflows, XML reporting, and appraisal waivers are converging almost simultaneously. It is understandable that many appraisers feel overwhelmed.
Social media pages and discussion groups have become filled with
questions, software concerns, and uncertainty. Yet every profession reaches
moments like this. The issue is not whether change is occurring. The issue is how we respond to it. During times of uncertainty, the easiest decision is to make no decision.
Yet history shows that periods of greatest change reward those who
continue learning and adapting rather than standing still. Appraisers are uniquely trained to reconcile conflicting evidence. That is what the sales comparison approach teaches every day. Appraisers don’t wait for perfect comparable sales; they analyze imperfect information and arrive at a supported opinion.
Perhaps the greatest irony is that appraisers should be among the people
least afraid of uncertainty, because uncertainty is the environment in which they have always worked. Knowledge, experience and aptitude qualities require sharpening and enhancement,
To read the very interesting full article, plus 3+ years of previous issues, subscribe to the paid Appraisal Today at www.appraisaltoday.com/order .
Not sure if you want to subscribe?
Sign up for monthly auto renewal for $8.25!
Cancel at any time for any reason! You will receive a prorated refund.
$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)
or $99 per year or $169 for two years
Subscribers get FREE: past 18+ months of past newsletters
What’s the difference between the Appraisal Today free Weekly email newsletter and the paid Monthly newsletter? Click here for more info.
————————————————–
If you are a paid subscriber and did not receive the
September, 2026 issue emailed on
Tuesday, September 2, 2026 please email info@appraisaltoday.com, and we will send lt to you. You can also hit the reply button. Be sure to include a comment requesting it. Or, call 510-865-8041
—————————————————————–
HUD Rewrites FHA Appraisal Quality Control
by Kenneth J. Mullinix
Excerpts: Significant changes to the appraisal profession rarely arrive with headlines. Instead, they appear in agency guidance, revisions to underwriting manuals or updates to long-standing administrative procedures. Although these policy changes often receive little public attention, they can significantly influence how residential appraisers, lenders and appraisal management companies conduct business.
HUD Mortgagee Letter 2026-10 is one such change. Effective June 23, the U.S. Department of Housing and Urban Development (HUD) eliminated the long-standing requirement that FHA-approved lenders obtain appraisal field reviews on at least 10% of selected quality control loan files. While the revision appears procedural, it represents one of the most significant changes to FHA appraisal quality control in recent years.
More importantly, the Mortgagee Letter reflects a broader shift in regulatory philosophy — from prescribed review requirements to risk-based quality management that gives lenders greater flexibility while maintaining accountability for appraisal quality. For residential appraisers, it also provides insight into the future direction of federal appraisal oversight.
The New Rule
Mortgagee Letter 2026-10 eliminates the mandatory 10% sampling requirement. Instead of requiring appraisal field reviews on a fixed percentage of quality control files, HUD now permits lenders to determine whether a field review is warranted based on their assessment of collateral risk.
Why HUD Made the Change
HUD’s rationale is both practical and economic. According to the agency, mandatory appraisal field reviews often produced limited additional benefit while imposing measurable costs on lenders. HUD estimated that eliminating the requirement could save the mortgage industry approximately $3.3 million annually. What It Means for Appraisers
Some appraisers may initially view the revised policy as a reduction in appraisal oversight. It is not.
Every FHA appraisal remains subject to lender review, underwriting analysis, automated quality control systems and potential post-closing examination. USPAP obligations and FHA reporting requirements remain unchanged, and appraisers remain responsible for producing credible, well-supported opinions of value.
For experienced appraisers, the practical impact should be minimal. Sound market analysis, logical adjustments, thorough documentation and transparent reporting remain the best defense against any form of appraisal review.
To read more, Click Here
To read the Mortgagee Letter 2026-10 Click Here
My comments: Detailed article. If you do FHA appraisals, check it out.
—————————————————————-
If the Management Model Is So righteous, Spread It Around (AMCs)
Excerpts: If the management model were truly noble, it would not stop at appraisers. Yet somehow the babysitting service never expands beyond us.
Once upon a time there was a profession that stood between the public and chaos. For forty five years I watched that profession take every punch the mortgage world could invent. Every market dip, every delayed closing, every regulatory shift, every headline looking for a villain landed on the appraiser. We carried it because we understood the role. We were the guardrail.
But when the word racist became fashionable, that was the breaking point. Appraisers were already the most over regulated people in the entire mortgage process. It was absurd to pretend that lawyers, originators, brokers, realtors, AMC’s and bankers were spotless while appraisers alone were the problem. That conclusion was not logical. It was convenient. And it became the narrative.
And here is the part that never gets said out loud. Why are appraisers the only ones being managed? Why is there an entire shadow industry built to supervise, monitor, and skim off the work of one profession while lawyers, originators, bankers and everyone else walk free? If management companies are such a brilliant idea, why not apply them to the legal world? Why not assign babysitters to originators? Why not force bankers to hand over most of their fee to a management company that checks their ethics and competence? If the management model is so righteous, spread it around. But it never is. It is only imposed on the appraiser.
To read more plus some interesting appraiser comments, Click Here
My comments: Short but interesting. I love the discussion of why appraisers? My answer: We have no large national association, such as NAR to speak for us.
My UAD 3.6 Update
How the get the list of GSE validated UAD 3.6 vendor software companies.
Go to https://singlefamily.fanniemae.com/integrated-vendor-list
Scroll down to Fannie Mae Product Interface
Select (scroll down) UAD 3.6 appraisal software provider then click Search.
I have included this link in other newsletters, if you can’t find the last time I included it. I check it almost every day to see what software is validated.
Fannie requires validation for uploaded appraisals. It does not mean that all the software components are completed and ready to go, such as inspection apps and AI.
As of 9/14/26 there were 10 validated vendor software approved. About 24 vendors total are anticipated.
Any UAD 3.6 software you are considering using MUST BE VALIDATED OR YOUR APPRAISALS WILL NOT BE ACCEPTED BY THE GSES.
——————————————————————–
Facebook group to read appraiser comments on UAD 3.6 software. : “Appraisers Perspective of UAD 3.6” Search for the vendor name or the software name, such as Total. My “go to” place to see what appraisers are saying. I go there regularly.
————————————————————————
HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, Click Here.
Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.
My comments: Rates are going up and down. We are all waiting for rates to drop lower in 2026.
————————————————————————-
Mortgage applications decreased 4.1 percent from one week earlier
Mortgage applications decreased 4.1 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending September 11, 2026. This week’s results include an adjustment for the Labor Day holiday.
The Market Composite Index, a measure of mortgage loan application volume, decreased 4.1 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index decreased 15 percent compared with the previous week. The Refinance Index decreased 9 percent from the previous week and was 65 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 1 percent from one week earlier. The unadjusted Purchase Index decreased 13 percent compared with the previous week and was 19 percent lower than the same week one year ago.
“Ongoing market concerns over spiking energy prices, persistently high inflation, and future monetary policy pushed bond yields and mortgage rates higher last week. As the 10-year Treasury inched closer to the 5 percent mark, mortgage rates followed and were almost 7 percent. The 30-year fixed rate at 6.97 percent was at its highest level since May 2025,” said Joel Kan, CMB, MBA’s VP and Deputy Chief Economist. “After adjusting for the Labor Day holiday, purchase applications dipped relative to the week prior as higher mortgage rates caused many buyers to pause their purchase decisions. The current level of rates also eliminated much of the benefit to refinance for many borrowers, resulting in declines in conventional, FHA, and VA refinance applications.”
The refinance share of mortgage activity decreased to 39.4 percent of total applications from 40.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity decreased to 8.4 percent of total applications.
The FHA share of total applications decreased to 16.9 percent from 17.2 percent the week prior. The VA share of total applications increased to 12.4 percent from 12.0 percent the week prior. The USDA share of total applications decreased to 0.4 percent from 0.5 percent the week prior.
The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) increased to 6.97 percent from 6.85 percent, with points increasing to 0.72 from0.67 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750)increased to 7.03 percent from 6.74 percent, with points decreasing to 0.59 from 0.63 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA increased to 6.62 percent from 6.53 percent, with points decreasing to 0.85 from 0.86 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 15-year fixed-rate mortgages increased to 6.30 percent from 6.17 percent, with points increasing to 0.98 from 0.93 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
The average contract interest rate for 5/1 ARMs increased to 6.23 percent from 5.82 percent, with points increasing to 0.99 from 0.84 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.
———————————————————–
Ann O’Rourke, MAI, SRA, MBA
Appraiser and Publisher Appraisal Today
1826 Clement Ave. Suite 203 Alameda, CA 94501
Phone: 510-865-8041
Email: ann@appraisaltoday.com
Online: www.appraisaltoday.com


