AMC Panel Requirements

Newz: UAD 3.6: Fees, Turn-Time, Software and more, AMC Panel Requirements

October 30, 2026

ARTICLE LIST – In order, scroll down the page to read

  • LIA AD: AMC Panel Requirements
  • UAD 3.6: Inside the Struggle Over Fees, Turn-Time and Software By Frank Andorka, Managing Editor WorkingRE
  • A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market
  • What is Highest and Best Use in Appraisal? (Updated for UAD 3.6) , By Kevin Hecht
  • MY AD: What Enough of UAD 3.6, I Have a Business to Run!, By Doug Smith, MBA, SRA
  • UAD 3.6: A New Era of Accountability in Appraisal Quality, By Gynell Vestal (Administrator) American Valuation Society
  • Flock Camera Blunders and the Privacy Risks of UAD 3.6, By Desiree Mehbod
  • MBA stats: Mortgage applications increased 3.4 percent from one week earlier
 

Thanks to our Sponsor!!

——————————-————————-

UAD 3.6: Inside the Struggle Over Fees, Turn-Time, Software and more

By Frank Andorka, Managing Editor, Working RE

Excerpts: Editor’s Note: Since this article was written, the GSEs created an exception to UAD 3.6 implementation for sellers who aren’t able to make the full transition to the new standard before Nov. 2. The exception runs through May 19, 2027. The GSEs will also allow resubmissions of UAD 2.6 appraisal reports through June 27, 2027. As of March 1, 2027, UAD 2.6 appraisals will no longer qualify for certain appraisal-related representations and warranties relief. For more, check out our full report at workingre.com:

GSEs Create Exception for UAD 3.6 Deadline: Runs through May 19, 2027.

To read: Click Here

Nov. 2 is usually just another day on the calendar — but not this year

Timeline and Rollout

The rollout of UAD 3.6 has been hampered considerably by two problems: slow software rollouts and lenders dragging their feet. When Working RE covered Valuation Expo in Las Vegas at the end of August, the problems clearly came into view.

While most of the leading software providers received initial approval from the GSEs in late 2025 and early 2026, word on the ground at Valuation Expo (Val Expo) was that there were still plenty of bugs to work out. AMC executives privately shared that they had staff simultaneously testing all the GSE-approved reporting software so they could troubleshoot and support appraisers when they inevitably ran into problems trying to turn in assignments. Some of those bugs were being run back to the software companies in real time, with the appraiser, AMC, lender and software provider working through the problem together.

The bigger problem in August was that lenders had barely begun ordering the 3.6 appraisals at all. Rocket Mortgage staff at Val Expo said they had ordered six UAD 3.6 appraisals. Rocket originates roughly six to seven percent of all residential mortgages in the United States. Several regional AMCs reported completing exactly two assignments apiece — and in each case, one of the two was a test run the AMC had ordered itself.

Scott Reuter, chief appraiser at Freddie Mac, summed up the bind on a panel at the show: “Appraisers cannot do a 3.6 assignment unless somebody orders a 3.6 assignment.”

More Than 900 Data Elements

There were approximately 190 data elements in UAD 2.6. There are now more than 900 in UAD 3.6. Reuter says it’s easy to be overwhelmed if appraisers just hear the number, but he assures the industry that appraisers were in the room when the form was developed.

“I want to make sure they don’t just hear ‘more than 900 elements’ and worry that they won’t be able to do it,” Reuter says. “They won’t have to fill out all those data points for every property. They are never going to touch the lion’s share of them, but we wanted to make sure we accounted for every potential contingency just in case.”

Lyle Radke, senior director of collateral policy at Fannie Mae, says Fannie and Freddie hold, between the two of them, $7 trillion in mortgage debt which, since it’s backed by the U.S. Treasury, is guaranteed by U.S. taxpayers. Therefore, it stands to reason collecting more data than before is important.

“From that perspective, the data is essential,” Radke says. “It’s how we manage risk. UAD 3.6 makes it easier for us to see and understand the data. If we didn’t have 3.6, we could still parse the data, but it would be much more challenging and time consuming.”

Other topics include turn times, liability and fees.

As the industry rushes toward the Nov. 2 deadline, appraisers’ stress levels will continue to rise. The only question is: What will things look like when the smoke clears? Only time will tell.

To read more, Click Here

My comments: Good discussion of the issues with quotes from many people, including GSEs. Not many changes since the August conference, except software vendors are still sending out updates. Fees still unclear.

——————————————————–
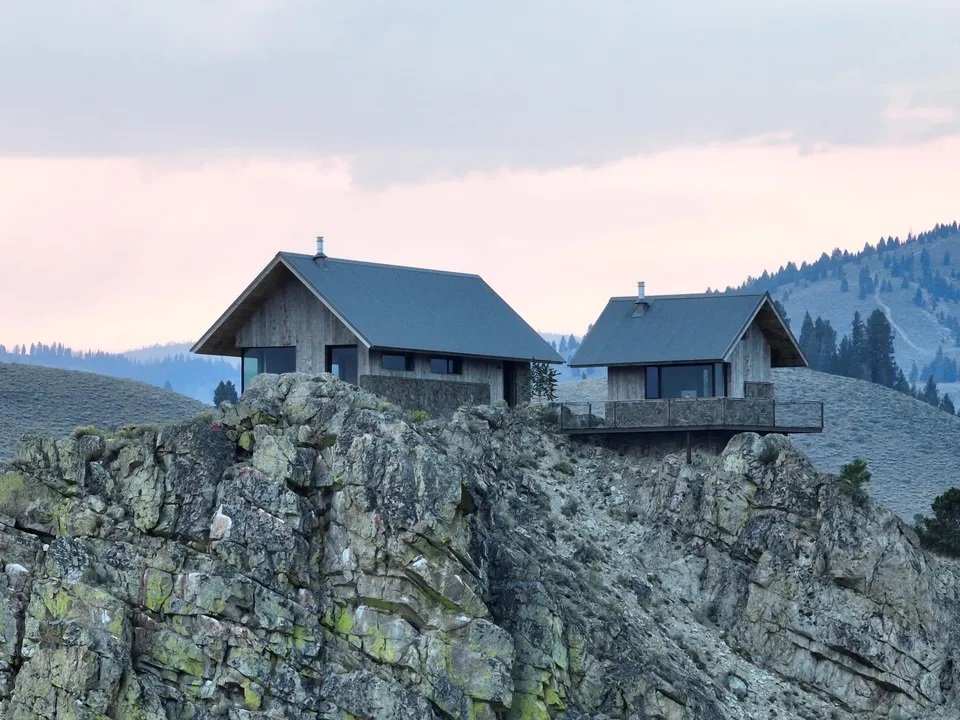
A Clifftop Compound With 2 Brand-New Cabins in Idaho Hits the Market for $2,299,000

Excerpts: 1 bedroom, 1 bath, 306 sq.ft., 3.06 Acre lot, Built in 2026

It’s all about location, location, location for two newly built mountain cabins perched atop a cliff outcropping in Idaho that have just hit the market.

Located on 3.06 acres in Stanley, where “snowmobiling, hiking, and mountain biking adventures begin right outside your door,” The sleek residences are surrounded by sweeping views of the Stanley Basin, the Sawtooth Mountains, Valley Creek, and the Salmon River. They come with “direct access to vast stretches of surrounding wilderness.”

A primary 900-square-foot cabin features a vaulted wood ceiling, wood-burning stove, heated flooring, modern kitchen, full bathroom, and sleeping loft.

The secondary structure has a loft and wraparound deck. It also offers flexible space that could be used for guest accommodations, a studio, home office, or fitness center.

Just minutes from downtown Stanley, the gated property also borders 465,000 acres of National Forest land.

To see the listing with 45 photos and an aerial view, Click Here

——————————————————–

What Is Highest and Best Use in Appraisal? (Updated for UAD 3.6)

By Kevin Hecht

Excerpts: What’s New: Fannie Mae’s HBU Policy Under UAD 3.6

For residential appraisers, highest and best use is more than a valuation concept. It is also a GSE eligibility requirement, and in September 2026, Fannie Mae changed it.

In Selling Guide Announcement SEL-2026-08, Fannie Mae updated its HBU policy for appraisals completed on the redesigned Uniform Residential Appraisal Report (URAR) under Uniform Appraisal Dataset (UAD) 3.6.

What Changed

Residential use, not present use. Under the prior guidance, the present use of the property generally had to be its highest and best use. Now the property’s HBU, as improved or as proposed, must be a residential use. It no longer has to be the present use.

Primarily residential 1-4 unit properties. The property must be primarily a one- to four-unit residential property, and any non-residential use must be subordinate to the residential use. This replaces the earlier “residential in nature” standard. Fannie Mae’s UAD 3.6 Policy Supplement defines present use, residential use, and subordinate use for this purpose.

A path for properties that fail an HBU test. The update sets eligibility criteria and reporting requirements for one- to four-unit residential properties whose present use fails one or more of the four HBU tests.

When It Applies

The policy applies to appraisals completed on UAD 3.6. It does not apply to appraisals completed on the legacy forms. As of November 2, 2026, UAD 3.6 is required for new submissions to the Uniform Collateral Data Portal (UCDP), so most Fannie Mae appraisals now fall under the new policy.

Some lenders have more time. Under a temporary exception announced September 30, 2026, approved sellers that requested it from Fannie Mae or Freddie Mac can keep submitting UAD 2.6 appraisals on the legacy forms through May 19, 2027. UAD 3.6 becomes mandatory for everyone on May 20, 2027. Until then, you may get assignments in both formats. The new HBU policy applies only to UAD 3.6 reports, so confirm your client’s UAD requirements before you accept an assignment.

Freddie Mac has not made the same HBU change. As of its September 2026 guide update, Freddie Mac still requires the present use to be the highest and best use. Because the two GSEs now differ, confirm with your client which guidelines apply when the present use is not the HBU.

What It Means in Practice

Consider an older single-family home on a lot that was recently rezoned for townhomes. The existing house may no longer be the maximally productive use of the site. Under the old approach, that conflict could raise an eligibility problem. Under UAD 3.6, the HBU is still residential, so the property may remain eligible if it meets Fannie Mae’s criteria and the appraisal reports the analysis as required.

The redesigned URAR also puts more weight on narrative, evidence-based support for the HBU conclusion than the legacy forms did. Be ready to explain why the market supports a residential use, whether any non-residential use (such as a home-based business or agricultural outbuildings) is subordinate, and, when the present use fails a test, which test it fails and why.

For exact definitions and reporting requirements, read the UAD 3.6 Policy Supplement.

Topics also included:

Many general HBU topics.

Survey: What’s the Most Common Error Appraisers Make When Performing an HBU Analysis?

To read more, Click Here

My comments: THIS IS A SIGNIFICANT HBU CHANGE ONLY FOR UAD 3.6!

My November 2026 Appraisal Today issue has a long article about Fannie’s HBU changes written by Denis Desaix, MAI, SRA, a HBU expert.

After reading Denis’ detailed article, I had difficulty understanding what has changed and what it means. The Playbook (below) helped me significantly.

Be sure to read these documents:

MOST IMPORTANT DOCUMENT

The Highest and Best Use Playbook – An excellent presentation of the “big picture” for this New HBU requirement for UAD 3.6

https://singlefamily.fanniemae.com/media/47851/display

—————-

Highest and Best Use Frequently Asked Questions

https://singlefamily.fanniemae.com/media/48061/display

—————————————————————–

UAD 3.6 Policy Supplement

https://singlefamily.fanniemae.com/media/42571/display

—————————————————————-

Why did Fannie do this?

To make more properties eligible for Fannie mortgage loans. No more clicking the NO box for conforms to HBU requirements. UAD 3.6 does not have a No box. Today, in many areas, there are few homes available for purchase with high prices.

——————————————————–

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.

To read more about the 4 ways, plus information on why I take ads, etc. Click here

——————————————————–

Enough of UAD 3.6, I Have a Business to Run!

Revenue Strategy: Managing the Business (Part 1)

By Doug Smith, MBA, SRA

In the November 1, 2026 issue of Appraisal Today

Excerpts:

“A time of turbulence is a dangerous time, but its greatest danger is a temptation to deny reality.” – Peter F. Drucker

The transition to UAD 3.6 is proving to be one of the most disruptive

changes many appraisers have experienced in their professional careers.

What initially appeared to be a change in reporting requirements has become a far more extensive transformation of the appraisal process.

Established workflows are being reconsidered. Familiar software

procedures are changing. New equipment, training, and additional expenditures may be required. Even experienced appraisers are discovering that the time and effort needed to complete an assignment may no longer resemble what they have come to expect.

The full economic consequences remain uncertain. But one thing is

becoming clear: That realization presents an opportunity.

Rather than concentrating exclusively on adapting our reports, perhaps this

is the appropriate time to reconsider something more fundamental: What do we want from our careers as professional appraisers?

Peter Drucker encouraged organizations to begin with a fundamental

question: What is our mission?

For appraisers, the answer must recognize our responsibility to the public

trust. Our work supports decisions by people and institutions relying on credible opinions of value. Our professional obligations extend beyond satisfying the company ordering the appraisal.

We are appraisers. Our responsibility is to analyze real estate markets,

interpret market evidence, and develop credible opinions of value.

Our primary purpose is not to make a software program work.

To read more about this topic in Part 2, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.

If this article helped you understand your business better, it is worth the subscription price!

—————————————————————-

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

——————————————————–

UAD 3.6: A New Era of Accountability in Appraisal Quality

October 26, 2026

By Gynell Vestal (Administrator) American Valuation Society

How standardized appraisal data could transform secondary market risk management, lender oversight, and the future of appraisal development.

Excerpts: What happens when the secondary mortgage market can evaluate appraisal quality with a level of consistency, transparency, and sophistication that wasn’t previously possible at scale?

I believe this is where UAD 3.6 has the potential to fundamentally change the valuation industry.

Not simply by changing how appraisals are reported, but by creating greater accountability throughout the entire valuation process, from the secondary market to lenders, AMCs, and ultimately the appraiser developing the opinion of value.

The Real Significance of Standardized Appraisal Data

UAD 3.6 is fundamentally a reporting standard. It doesn’t change the principles of appraisal development or the appraiser’s responsibility to produce a credible opinion of value.

What it changes is how appraisal information is structured, communicated, and made available for analysis.

Historically, appraisal reports have contained a significant amount of narrative information, often presented with varying levels of detail and consistency. While lenders and secondary market participants have long employed automated collateral review tools, the limitations of legacy reporting formats have constrained how comprehensively certain appraisal information can be analyzed across large volumes of reports.

UAD 3.6 introduces a more structured, standardized dataset that creates opportunities for increasingly sophisticated automated analysis.

And that has implications far beyond the appraiser’s reporting software.

Structured data can make it easier to identify inconsistencies, evaluate reported property characteristics, compare appraisal information against external datasets, and flag potential deficiencies for further review.

As analytical technology and artificial intelligence continue to advance, these capabilities can become even more powerful.

But the real significance isn’t simply that more appraisal data can be analyzed.

It’s who can analyze it, how consistently it can be evaluated, and what happens when weaknesses are identified.

The Secondary Market: Where Accountability Begins

Consider the implications for the government-sponsored enterprises and other secondary mortgage market participants.

Their exposure to collateral risk makes the quality of the underlying appraisal an important component of mortgage risk management.

With more standardized and machine-readable appraisal data, secondary market participants have an opportunity to enhance their existing review systems, develop more sophisticated risk indicators, and identify potential appraisal deficiencies with greater consistency.

Rather than relying primarily on individual report reviews or limited automated checks, increasingly advanced analytical systems can evaluate patterns across large volumes of appraisal data.

Additional topics

  • The Accountability Effect: From Secondary Market to Lender
  • As the secondary market becomes better equipped to evaluate valuation risk, lenders have a stronger incentive to strengthen the quality-control processes that identify and address those risks before loan delivery.
  • That accountability will naturally extend to the valuation service providers supporting those lenders.

What This Means for AMCs and Appraiser Performance

A Changing Landscape for Appraiser Panels

There’s another development worth considering, particularly from the lender and AMC side.

UAD 3.6 is already creating opportunities for appraisers who prepared early for the transition.

We Cannot Simply 2.6 the 3.6

I’ve been thinking about this distinction between reporting and development for some time.

UAD 3.6 changes the way appraisal information is reported, but the principles of credible appraisal development remain the same.

Appraisers must still identify and analyze relevant market data, select appropriate comparable properties, develop supportable adjustments, and reconcile their findings into credible opinions of value.

Better Data Must Lead to Better Quality Control

The Next Chapter of Appraisal Quality

The secondary market can use standardized data to strengthen valuation risk analysis. That creates greater accountability for lenders, which in turn creates stronger incentives for meaningful appraisal quality control and AMC oversight. Ultimately, those expectations reach the appraiser and the quality of the underlying appraisal development.

This accountability already exists in various forms. UAD 3.6 creates an opportunity to make it more consistent, more data-driven, and potentially more effective.

The real promise of UAD 3.6 isn’t simply a more modern appraisal report.

It’s the possibility of a valuation ecosystem in which better data supports better risk management, stronger accountability, and greater recognition of credible appraisal development.

That’s the opportunity I believe the industry should be preparing for.

To read more, Click Here

My comments Definitely worth reading. I had never read about this topic or even knew about the topic. Appraisers often forget about the lender side of UAD 3.6 and all lender appraisals.

——————————————————–
Flock Camera Blunders and the Privacy Risks of UAD 3.6

By Desiree Mehbod

A shocking Flock camera mistake triggered a midnight police raid on an innocent mother, exposing the dangerous reality of automated data overreach heading our way under UAD 3.6.

Excerpts: The Richmond police department just handed real estate appraisers the ultimate warning story about the dangers of automated data and algorithmic overreach. On July 29th, just before two in the morning, Richmond police officers woke up Rosalyn Crump, a mother of three, and towed her 2012 Hyundai Elantra right out of her driveway over a shooting she had absolutely nothing to do with.

The justification for this midnight raid was a hit from a Flock safety license plate reader camera. Body camera footage later revealed that officers walked up to the car, shined flashlights through the glass, and noticed children’s car seats buckled into the back.

The homeowner came outside and explicitly told the officers they had the wrong car, explaining her exact timeline for the day and the fact that the vehicle had been sitting idle. Instead of using human logic, looking at the physical evidence, or listening to the homeowner, an officer decided her story did not match the machine’s data and declared on camera that she was definitely not telling the truth.

We are watching a dangerous cultural shift where institutional systems place blind faith in digital data repositories while completely discarding human expertise and physical reality. In the Richmond towing case, a computer screen told an officer that a vehicle was involved in a crime, and that digital output instantly overrode the physical presence of children’s car seats and a mother’s direct testimony.

Appraisers are being forced into a parallel trap under the new UAD 3.6 data demands. Fannie Mae and Freddie Mac are demanding that we sweep through private residential spaces, capturing high-resolution interior photographs of bedrooms, living areas, hallways, and security setups, and then funnel that data into centralized, standardized databases accessible to unknown third parties.

When appraisers object to signing Certification 25, which strips away our core confidentiality defense and allows this private property data to be aggregated, corporate pragmatists tell us we are being dramatic. They claim the data is secure and meant only for secondary market functions.

But the Richmond incident proves that once a massive, standardized digital database exists, it will inevitably be hooked up to automated scanning tools and surveillance networks.

To read more, and watch the video of the encounter (near the bottom of the article)

To read more, Click Here

My comments: Worth reading. I had never thought (or read about) this aspect of UAD 3.6 increased data availability. Scary.HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down in 2026.

—————————————————————————

Mortgage applications increased 3.4 percent from one week earlier

WASHINGTON, D.C. (October 28, 2026) — Mortgage applications increased 3.4 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 23, 2026.

The Market Composite Index, a measure of mortgage loan application volume, increased 3.4 percent on a seasonally adjusted basis from one week earlier. On an unadjusted basis, the Index increased 3 percent compared with the previous week. The Refinance Index increased 3 percent from the previous week and was 61 percent lower than the same week one year ago. The seasonally adjusted Purchase Index increased 4 percent from one week earlier. The unadjusted Purchase Index increased 3 percent compared with the previous week and was 18 percent lower than the same week one year ago.

“Mortgage rates declined for the second week in a row, with the 30-year fixed rate decreasing to 7.37 percent, the lowest in three weeks. The decline in rates gave borrowers some relief, with applications rebounding slightly, particularly conventional applications,” said Joel Kan, CMB, MBA’s Vice President and Deputy Chief Economist.

“Mortgage rates are still more than a percentage point higher than the same week last year and most homeowners still have rates much lower than prevailing market rates. The ARM share of applications increased to 11.3 percent, the highest level in more than a year, as more borrowers applied for ARM loans to lower their monthly payments.”

Added Kan, “While purchase applications increased over the week, they were 18 percent behind last year’s pace as many homebuyers have put their purchase plans on hold. Similarly, refinance applications were down more than 60 percent from a year ago, as most borrowers have little to gain from refinancing.”

The refinance share of mortgage activity decreased to 38.9 percent of total applications from 39.0 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.3 percent of total applications.

The FHA share of total applications increased to 16.6 percent from 16.3 percent the week prior. The VA share of total applications decreased to 11.0 percent from 11.5 percent the week prior. The USDA share of total applications remained unchanged at  0.5 percent from the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.37 percent from 7.41 percent, with points increasing to 0.76 from 0.75 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.28 percent from 7.33 percent, with points increasing to 0.64 from 0.60 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.12 percent from 7.13 percent, with points decreasing to 1.07 from 1.15 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The average contract interest rate for 15-year fixed-rate mortgages decreased to 6.70 percent from 6.73 percent, with points increasing to 0.85 from 0.73 (including the origination fee) for 80 percent LTV loans. The effective rate remained unchanged from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.41 percent from 6.46 percent, with points increasing to 1.20 from 1.11 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

———————————————————–

Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
UAD 3.6 Fees for Appraisers

Newz: UAD 3.6 Fees, Fun Appraiser Game, Who Can Get Your Appraisal Data?

October 16, 2026

ARTICLE LIST – In order, Scroll down the page to read

  • LIA AD: Problem with An Affidavit
  • UAD 3.6 and the Appraisal Fee Chain: Who Actually Sets the Fee?, By Doug Smith, SRA
  • Lots Under Water
  • Certification 25: The 20-Year Fight Over Who Gets to Use Your Data, By Isaac Peck, WorkingRE, Publisher
  • Appraiser Game – Something FUN, By Dustin Harris
  • MY AD: 2026 E&O Update – Claims, Payment Options, Lawsuits, Etc
  • Inspectors Blocked the Door, Appraisers handed over the Keys By Desiree Mehbod
  • MBA STATS: Mortgage applications decreased 2.7 percent from one week earlier


Thanks to our Sponsor!!!

——————————————————-

UAD 3.6 and the Appraisal Fee Chain: Who Actually Sets the Fee?

By Doug Smith, SRA

“…the higgling and bargaining of the market…”

— Adam Smith, The Wealth of Nations, 1776

There has been considerable discussion about appraisal fees as UAD 3.6 is implemented. Much of the criticism over resistance to fee increases has been directed at Appraisal Management Companies.

But before deciding where responsibility lies, perhaps we need to follow what might be called the appraisal fee chain.

It begins with the borrower

A consumer seeking to purchase or refinance a residence provides information to a lender. The familiar conventional mortgage application is the Uniform Residential Loan Application (URLA), also known as Freddie Mac Form 65/Fannie Mae Form 1003.

For federal mortgage disclosure purposes, an application is considered received once the lender has six pieces of information: the consumer’s name, income, Social Security number, property address, estimated property value, and desired loan amount.

Once those items have been received, the lender generally must provide a Loan Estimate within three business days.

That Loan Estimate includes estimated loan and closing costs, including the anticipated cost of an appraisal when one is required.

This is where the appraisal fee chain gets interesting.

Federal disclosure rules limit how much certain estimated charges can increase between the Loan Estimate and closing. Depending on the circumstances, some required third-party service charges may be subject to a 10% cumulative tolerance, while others are subject to different rules. A valid changed circumstance may also permit a revised Loan Estimate.

So here is the first question:

Does the appraisal amount initially disclosed to the borrower influence the fee that can later be offered to the appraiser?

Once the borrower indicates an intent to proceed, the appraisal ordering process moves forward. Depending on the lender’s business model, the appraisal may be ordered directly from an appraiser or through an AMC.

Eventually, an assignment reaches an appraiser with a proposed fee.

But where in the appraisal fee chain was that number actually established?

Was it established by the lender when estimating the cost of the loan?

Was it established through an existing agreement or fee schedule between the lender and AMC?

Does the AMC determine the fee it offers the appraiser?

For lenders ordering directly, are they expecting UAD 3.6 assignments to be completed for the same fees previously paid for UAD 2.6 assignments?

And when an appraiser responds that the proposed fee is inadequate, how far back up the appraisal fee chain does that information travel?

These questions matter because UAD 3.6 changes the appraisal product and, for many appraisers, the process required to produce it. Appraisers are investing in training, software and equipment. Inspection procedures and data collection are changing. During the transition, the time required to complete an assignment may change as well.

Yet much of the current discussion seems to begin with the assumption that the appraisal fee should remain where it was.

Perhaps the question should not simply be, “Why won’t AMCs increase appraisal fees?”

The better question may be:

Where in the appraisal fee chain is the price of a UAD 3.6 appraisal actually being established—and is there still room for the market to establish a different price?

Nearly 250 years ago, Adam Smith described part of that price-setting process as the “higgling and bargaining of the market.”

Appraisers are participants in that market too.

A proposed fee is a proposal, not necessarily the market price.

Perhaps it is time for a little more higgling and bargaining.

My comments: I had never known about this before. Thanks to Doug Smith for the info!

Read more!! →

Defending Adjustments for Appraisers

Newz:  GSEs Request Feedback on UAD 3.6, Defending Adjustments

September 4 , 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Too Late for a Reconsideration of Value
  • How to Defend Adjustments in Appraisal Reports
  • $112 Million Laguna Beach Mansion With a Private Library and a Rotating Bed in Primary Suite Could Become Priciest Home Ever Sold in Orange County
  • GSEs Request Appraiser Feedback on UAD 3.6
  • MY AD: How AI Can Help Residential Appraisers and Why Appraisers Will Always be Needed By By David Galatto
  • First the Borrower Fee. Now the Appraiser Compensation in Court By Kenneth J. Mullinix
  • The part of the process appraisers never see, and the reason your file keeps coming back
  • UAD 3.6 UPDATE – Inspection Checklist, New Survey: UAD 3.6 mandate is Nov. 2nd. Are you ready for it?,
  • MBA STATS: Mortgage applications increased 0.8 percent from one week earlier

————————————————————————–

How to Defend Adjustments in Appraisal Reports

When someone questions an adjustment, many appraisers respond, “It’s based on market data” or “my experience in the market.” These statements might be true, but they don’t support the adjustment. They just state where it came from.

Appraisal reports are similar to scientific papers. A scientist can’t write “Based on my experiments, the hypothesis is correct” and expect peer review to accept it. Scientists need to share their methodology, summarize their analysis, and support their conclusions.

The same applies to appraisal adjustments. Saying you used market data is like saying you conducted an experiment. It’s just the starting point. Your report needs to summarize how you analyzed the data and how it supports that specific adjustment.

Without this documentation, you haven’t provided credible analysis. You’ve stated an unsupported opinion, regardless of your experience.

You need a clear path from market evidence to the number on your grid. Defending appraisal adjustments isn’t one perfect technique. It’s about using multiple, credible methods, explaining your logic, and sequencing your work so it aligns with how the market behaves and with USPAP.

Below is a practical, step-by-step approach you can put to work right away.

Start with the Right Sequence

Before you calculate any adjustment, get the order right. In practice, you should follow this sequence:

  • Apply transactional adjustments:
  • Real property rights conveyed
  • Financing terms
  • Conditions of sale
  • Expenditures made after purchase
  • Market conditions (time)
  • Apply property adjustments:
  • Location
  • Physical characteristics (e.g., finished square footage, bathrooms, garages, condition, quality)

Transactional adjustments affect the overall transaction price, and each adjustment creates a new base for the next one. They answer the question, “What would this comparable have sold for under typical terms on my effective date?”

These adjustments normalize the sales by removing distortions from unusual financing, non-market conditions, or time differences.

Equalize Market Conditions Before You Compare

Read more!! →

Surplus vs. Excess Land for Appraisers

Newz: Surplus vs. Excess Land,
Easement Issues and Liability

August 14, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Easements: Issues and Appraiser Liability
  • Surplus Land vs. Excess Land: What Appraisers Need to Know, By Kevin Hecht
  • Built Different: How the Ranch-Style Home Went from 1930s Architectural Rebel to America’s Favorite Floor Plan
  • Let’s Talk About Letters of Engagement, By Jeff Whaley
  • MY AD: UAD 3.6 Software Evaluation Checklist
  • An Abridged History of the Appraiser Profession, By Kendra Budd, Editor Working RE
  • My UAD 3.6 Tips of the Week
  • MBA: Mortgage applications increased 3.6 percent from one week earlier

———————————————————

Surplus Land vs. Excess Land: What Appraisers Need to Know

By Kevin Hecht

Excerpts: Land valuation is a fundamental aspect of real estate appraisal, influencing property transactions, development decisions, and investment strategies. A key part of the process involves distinguishing between the land that supports the property’s current use and any additional land that may or may not have independent value.

Commonly, a square footage adjustment is made based on lot size differences among comparable properties without one key distinction: whether the difference in land is surplus or excess land. This fails to consider whether the extra land has value independent of the subject property.

Surplus land generally does not contribute value beyond its association with the primary parcel, though it may still add some contributory value in certain market conditions. Excess land, by contrast, has value because it can be divided and sold separately.

Understanding this distinction is essential for developing a credible appraisal.

Surplus Land vs. Excess Land at a Glance

Surplus Land – Cannot be separated and sold independently

Excess Land – Can be divided and sold separately

Surplus Land – No independent highest and best use

Excess Land – May have a different highest and best use

Surplus Land – Typically contributes limited additional value

Excess Land – Has independent value and should be analyzed separately

Surplus Land – Remains part of the primary property

Excess Land – Can potentially support separate development

Key Differences Between Surplus and Excess Land

Surplus and excess land apply to commercial and residential properties. Before determining whether land is surplus or excess, appraisers must consider zoning, highest and best use, surrounding properties and their use, property improvements, and supply and demand for the property and any proposed improvements.

Why the Distinction Matters in Appraisal

Choosing the correct land type has an effect on the final value of the property. Excess land adds value to the subject property and creates future potential. Thus, a higher price per square foot should be assigned to excess land over surplus land.

Ultimately, identifying land type is about more than just checking if a property can be split. It’s about understanding the property’s most productive use under current legal and economic conditions.

To read more, Click Here

My comments: Read this article!! The best comprehensive article I have read on this issue. Understanding Surplus vs. Excess Land is critical in appraising. I have encountered this issue mostly in commercial and agricultural appraisals. It can happen in any type of property.

Unfortunately, residential lender appraisers sometimes encounter this but don’t know much about it. I have appraised it on single family properties. Not understanding what this is of the many ways residential appraisers end up trouble at the state appraisal board because of lack of knowledge and experience.

Read more!! →

AQB Exposure Draft Removes College Degree Requirement

Newz: Appraisal Stress Test, AQB Exposure Draft Removes College Degree Requirement

June 26, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: State Board Complaint Frustrations
  • The Appraisal Profession Is Being Stress-Tested. That’s Not the Same as Being Replaced By Jessica Sturm
  • All About the Brownstone: How the Iconic Design Went From Humble Row House Roots to Million-Dollar Metropolis Luxury
  • MY AD: UAD 3.6 Software Evaluation Checklist By Doug Smith
  • Include E&O in Appraisal Reports? Just Say No By Isaac Peck
  • AQB second exposure draft removes college degree requirement
  • MBA STATS: Mortgage applications increased 1.0 percent from one week earlier     
  • ———————————————————


The Appraisal Profession Is Being Stress-Tested.

That’s Not the Same as Being Replaced

A frank conversation about UAD 3.6, waiver expansion, and where the real opportunity lies.

By Written by : Jessica Sturm, EVP of Property Services at Opteon.

Excerpts:

What UAD 3.6 Actually Changes (And What It Doesn’t)

UAD 3.6 changes the infrastructure around how appraisal judgment is captured, structured, and delivered. It does not change what a great appraiser does and the value they bring. Your ability to walk a property and know, as a trained professional, that the finished basement wasn’t permitted, that the kitchen renovation was done on the cheap or that the comparable three streets over sold under pressure. None of that local, industry expertise lives in a data schema.

What the new standard demands is that the mechanics around that judgment are handled cleanly and consistently. Field data capture, structured commentary, condition ratings, quality flags, all in a format that downstream systems can use. That’s not a threat to expertise. We see this as a long-overdue investment in the infrastructure that supports our industry.

What the Stress Test Is Really Asking

Every industry stress test asks the same question: who is built for what comes next?

UAD 3.6 is asking whether the profession can operate with greater rigor and efficiency. Waiver expansion is asking whether appraisers can own the complex, high stakes, advisory end of the market with real authority. The mature appraiser pipeline is asking whether the profession can retain experience and retrain while bringing in and developing new people. These are hard questions, but the profession has more tools, more data, and more support to answer them than at any point in its history.

Accounting faced the same reckoning. When tax software arrived and then matured, the prediction was that it would hollow out the profession. Routine compliance work did automate and what happened next was the opposite of collapse.

To read more, Click Here

My comments: Interesting analysis. I think the new reports are much better than the old forms for reviewers and borrowers. If I was doing GSE appraisals I would look forward to doing them.

Read more!! →

Recent Executive Orders Affecting Appraisers

Newz: Recent Executive Orders Affecting    Appraisers, When Appraisers Take the Stand

June 12, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: A case of forgery
  • Recent Executive Orders: Threat, Opportunity, or Both for Appraisers? By Kim Perotti, AXIS AMC
  • $22.8 Million Aspen Home With Its Own Private Waterfall Feels Like a Real-Life Fairy Tale
  • MY AD: If the Standards Are Uniform, Why Isn’t Your License? By Thaddus Dawson, Jr., CG
  • When Appraisers Take the Stand By By David C. Wilkes, Esq., CRE, FRICS and Kevin M. Clyne, Esq., CRE
  • Agents, Are You Using AI to Price Your Listings? By Tom Horn
  • 10K Appraisers. Policy and Advocacy Day, By 10K Appraisers Foundation
  • MBA: Mortgage applications increased 10.8 percent from one week earlier

Recent Executive Orders: Threat, Opportunity, or Both for Appraisers?

By Kim Perotti, a founding partner of AXIS AMC

Excerpts: In March 13, 2026, President Trump signed two Executive Orders that together amount to a clear message for our profession: build more houses, make credit easier, and get the valuation piece done faster and cheaper. We think it’s critically important that our industry discuss the implications.

The two orders are:

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION

AND PROMOTING ACCESS TO MORTGAGE CREDIT

While they are not “about” appraisers, the Executive Orders will absolutely reshape the environment in which we work. Appraisers who treat these as background noise will find the ground shifting under their feet. Those who read them as a roadmap can pick their spots and come out stronger and, more importantly, help shape how they are put into practice.

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION:

Faster, Cheaper Construction – What That Really Means for Your Desk

PROMOTING ACCESS TO MORTGAGE CREDIT: Faster, Cheaper Valuations – Where the Squeeze Shows Up – Second Order

The second order takes direct aim at how loans—and valuations—get done. The theme is unmistakable: streamline, digitize, and de-emphasize technical compliance.

For appraisers, here are the potential realities:

More alternative valuation products: Regulators are being encouraged to expand the use of AVMs, desktop, and hybrid appraisals and reduce full appraisal requirements on low-risk and small-balance loans. You should expect more hybrid and desktop requests and data-only products as well as a clearer dividing line between high-volume, low-margin work and complex, higher-risk assignments.

Pressure on fees and turn times: Agencies are being asked to set “clear appraisal timelines” and cut costs and therefore lenders will likely lean harder on speed and price whenever a waiver, AVM, or hybrid is allowed, and traditional assignment ordering will have to justify itself on risk grounds.

Changes in who can appraise and how: The order invites simplification of appraiser qualification requirements. Easier entry could mean more competitors and lenders may fill low-fee niches with less-experienced personnel or non-traditional vendors.

If your business is built primarily on simple, low-risk assignments, this is a direct competitive challenge.

Alignment of FHA and VA rules: HUD and VA are asked to align standards where risk is comparable, clarify what truly requires pre-closing repairs vs. what’s cosmetic, and expand post-closing repair flexibility.

That could change the frequency and scope of “subject to” conditions, reduce some friction and disputes around FHA/VA appraisals, and make your judgment about safety vs. cosmetic issues more visible and important.

In summation, this order calls for more technology and alternatives, more pressure on traditional appraisals, and more segmentation of valuation products by risk level.

A Clear Fork in the Road for Appraisers

Taken together, these two Executive Orders point in one direction: more volume, more complexity at the edges of the market, and more pressure to commoditize anything that looks “low risk.” Together they create a fork in the road for real estate appraisers:

If you stay in the lane of interchangeable, low-complexity assignments, you will feel the squeeze—from technology, from relaxed standards, and from new entrants.

If you lean into complexity—new construction, manufactured and modular, fringe markets, environmental and hazard issues, FHA/VA nuance—you become harder to replace, not easier.

This doesn’t mean abandoning efficiency or refusing alternative products. It means being fluent in hybrids and desktops so you can decide which work makes sense for you, positioning yourself as the expert when a lender can’t responsibly rely on an AVM or a waiver, and building documented expertise in the exact areas these orders will expand.

To read more, Click Here

My comments: Definitely worth reading. All about what this means for appraisers in detail. The best analysis for appraisers I have read about this executive order. The author is definitely an “insider” as she is Co President of AXIS, a long time AMC. When I wrote one of my first articles on AMCs, I interviewed AXIS.

Read more!! →

24 Hour Appraisals

Newz: 24 Hour Appraisals, Bias Accusation Collapses, Easements and Appraiser Liability

May 15, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Easements and Appraiser Liability
  • 24-Hour Appraisals: The Future or a Gimmick? By Shawn Telford , Chief Appraiser and Valuation Officer at Cotality
  • $28 Million ‘Pavilion’ House in Los Angeles Boasts ‘Once-in-a-Generation’ Design—and a Sunken Conversation Pit
  • Freddie/Fannie UAD and Forms Redesign: Enhanced Timeline and Updated FAQs
  • MY AD: Appraisal forms software in September, 1993 – a glance at the past
  • AQB Releases White Paper on Experience Requirements
  • Bias Accusation Collapses as HUD Clears the Appraiser by Desiree Mehbod
  • MBA: Mortgage applications increased 1.7 percent from one week earlier


—————————————————————————

24-Hour Appraisals: The Future or a Gimmick?

By Shawn Telford , Chief Appraiser and Valuation Officer at Cotality,

Rethinking Quality and Risk in Modern Valuations: Why Faster Can be Risky

Excerpts: side from the opinion of value, speed is often the next loudest talking point in any conversation about appraisals—but it’s also one of the most misleading. While accelerated appraisal procurement models promise faster turn times, they do little to address the concerns that matter most to lenders: inaccurate valuations, which lead to appraisal defects that create buyback exposure and margin pressures for lenders, ultimately contributing to delays and additional costs.

This isn’t to say that the prospect of 24-hour appraisals is not appealing: after all, who doesn’t like faster? But is it a game-changer or merely a gimmick?

Today, lenders are facing greater scrutiny from the GSEs and investors over loan quality, in general, and collateral valuations in particular. Recently, Fannie Mae reported that collateral defects – like property damage, appraisal condition & quality rating inflation, and inappropriate comparable sale selection—are now accounting for nearly half of discretionary loan review defects. Solving for the Right Problems

Pressuring appraisers to work faster is hardly going to address these issues.

The Economic Impact of Quality

Getting an appraisal quickly can be a plus. But if the valuation requires extensive rework, it can create friction and delays and add operational costs to the underwriting process. One of the biggest slowdowns in the appraisal process is the back-and-forth between the appraiser and an AMC’s lender over administrative “corrections” that often don’t affect the opinion of value. In fact, recent Cotality data shows that nearly half of all appraisals are returned for some type of correction, and the vast majority of those returned do not have their value changed when resubmitted.

To read more, Click Here

My comments: very good analysis with many excellent comments. Very knowledgeable author. Worth reading.


Read more!! →

The Appraiser Exodus and How to Fix It

Newz: Expanded Intended Users?

The Appraiser Exodus and How to Fix It.

May 8, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Expanding Intended Users? Not So Fast
  • Under Pressure: What’s Driving the Appraiser Exodus and How to Fix It, By David Massey
  • Historic Tudor Estate With English Gardens and Prairie Views Is Listed for $4.7 Million Near Chicago
  • What is a Pre-listing appraisal? Written for Home Owners But Has Good Tips for Appraisers, By Tom Horn
  • MY AD: What Happened When Government Decided That Appraisers Needed Protection, By Cindy Chance, PhD
  • How to See the Potential in Homes That Don’t Look Perfect. Written for Home Owners But Has Good Tips for appraisers
  • More Than 60% of America Is Covered by Drought and Millions of Homes Are at Risk
  • UAD 3.6 Bootcamp, LIVE in Chicago, IL and on Zoom, Wednesday – Friday, May 13th-15th
  • MBA STATS: Mortgage applications decreased 4.4 percent from one week earlier


——————————————————————-

Under Pressure: What’s Driving the Appraiser Exodus and How to Fix It,

By David Massey

Ask any veteran appraiser or physician what has changed most over the past twenty years, and the answer is usually the same: paperwork.

Professions once centered on skill, judgment, and service are now dominated by portals, compliance layers, and third-party control. Burnout rises, independence falls, and a quiet exodus follows.

The American Medical Association reports that physicians now spend nearly two hours on documentation for every hour of patient care.

The appraisal profession is now well into that cycle.

According to the Appraisal Institute’s 2023 Fact Sheet, the number of practicing appraisers in the United States has declined by roughly 8,000 in recent years. The Conference of State Bank Supervisors shows a longer-term drop from about 120,000 appraisers in 2008 to fewer than 96,000 by 2017, a 21 percent decline in less than a decade. IBISWorld reports another six percent employment drop between 2018 and 2023. The U.S. Bureau of Labor Statistics projects only modest growth through 2034, far short of what is needed to replace retirees.

The pipeline is shrinking while demand remains steady.

The National Association of Realtors ® 2023 Appraisal Survey found that more than half of appraisers are now asked monthly, or more often, to complete assignments outside their normal geographic or property-type expertise. More telling, 54 percent cited Appraisal Management Companies as the single greatest challenge to their business. That statistic alone explains much of what has gone wrong.

When I started in this profession, appraisal centered on analysis, interpretation, and professional opinion. I studied neighborhoods, walked properties, and applied experience to market behavior. Today, much of the job revolves around compliance portals, redundant uploads, and layers of review by people who have never inspected a property.

AMCs were created after the 2008 crisis to protect appraiser independence. The idea made sense. The execution has failed. Today, borrowers commonly pay $600 to $700 for an appraisal, while the appraiser often receives about half of that after AMC fees. Turn times lengthen. Panel depth shrinks. Geographic competency erodes. And experienced appraisers quietly step away.

What was meant to reduce pressure has become a system of control. Communication between lenders and appraisers is filtered. Pricing is dictated by algorithms. Scope interpretations are issued by third parties removed from the field. Judgment is slowly replaced by checklist compliance.

Healthcare has already traveled this road.

A 2025 Annals of Internal Medicine study showed nearly five percent of U.S. physicians left clinical practice in a single year, driven largely by burnout and administrative burden. The American Medical Association reports that physicians now spend nearly two hours on documentation for every hour of patient care.

Appraisers now operate inside the same imbalance. More time formatting reports than analyzing markets. More time satisfying review protocols than developing defensible opinions. Judgment yields to process.

This is not a workforce inconvenience. It is a structural market risk.

The fix is not complicated, but it does require courage.

First, appraisal fee transparency must be mandatory. If a borrower pays $650 and the appraiser receives $325, both parties deserve to know. Transparency restores accountability and allows market forces to function.

To read more, Click Here

My comments: Worth reading, especially how to fix it. We all know what is happening to residential lender appraisers.

For doctors, corporate medicine has taken over. For example, primary care physicians are allowed only 15 minute visits with patients. Large insurance companies make it very difficult for patients to get the care they need by denying what the patient needs. Doctors don’t like it, plus the excessive paperwork.

I play pickleball with a retired doctor. He had to sell his medical practice as he was underbid on fees by large health insurance companies.

Read more!! →

Avoiding Court: A Common Sentiment Among Appraisers

Newz: Cyber Attack Risk for Appraisers,

Avoiding Court: A Common Sentiment Among Appraisers

May 1, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Avoiding Court: A Common Sentiment Among Appraisers
  • Cyber Insurance: Why It’s Time for Appraisers to Protect Themselves By Isaac Peck, Senior Broker at OREP.org
  • Electrochemist’s Exclusive Private Island Escape With 9-Hole Golf Course and Helipad Hits the Market in Florida for $89 Million
  • Hype Heretics – Twisting the narrative to create hype. By JoAnn Apostol
  • MY AD: What is a Good Appraiser?
  • April 2026 Housing Insights: A Market Searching for Stability, By Kevin Hecht, Appraiser and Economist
  • A new Scope of Work, By George Dell, MAI
  • MBA: Mortgage applications decreased 1.6 percent from one week earlier

————————R