Appraisal News and Business Tips

Blog

Basic Requirements For Appraisal Reports (Updated for UAD 3.6)

Newz: 3 Basic Requirements for UAD 3.6 Appraisal Reports, Good Facebook Page – UAD 3.6 Software

July 31, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Limiting Liability to Third Parties
  • The 3 Basic Requirements for Real Property Appraisal Reports (Updated for UAD 3.6) By Kevin Hecht
  • Bay Area’s wildest house lists at $899K and just hit the market for the first time
  • Am I Being Paranoid, or Is There Another Reason? By Richard Hagar, SRA – GSE data
  • MY AD: Residential appraisal forms from the 1960s to today
  • The Appraisal Fee Lawsuit AMCs Can’t Outrun
  • DATE CORRECTION ON CONFERENCES in last week’s email
  • Excellent Facebook Page for UAD 3.6 Software
  • MBA STATS: Mortgage applications decreased 6.4 percent from one week earlier
 

The 3 Basic Requirements for Real Property Appraisal Reports (Updated for UAD 3.6) By Kevin Hecht, SRA

Excerpts: As a real property appraiser, you rely on appraisal reports to communicate your opinion of value. One of the most important principles in USPAP is also one of the most misunderstood: forms are not reports.

Filling out a form properly and completely does not automatically mean your report is USPAP-compliant. The content of the appraisal report, not its form or format, determines compliance.

That distinction has never mattered more than it does right now.

The static forms appraisers have relied on for decades, including the 1004, 1073, 1025, and 2055, are being retired and replaced by a single, dynamic, data-driven reporting structure.

This shift does not change the three foundational requirements of USPAP Standards Rule 2-1. But it does change how you meet them. Understanding that distinction is critical to your compliance and your credibility in the new reporting environment.

TOPICS

What Are the Three Basic Requirements for an Appraisal Report?

Standards Rule 2-1(a): Clearly, Accurately, and Not Misleading

SR 2-1(a) builds on the ETHICS RULE requirement that your appraisal reports must not be misleading. You satisfy this requirement by making sure you “clearly and accurately set forth the appraisal.”

As the saying goes, you must tell the truth, the whole truth, and nothing but the truth.

Under the legacy form-based system, appraisers added context and explanation through a free-form General Addendum, which provided flexibility when a standard data field did not fully capture the nuances of a particular property or assignment.

Under UAD 3.6, that flexibility is now built directly into the report structure itself through section-specific commentary fields, which keeps all relevant analysis organized and immediately accessible to reviewers.

Standards Rule 2-1(b): Sufficient Information for Intended Users

What changes under UAD 3.6 is where and how you provide that sufficient information

Standards Rule 2-1(c): Disclosing Assumptions, Extraordinary Assumptions, Hypothetical Conditions, and Limiting Conditions

How UAD 3.6 Supports USPAP Compliance

Preparing for UAD 3.6: Practical Steps for Appraisers

To read more, Click Here

My comments: Comprehensive, well written and worth reading.

Read more!! →

Posted in: AMCs, Appraisal fees, GSEs, UAD 3.6
Fannie Appraiser Update

Newz: Fannie Appraiser Update, Kentucky Board Approves Increase in Licensing Fees

July 24, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Client Insists on Cost to Cure
  • Fannie Mae Appraiser Update, July 16, 2026
  • Glittering L.A Megamansion With ‘Dramatic’ 50-Foot Water Wall and Swim-Up Hits the Market for $88 Million
  • Kentucky Board Approves Significant Increase in Appraiser Licensing Fees
  • MY AD: Doug Smith’s tips on selecting UAD 3.6 software
  • Honoring Jan Bellas, Our Greatest Advocate
  • Where Does an FHA Appraisal End and a Home Inspection Begin? HUD Has an Opportunity to Clarify. By Shane White, SRA (REPRINT)
  • Upcoming National Appraisal Conferences in Las Vegas
  • MBA STATS: Mortgage applications increased 1.9 percent from one week earlier

————————————————————————–

Fannie Mae Appraiser Update

July 16, 2026

Get practical guidance to help you prepare for the Uniform Appraisal Dataset (UAD) 3.6 and Forms Redesign transition and stay current on updates that affect your work.

In this second Appraiser Update of 2026—and our 35th edition since launching in 2017—we’re sharing timely insights, policy updates, and resources to help you navigate industry changes and support your success.

In this issue, you’ll find:

Expert insights on key UAD 3.6 topics, including terminology updates, policy changes, unit counts, and more.

What Appraisal Management Company access to Collateral Underwriter® (CU®) means and how to navigate it effectively.

List of Topics

  • Changes to UAD language in 3.6
  •  Unit Count Differences in the Sales Comparison Grid
  •  UAD 3.6 Reports: Lessons Learned
  •  AMC Access to Collateral Underwriter

Sample Topic detail

Vet Comments for Accuracy and Necessity

Some of the most common problems we have seen in UAD 3.6 appraisal reports relate to inaccurate or unnecessary comments. Here are some actual cases that illustrate the issue:

Contradictory information: In the SCA grid, an appraiser correctly utilized the Comparable Weight field to state that Comp 1 was given most weight and Comps 2-3 were given less weight, but then the appraiser added a comment that “The final opinion of value has been weighted equally among comparable sales 1-3.” The contradiction between the information in the enumerated data versus the narrative comment is confusing to the reader and undermines the appraiser’s credibility. A more helpful and appropriate comment would explain why comp 1 merited the most weight.*

Repetitive information: Another common issue we have seen in UAD 3.6 reports is the appraiser repeating the condition rating (already stated in a defined data element) in the associated comment field.*

Outdated language: In another report, an appraiser commented in the Sketch Commentary field that “The GLA for the subject was derived by…” Of course, the term “GLA” or Gross Living Area has been replaced in UAD 3.6 with the term “above grade finished area” (see accompanying article in this newsletter), so the reference to GLA was a non sequitur and confusing to the reader.

*These cases illustrate the general principle that appraisers should not restate information already contained in the defined data elements.

To read more, Click Here

My comments: Definitely worth reading for excellent “how to” advice on UAD 3.6.

Read more!! →

Posted in: Fannie, FHA, UAD 3.6

Appraisal Provisions Included in the 21st Century ROAD to Housing Act

Newz: Road to Housing Act and Appraisals, Florida Class Action: AMCs and Appraisal Fees

July 17, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: State Board Complaints: Does It Mean the End of Your Coverage?:
  • Appraisal Provisions Included in the 21st Century ROAD to Housing Act
  • Bargain $139K Shipping Container ‘Retreat’ in Virginia Proves You Should Never Judge a Book by Its Cover
  • Appraiser Capacity, Updated June, 2026, Freddie Mac
  • MY AD: Is Expert Witness a Viable Alternative to GSE Work By Tim Andersen, MAI
  • Florida Class Action: What’s It Mean for Appraisers? by Isaac Peck, Publisher, Working RE
  • Where Does an FHA Appraisal End and a Home Inspection Begin? HUD Has an Opportunity to Clarify. By Shane White, SRA
  • MBA: Mortgage applications decreased 2.7 percent from one week earlier


———————————————–

Appraisal Provisions Included in the 21st Century ROAD to Housing Act

Appraisal Institute News Release, June 26, 2026

Editor’s Note: This is Now a Law.

Excerpts: The recently passed 21st Century ROAD to Housing Act (H.R. 6644), now awaiting Presidential signature, includes two appraisal-focused measures supported by the Appraisal Institute: the Appraisal Industry Improvement Act and the Appraisal Modernization Act. Together, these provisions represent the most significant federal appraisal legislation enacted in several years and address workforce development, regulatory oversight, consumer protections, and appraisal modernization.

Appraisal Industry Improvement Act

The Appraisal Industry Improvement Act contains several provisions designed to strengthen the appraisal profession, modernize oversight, and expand pathways into appraisal practice.

Topics include:

  • Strengthening the Appraisal Subcommittee
  • Entry into the Profession
  • Expanded FHA Appraiser Eligibility and Training Requirements
  • The legislation would allow both state-certified and state-licensed residential appraisers to perform FHA appraisals
  • Appraisal Modernization Act primarily on consumer protections and appraisal transparency.
  • Reconsideration of Value (ROV) Process
  • Second Appraisal Procedures
  • GAO Study of a Public Appraisal Database

And More

To read the full News release, Click Here

My comments: Many thanks to the Appraisal Institute for telling us what the new Housing Act means for appraisers. Definitely worth reading the full News release.

Read more!! →

Posted in: Uncategorized

Former Appraiser Goes to Prison

Newz: Former Appraiser Goes to Prison, Board Says AMC Violated Appraiser Independence

July 10, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Who Said I Agreed To Be An Expert?
  • Former Florida Resident Sentenced to 20 Years in Federal Prison for Appraisal Fraud
  • Whimsical Storybook Cottage Built With Salvaged Wood From Old Boxcars Lists for Just $250K
  • The Board Has Spoken, and AMCs Should Pay Attention
  • MY AD: UAD 3.6 and the “Tablet” Question By Doug Smith, SRA
  • UAD 3.6 and the Future of Residential Appraising By Tony Pistilli
  • The Full Measure: Midyear 2026 Economic Update for Appraisers By Kevin Hecht
  • MBA STATS: Mortgage applications decreased 2.2 percent from one week earlier

———————————————

Former Florida Resident Sentenced to 20 Years in Federal Prison for Appraisal Fraud

Excerpts from DOJ Press Release

Tampa, FL – Armando Martinez (51, Plano, TX) has been sentenced by Chief U.S. District Judge Amos Mazzant, III, of the United States District Court for the Eastern District of Texas to 20 years in federal prison for bank fraud. Martinez previously pleaded guilty. U.S. Attorney Gregory W. Kehoe made the announcement.

According to court documents filed with the United States District Court for the Middle District of Florida, Martinez, who had his Florida Appraiser’s license revoked, orchestrated and executed a bank fraud scheme directed at multiple financial institutions by taking over the identity and license number of a legitimate licensed appraiser.

Martinez then purportedly conducted onsite appraisals for dozens of properties in Florida. In reality, Martinez paid others to go to the properties and take pictures for appraisals he completed. He then sent the appraisals to the victim lenders, using his computer after having fled the United States to the Dominican Republic.

Based on the false and fraudulent appraisals, the financial institutions were fraudulently induced to approve and fund mortgage loans and pay Martinez appraisal fees. As a result of Martinez’s appraisal fraud, more than $65 million in mortgages are impaired or defective. These mortgages were either guaranteed by the Federal Housing Administration or purchased and guaranteed by Fannie Mae and Freddie Mac.

Dave Towne Comments: Another ethically twisted former appraiser is going to be experiencing “three hots and a cot” for the next 20 years, assuming the full sentence is served.

It never ceases to amaze me how some very bad people in our profession think they can keep the ‘wool pulled over the eyes’ of financial institutions, and the funders or guarantors of those mortgage loans.

In this case, the former appraiser had his licenses in Florida and Texas REVOKED in 2020. But then stole the identity of another unsuspecting appraiser, fled the US, hired ‘go-fers’ to get Florida subject and comp photos and data, then wrote, signed and submitted fraudulent appraisals after the revocation date.

The other sickening part of this, which is not mentioned, is that the ‘go-fers’ the convicted appraiser hired probably were akin to “gig workers” with limited education or understanding of what they were actually doing to assist the mortgage frauds activity.

To subscribe to Dave Towne’s emails, send an email to dtowne@fidalgo.net requesting to be added to his email list. I have subscribed for many years. He lives in Mt. Vernon, WA

To read the full Press Release, Click Here

Read more!! →

Posted in: AMCs, bad appraisers, Economic analysis, UAD 3.6

GSEs New Info on Completing UAD 3.6

Newz: GSEs New Info on Completing UAD 3.6,

2026 Appraiser Survey: State of the Profession

July 3, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Buyer Wants Lower Price to Negotiate
  • 2026 Appraiser Survey: State of the Profession By Isaac Peck, Publisher, WorkingRe
  • Abandoned 1822 Federal-Style Estate That Was Relocated and Then Carefully Rebuilt Hits the Market for $1.6 Million
  • Can (Should) AI Replace Your Office Staff? By Dustin Harris
  • MY AD: UAD 3.6 and the “ Tablet “ Question
  • Fannie/Freddie Job Aids for Completing URARs Using UAD 3.6
  • FHA Updates for QC requirements for Appraisal Field Reviews
  • Mortgage applications increased 0.04 percent from one week earlier

————————————————————

2026 Appraiser Survey: State of the Profession

By Isaac Peck, Publisher, WorkingRe

Excerpts: Nearly one-third of all practicing appraisers plan to leave the profession within three years. Add the next cohort and roughly half intend to exit within the next five years.

Those are the headline numbers from Working RE‘s 2026 State of the Profession Survey, completed by approximately 1,800 appraisers nationwide in early 2026.

Before the retirement cliff narrative takes hold, consider this: Working RE ran a nearly identical question in its 2016 Future of Appraising Survey. At that time, 33 percent of respondents planned to retire within five years, and more than half within 10 years. Today, a decade later, most of them are still appraising.

The pattern goes back further still. In a 2009 Working RE survey (18 years ago), conducted at the bottom of the financial crisis with over 6,200 respondents, over 53 percent of appraisers said they did not expect to be appraising full-time five years from then. While the profession did see some attrition over the next five years due to the incredibly slow market that followed the 2008 real estate crash, the fallout was nowhere close to 50 percent of the profession, or even 25 percent.

Appraisers consistently overpredict their own demise.

Different This Time?

Working RE spoke with Jim Park, President of the Collateral Risk Network (CRN) and the former Executive Director of the Appraisal Subcommittee, to get his read on the survey findings. Park says the 2026 numbers reflect a genuine inflection point, not a repeat of the false alarms that preceded them.

“This time it’s different,” Park says. “We’ve reached a point where a number of things are happening at the same time. The average age of an appraiser has to be in the range of 60 to 65. That’s retirement age. On top of that, depending on who you talk to, 10 to 25 percent of appraisers could cease doing mortgage work because of UAD 3.6 alone. How many will ultimately adapt to the new form? How many will come back after sitting it out? We’ll see. But I’m more concerned about the lack of new people getting into the business than I am about the people who might leave.”

UAD 3.6: The Readiness Gap

The November 2, 2026 mandatory compliance deadline for UAD 3.6 is roughly four months away. While Working RE‘s survey ended March 15 (three months prior to this publication), even if we account for a rapid ramp up, the data suggests that the profession is not ready.

The Takeaway

Taken together, the 2026 survey describes a profession that is older and more experienced than it has ever been. Appraisers remain skeptical of hybrid products, are divided on credentialing, and approaching one of the most significant form changes in decades largely untrained. The retirement numbers are alarming on their face but unconvincing as a cliff narrative. Working RE‘s own historical data makes that case directly.

What the 2026 data cannot tell us is whether UAD 3.6 will finally push appraisers into retirement in a way that past challenges failed to do.

To read more, Click Here

My comments: Very interesting. Worth reading. Many topics with graphs and other data. The only recent appraiser survey I have seen.

Read more!! →

Posted in: Appraiser Survey, Freddie, GSEs, UAD 3.6

AQB Exposure Draft Removes College Degree Requirement

Newz: Appraisal Stress Test, AQB Exposure Draft Removes College Degree Requirement

June 26, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: State Board Complaint Frustrations
  • The Appraisal Profession Is Being Stress-Tested. That’s Not the Same as Being Replaced By Jessica Sturm
  • All About the Brownstone: How the Iconic Design Went From Humble Row House Roots to Million-Dollar Metropolis Luxury
  • MY AD: UAD 3.6 Software Evaluation Checklist By Doug Smith
  • Include E&O in Appraisal Reports? Just Say No By Isaac Peck
  • AQB second exposure draft removes college degree requirement
  • MBA STATS: Mortgage applications increased 1.0 percent from one week earlier     
  • ———————————————————


The Appraisal Profession Is Being Stress-Tested.

That’s Not the Same as Being Replaced

A frank conversation about UAD 3.6, waiver expansion, and where the real opportunity lies.

By Written by : Jessica Sturm, EVP of Property Services at Opteon.

Excerpts:

What UAD 3.6 Actually Changes (And What It Doesn’t)

UAD 3.6 changes the infrastructure around how appraisal judgment is captured, structured, and delivered. It does not change what a great appraiser does and the value they bring. Your ability to walk a property and know, as a trained professional, that the finished basement wasn’t permitted, that the kitchen renovation was done on the cheap or that the comparable three streets over sold under pressure. None of that local, industry expertise lives in a data schema.

What the new standard demands is that the mechanics around that judgment are handled cleanly and consistently. Field data capture, structured commentary, condition ratings, quality flags, all in a format that downstream systems can use. That’s not a threat to expertise. We see this as a long-overdue investment in the infrastructure that supports our industry.

What the Stress Test Is Really Asking

Every industry stress test asks the same question: who is built for what comes next?

UAD 3.6 is asking whether the profession can operate with greater rigor and efficiency. Waiver expansion is asking whether appraisers can own the complex, high stakes, advisory end of the market with real authority. The mature appraiser pipeline is asking whether the profession can retain experience and retrain while bringing in and developing new people. These are hard questions, but the profession has more tools, more data, and more support to answer them than at any point in its history.

Accounting faced the same reckoning. When tax software arrived and then matured, the prediction was that it would hollow out the profession. Routine compliance work did automate and what happened next was the opposite of collapse.

To read more, Click Here

My comments: Interesting analysis. I think the new reports are much better than the old forms for reviewers and borrowers. If I was doing GSE appraisals I would look forward to doing them.

Read more!! →

Posted in: appraisal business, AQB, E&O, liability, UAD 3.6

UAD 3.6: The Appendices

Newz: UAD 3.6: The Appendices, Will Florida Governor Eliminate Property Taxes?

June 19, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Expanding Intended Users? Not So Fast
  • UAD 3.6 Answer Headquarters: The Appendices
  • Private Island for Sale: 25-Acre Historic Maine Estate Lists for $3.85 Million
  • Buying a private island & prices are now higher than last year
  • By Ryan Lundquist
  • MY AD: Doug Smith’s tips on selecting UAD 3.6 software
  • Florida Gov. Ron DeSantis Unveils His Plan To Virtually Eliminate Property Taxes
  • A record 242 U.S. cities now have starter homes that cost $1M
  • MBA STATS: Mortgage applications decreased 3.8 percent from one week earlier

—————————————–

UAD 3.6 Answer Headquarters: The Appendices

Excerpts: Start Here: The Appendices as Your Foundation

When Fannie Mae and Freddie Mac rolled out UAD 3.6, they published an entire documentation ecosystem to go with it. That ecosystem includes a full suite of appendices (A-1 through G-1), each serving a specific purpose. Some are highly technical and aimed at software developers and data delivery. But for appraisers doing the day-to-day work of completing reports, three appendices are essential core references: F-1, C-1, and D-1.

Here’s how each one functions:

Appendix F-1: The Field-by-Field Reference Guide

If there’s a single document that deserves the title of “master manual” for the dynamic URAR, it’s Appendix F-1. This is your comprehensive field guide. It details every possible field in the report, specifies when each field is required (and when it’s conditional), defines what answers are acceptable, and explains how data must be formatted.

Appendix C-1: Your Visual Roadmap

If F-1 is the user manual, C-1 is the map. Appendix C-1 is a visual layout of the dynamic URAR that shows every possible field and label that could appear in a report, giving you a complete picture of the report’s full scope before you ever open an assignment.

Appendix D-1: Context and Practical Examples

While F-1 and C-1 handle the mechanics of the report, Appendix D-1 adds interpretive depth. This appendix provides sample scenarios that show how specific data elements fit into the overall appraisal and are particularly useful when you’re dealing with edge cases or less common property situations.

Layer In the Selling and Servicing Guides

The appendices answer the “how” of UAD 3.6. For the “why”—the policy context and secondary market expectations behind those requirements—you need to work with the Fannie Mae and Freddie Mac Selling and Servicing Guides.

To read more details in the article, Click Here

For more information, go to Fannie’s Uniform Appraisal Dataset page,

Click Here To read the documents scroll down the page

My comments: This is the best explanation of the GSE AD 3.6 documents. Read this article!! UAD 3.6 can be confusing with many documents available. This article breaks them down so you can understand what they do.

When I took my first UAD 3.6 class “Appraiser’s Guide to the New URAR” in early 2025 it was overwhelming and mostly went over F-1. Now I know what the other documents cover.

Read more!! →

Posted in: real estate market, UAD 3.6

Recent Executive Orders Affecting Appraisers

Newz: Recent Executive Orders Affecting    Appraisers, When Appraisers Take the Stand

June 12, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: A case of forgery
  • Recent Executive Orders: Threat, Opportunity, or Both for Appraisers? By Kim Perotti, AXIS AMC
  • $22.8 Million Aspen Home With Its Own Private Waterfall Feels Like a Real-Life Fairy Tale
  • MY AD: If the Standards Are Uniform, Why Isn’t Your License? By Thaddus Dawson, Jr., CG
  • When Appraisers Take the Stand By By David C. Wilkes, Esq., CRE, FRICS and Kevin M. Clyne, Esq., CRE
  • Agents, Are You Using AI to Price Your Listings? By Tom Horn
  • 10K Appraisers. Policy and Advocacy Day, By 10K Appraisers Foundation
  • MBA: Mortgage applications increased 10.8 percent from one week earlier

Recent Executive Orders: Threat, Opportunity, or Both for Appraisers?

By Kim Perotti, a founding partner of AXIS AMC

Excerpts: In March 13, 2026, President Trump signed two Executive Orders that together amount to a clear message for our profession: build more houses, make credit easier, and get the valuation piece done faster and cheaper. We think it’s critically important that our industry discuss the implications.

The two orders are:

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION

AND PROMOTING ACCESS TO MORTGAGE CREDIT

While they are not “about” appraisers, the Executive Orders will absolutely reshape the environment in which we work. Appraisers who treat these as background noise will find the ground shifting under their feet. Those who read them as a roadmap can pick their spots and come out stronger and, more importantly, help shape how they are put into practice.

REMOVING REGULATORY BARRIERS TO AFFORDABLE HOME CONSTRUCTION:

Faster, Cheaper Construction – What That Really Means for Your Desk

PROMOTING ACCESS TO MORTGAGE CREDIT: Faster, Cheaper Valuations – Where the Squeeze Shows Up – Second Order

The second order takes direct aim at how loans—and valuations—get done. The theme is unmistakable: streamline, digitize, and de-emphasize technical compliance.

For appraisers, here are the potential realities:

More alternative valuation products: Regulators are being encouraged to expand the use of AVMs, desktop, and hybrid appraisals and reduce full appraisal requirements on low-risk and small-balance loans. You should expect more hybrid and desktop requests and data-only products as well as a clearer dividing line between high-volume, low-margin work and complex, higher-risk assignments.

Pressure on fees and turn times: Agencies are being asked to set “clear appraisal timelines” and cut costs and therefore lenders will likely lean harder on speed and price whenever a waiver, AVM, or hybrid is allowed, and traditional assignment ordering will have to justify itself on risk grounds.

Changes in who can appraise and how: The order invites simplification of appraiser qualification requirements. Easier entry could mean more competitors and lenders may fill low-fee niches with less-experienced personnel or non-traditional vendors.

If your business is built primarily on simple, low-risk assignments, this is a direct competitive challenge.

Alignment of FHA and VA rules: HUD and VA are asked to align standards where risk is comparable, clarify what truly requires pre-closing repairs vs. what’s cosmetic, and expand post-closing repair flexibility.

That could change the frequency and scope of “subject to” conditions, reduce some friction and disputes around FHA/VA appraisals, and make your judgment about safety vs. cosmetic issues more visible and important.

In summation, this order calls for more technology and alternatives, more pressure on traditional appraisals, and more segmentation of valuation products by risk level.

A Clear Fork in the Road for Appraisers

Taken together, these two Executive Orders point in one direction: more volume, more complexity at the edges of the market, and more pressure to commoditize anything that looks “low risk.” Together they create a fork in the road for real estate appraisers:

If you stay in the lane of interchangeable, low-complexity assignments, you will feel the squeeze—from technology, from relaxed standards, and from new entrants.

If you lean into complexity—new construction, manufactured and modular, fringe markets, environmental and hazard issues, FHA/VA nuance—you become harder to replace, not easier.

This doesn’t mean abandoning efficiency or refusing alternative products. It means being fluent in hybrids and desktops so you can decide which work makes sense for you, positioning yourself as the expert when a lender can’t responsibly rely on an AVM or a waiver, and building documented expertise in the exact areas these orders will expand.

To read more, Click Here

My comments: Definitely worth reading. All about what this means for appraisers in detail. The best analysis for appraisers I have read about this executive order. The author is definitely an “insider” as she is Co President of AXIS, a long time AMC. When I wrote one of my first articles on AMCs, I interviewed AXIS.

Read more!! →

Posted in: AI, appraisal business, appraisal how to, appraisal regulations, lender appraisals, Uncategorized, USPAP

Creative Appraisal Definitions – Humor

Newz: Creative Appraisal Definitions – Humor, FHA Modernization Minimum Property Requirements

June 5, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Subpoena Threat Over a 10-Year-Old Appraisal
  • Creative Appraisal Definitions Humor
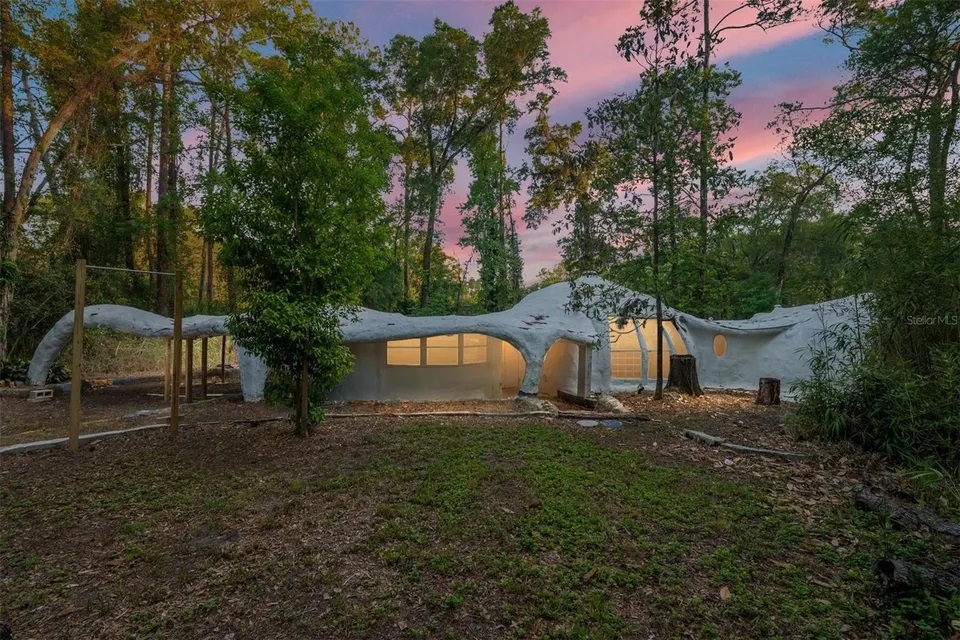
  • Foam Dome Home With ‘Not a Single Straight Line’ Hits the Market in Florida for $249K: ‘A Genuine Original’
  • My ad: How to decide which UAD 3.6 software to use
  • USPAP’s Typical Buyer Standard in the Fair Housing Era, By Edwin Farr, MAI
  • FHA Seeks Public Comment Regarding Modernizing Its Single Family Housing Minimum Property Requirements
  • Upcoming UAD 3.6 Bootcamp in Irving, Texas
  • MBA: Mortgage applications decreased 2.5 percent from one week earlier

————————————————-

Creative Appraisal Definitions – Humor

Excerpts:

  • Purpose of the Appraisal – To make a living in the appraisal business.
  • Functional Obsolescence – That state of many older appraisers.
  • The Subject – A term police use to identify the victim of a crime.

To read more, Click Here

My comments: We can all use some appraiser humor !!

For commercial and residential appraisers.

————————————————-

Foam Dome Home With ‘Not a Single Straight Line’ Hits the Market in Florida for $249K: ‘A Genuine Original’

Read more!! →

Posted in: bias, FHA, UAD 3.6

Adapt or Step Back? How UAD 3.6 Is Forcing a Career Decision for Appraiser

Newz: UAD 3.6 Adapt or Step Back,

Getting Started With AI

May 29, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Too Late for a Reconsideration of Value
  • Adapt or Step Back? How UAD 3.6 Is Forcing a Career Decision for Appraisers, By Rachel Mann
  • 109-Year-Old ‘Boathouse’ That Appears To Float on Washington Canal at High Tide Hits the Market for $2.1 Million
  • Getting Started with AI for Appraisers
  • MY AD: Loose Lips Cause Claims (Loose Lips Lead to Lawsuits) By Claudia Gaglione, Esq.
  • Wells Fargo Settles Mortgage Discrimination Suit With $100M Fund To Help Low-Income Homebuyers
  • HB 355 and What Every Appraiser Should Learn from Kentucky’s Legislative Win, By Bryan S. Reynolds, MNAA
  • MBA: Mortgage applications decreased 8.5 percent from one week earlier

——————————————-

Adapt or Step Back? How UAD 3.6 Is Forcing a Career Decision for Appraisers

By Rachel Mann

Behind the technical transition lies a more personal question: Is it worth starting over at this stage of a career?

Excerpts: A Profession Split in Real Time

While there’s plenty of buzz around UAD 3.6 itself, it’s worth taking a boots-on-the-ground look at what active appraisers are actually feeling. In a recent industry poll conducted on Facebook, the findings were telling.

Out of 233 responses from active appraisers, 36.5% reported they are actively preparing, while 36.1% are taking a “wait and see” approach. The remaining responses, which we’ll get into below, reveal the deeper undercurrents.

The clear takeaway is that the industry isn’t aligned. There’s real uncertainty in how appraisers are responding to the shift, and a large unknown hanging over the profession.

And it raises a question: Is the uncertainty driven by the change itself, or by the lack of clear options for what happens next?

Appraiser Voices: Real Reactions to UAD 3.6

Beyond the “actively preparing” and “wait and see” camps, smaller groups of respondents revealed the deeper anxieties at play.

About 8.2% cited concerns about the learning curve, 4.7% said they’re considering stepping back from volume, and 2.6% plan to retreat into private work only.

Another 12% fell into smaller categories ranging from software testing readiness and hardware concerns to skepticism about implementation timelines.

The overall picture is a mix of readiness, hesitation, and resistance — revealing capacity limits and decision fatigue at a critical moment: adapt or step back? The underlying question for those nearing retirement is: Is it worth the time, cost, and effort to adapt at this stage in my career?

When a Workflow Change Becomes a Career….

A sudden decline in active appraisers could carry real consequences:

  • Loss of experienced appraisers who currently make up the majority of the workforce
  • 2. Disruption of long-standing client relationships, leaving lenders, AMCs, and homeowners scrambling
  • A thinning mentorship pipeline for new appraisers, weakening the path forward for the next generation
  • These changes, paired with the lack of exit planning, have broader implications. This isn’t an individual issue; it impacts industry stability and continuity.

To read more, Click Here

My comments: Worth reading the entire post for the details and interesting comments.

Read more!! →

Posted in: AI, bias, state appraiser regulators, UAD 3.6