AMCs: Survey, How Tech Sabotages Appraisers

Newz: Appraiser AMC Survey, AMCs: How Tech Quietly Sabotages Appraisers

November 6, 2026

ARTICLE LIST – In order, Scroll down to read

  • LIA AD: Read The Fine Print
  • Independent Appraiser Voices plus Survey: More in Common Than We Think
  • Inside a Marvel Showrunner’s $2.4 Million Topanga California Compound Featuring a 1970s Geodesic Dome and Private Oak Grove
  • Helping Appraisers Get Paid for What They’ve BuiltBy Isaac Peck, Publisher, WorkingRE
  • My Ad: Major Changes in Fannie Mae’s HBU Property Eligibility Requirements (Effective With UAD 3.6), By Denis Desaix, MAI, SRA
  • Countdown in Chicago: UAD 3.6, AI, and Rates Going Up? MBA 2026 Recap, By Jim Morrison
  • The Full Measure: October 2026 Housing Market Update, By Kevin Hecht, Appraiser and Economist
  • The Ghost in the Machine: How Tech Quietly Sabotages Appraisers, By Desiree Mehbod
  • Appraisers face stagnant pay and rising costs as AMCs defend their fees and new technology reshapes the industry
  • Mortgage Applications Decrease 1.2 Percent in Latest MBA Weekly Survey

Thanks to our Sponsor!!!

Very reasonable prices and good open rates!
———————————————————————–

Independent Appraiser Voices: More in Common Than We Think and and AMC Appraiser Survey

Independent Appraiser Voices is breaking the silence on unfair AMC fees and UAD 3.6 struggles to prove that while we may work independently, we don’t have to face these industry battles alone.

Excerpts: Independent Appraiser Voices is breaking the silence on unfair AMC fees and UAD 3.6 struggles to prove that while we may work independently, we don’t have to face these industry battles alone.

If you’ve been an independent appraiser for any length of time, you’ve probably asked yourself, more than once, “How much more am I expected to take on without being compensated for it?”

Between rising business expenses, increasingly complex assignments, unrealistic deadlines, and AMC fees that often seem disconnected from the work involved, there’s plenty to be frustrated about.

And now we have UAD 3.6. We can probably all agree that the UAD 2.6 forms were due for an update, but is this really the improvement we needed?

We know these frustrations because we’re dealing with them, too. And they’re exactly what inspired Independent Appraiser Voices (IAV). BookAppraisals

IAV is a brand-new, independent grassroots initiative created by working appraisers who believe it’s time to do more than vent about these problems individually. We’re boots-on-the-ground appraisers, just like you, trying to make a living while navigating the same challenges.

There are already people around the country advocating for change in our profession, and we share those goals. We want to bring independent appraisers together, identify the concerns we have in common, and turn our shared experiences into a stronger, more unified voice.

Our first step is the 2026 Independent Appraiser Survey: UAD 3.6, AMC Fees & Industry Concerns.

The survey is anonymous and covers compensation, UAD 3.6, AMC practices, unpaid time, and other industry concerns. There’s no membership, no fee, and nothing being sold. We simply want to hear directly from appraisers across the country.

The survey is anonymous and covers compensation, UAD 3.6, AMC practices, unpaid time, and other industry concerns. There’s no membership, no fee, and nothing being sold. We simply want to hear directly from appraisers across the country.

Our intention is to use the findings to document common concerns, support advocacy for meaningful change, and encourage greater cooperation among independent appraisers. We’ll share the results with the appraisal community and be transparent about what the data does and doesn’t tell us.

To read more, Click Here

To take the survey, Click the link in the article.

My comments: The survey seems like a good idea. I always like to read the survey results. I have never worked for an AMC so did not take the survey.
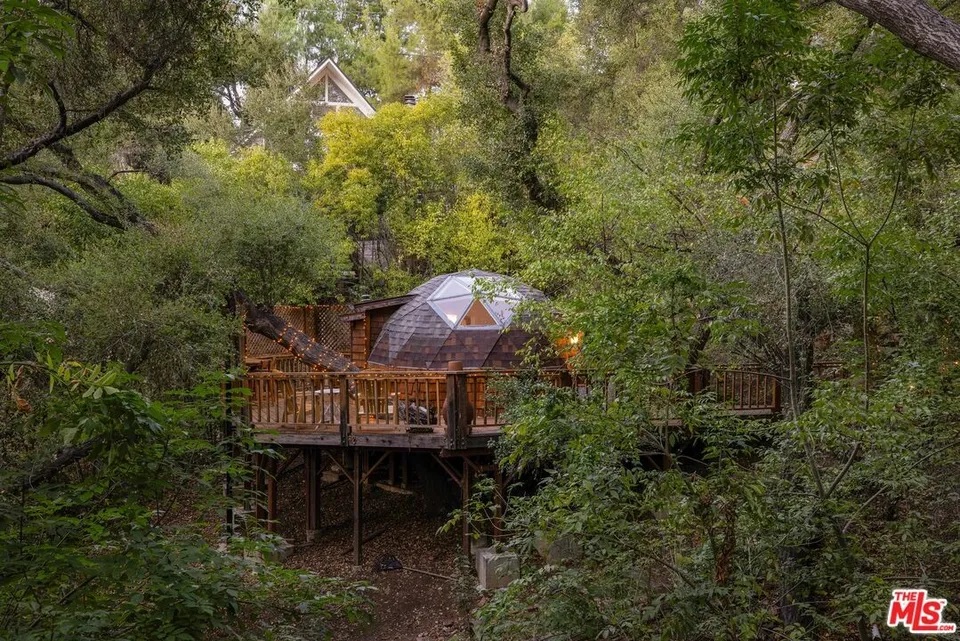

Inside a Marvel Showrunner’s $2.4 Million Topanga California Compound Featuring a 1970s Geodesic Dome and Private Oak Grove

Excerpts: 4 bedrooms, 4 baths, 1,547 sq.ft., 0.76 acre lot, Built in 1935

Built in 1935, the “thoughtfully cared for” 1,547-square-foot sanctuary boasts stone pathways, footbridges, and a seasonal creek. It is located in the Post Office Tract near Topanga State Park.

“What makes this property so special is its setting within a private oak grove,” says listing agent Nina Kurtz of Compass. “It genuinely feels like having your own private park.”

That private-park feel extends across the compound, which includes a two-bedroom primary residence and additional living space.

According to public records, the four-bedroom property is currently owned by Hollywood writer and producer Andrew Guest, co-creator, showrunner, and executive producer of Marvel’s “Wonder Man.” Guest purchased the property for $2.75 million in 2022.

Expansive windows were designed to frame the lushly landscaped lot and bring the outdoors into the living spaces.

To see the listing with an aerial view and 54 photos, Click Here

My comment: I would love to live in a private Oak Grove fully landscaped with a seasonal creek, house, and a Geodesic Dome. Before the Gold Rush from 1848 to 1855 my city was full of oak trees. Over time, most were torn down and Alameda became a suburb of San Francisco, 10 miles away with access via ferry boats.

I often think of the original native inhabitants, the Ohlone, who traveled to Alameda for oak tree acorns and access to San Francisco Bay with fish and shellfish.

Our pickleball courts are in a park and used to have a large oak tree that offered shade when it was hot. A large branch broke off and fell on part of our courts. We miss the large oak branch with the shade it provided. Large umbrellas are not the sameI

————————————————————-

Helping Appraisers Get Paid for What They’ve Built

by Isaac Peck, Publisher, WorkingRE

Excerpts: Most appraisal shops are one-person operations. The specter of the lone appraiser running their business in a spare bedroom and not socializing much with their peers has persisted for decades — and there’s certainly some truth to it.

However, one of the downsides to a solo-operator business model, especially with service businesses like appraisal, is that when it comes time to retire, these types of businesses are rarely saleable. With no (or few) assets, no staff and little goodwill outside of the name of the principal, most solo appraisers build their businesses for decades and then simply flip the light switch and shut the door on their business.

Bryan Reynolds wants to change all that.

A certified general appraiser, partner at Appraiser eLearning, host of The Appraisal Update Podcast, owner of Reynolds and Associates, and a partner at his two newest ventures — Legacy Appraisal and Consulting and Legacy Advisors and Consulting — Reynolds is a serial entrepreneur.

His latest ventures are particularly interesting and arguably well-timed, given everything the profession is facing.

Entering and Exiting the Profession

Reynolds sees real opportunity in simultaneously helping folks enter the profession, as well as working with appraisers who are about to step back and retire.

“Our vision is to help appraisers enter the profession and exit the profession,” Reynolds says. “What do most appraisers do when they’re ready to retire is they turn their light off and close the door. Their book of business, which in many cases represents 30 to 40 years of careful nurturing, just evaporates. They don’t get paid for it or rewarded in any way. We would like to help keep their legacies alive.”

Instead of just shutting the door, Reynolds explains that Legacy Advisors and Consulting is working with appraisers to set up an exit strategy that allows them to receive compensation for the first three to five years of retirement.

“We will ask them to stay with the company for a prescribed period of time,” Reynolds says. “Then we will put someone in their market, as well as our administrative and support team based out of western Kentucky. Basically, we want to see another appraiser step in and become them in that local market.”

Reynolds’ strategy requires the exiting appraiser to remain with the company for 12 to 18 months. If they want to retire, however, Reynolds requests they call a year in advance. Several interested appraisers have already reached out.

“I just talked to an appraiser who asked me, ‘What about the VA? I’m a VA appraiser. VA selects me to do the appraisal. How can I transition this business?’” Reynolds says. “Our position is that for every problem there is a solution.

Helping Train New Appraisers, Too

Reynolds also wants to help new entrants to the profession find their feet and get started. Legacy Advisors and Consulting is also licensing Melissa Bond’s MPact Practicum coursework, a successful appraiser curriculum.

Appraisers thinking about an exit strategy, and anyone looking at the training pathway, can find more at LegacyAppraisalandConsulting.com and LACappraiserpathway.com, or email info@LACappraiserpathway.com. Reynolds can be reached directly at Bryan@theLegacyAG.com.

To read more, Click Here

My comments: When I have written about selling your appraisal business (or spoken with appraisers), I have always said the best people are those working for you. Selling a one person appraisal business seldom happens. Sometimes if you’re in a vacation location an appraiser may be interested in locating. Or, a competitor may want to purchase it.

I have spoken with buyers and sellers of appraisal businesses. It is not easy for the buyer or the seller, even if you have employees and are well established. Staying over for a transition period is very common.

Selling a Commercial may be easier than residential. Over the years I have seen many larger commercial appraisal companies that expand by buying (or merging with) other local commercial appraisal companies.

Since I have been writing about this, over time several national appraisal firms merged with other commercial appraisal firms.

————————————————————-

Are you getting too many ad-only emails?

4 ways to get only the FREE email newsletters and NOT the ad-only emails.

1. Twitter: https://twitter.com/appraisaltoday posted by noon Friday – all recent newsletters

2. Read on blog www.appraisaltoday.com/blog Posted by noon Friday. You can subscribe to the blog in the upper right of each blog page.

3. Email Archives: https://appraisaltoday.com/archives

(posted by noon Friday) The link is above and to the right of the big yellow email signup form. Newsletters start with “Newz.” Contains all recent emails sent.

4. Link to the 10 most recent weekly newsletters (no ads) at www.appraisaltoday.com. Scroll down past the big yellow signup block.

To read more about the 4 ways, plus information on why I take ads, etc. Click here

———————————————————

Major Changes in Fannie Mae’s HBU Property Eligibility

Requirements (Effective With UAD 3.6),

By Denis Desaix, MAI ,SRA

In the November 2026 issue of Appraisal Today

Excerpts: In September of 2026, Fannie Mae (FNMA) announced major changes in their property eligibility standards regarding highest and best use (HBU) conclusions reported in the appraisal.

I was asked by Fannie to be a Policy Advisor on this matter and had a preview of the changes that have since been announced. I say this so I can affirm, with credibility, that a lot of thought has gone into the changes and

how they affect not only the appraisal process but the entire 1- to 4-unit residential lending production process.

In this article, I will discuss the new HBU policy and review the examples that Fannie uses to illustrate how the new policy can affect property eligibility which, in turn, can affect how we analyze and report our value opinions in our appraisal reports.

Please note that these changes apply to UAD 3.6 Appraisal Assignments only!!

The impact on lending is easy to describe: Certain properties that were previously ineligible for Fannie purchase are now eligible.

The impact on appraisers is also easy to describe:

To conclude a credible HBU opinion for some properties, a deeper level of analysis will be necessary.

This is not a bad thing for appraisers as the more complex the property, the less likely an alternative valuation tool can be used

To read more about this new UAD 3.6 change, plus 2+ years of previous issues, subscribe to the paid Appraisal Today.

If this article helped you understand this Fannie change, it is worth the subscription price!

—————————————————————-

Not sure if you want to subscribe?

Sign up for monthly auto renewal for $8.25!

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

What’s the difference between the Appraisal Today free Weekly email newsletters and the paid Monthly newsletter? Click here for more info

Cancel at any time for any reason!

You will receive a prorated refund.

$8.25 per month, $24.75 per quarter, and $89 per year (Best Buy)

or $99 per year or $169 for two years

Subscribers get FREE: past 18+ months of past newsletters

To purchase the Monthly Appraisal Today newsletter:

www.appraisaltoday.com/order or call 510-865-8041

————————————————–

Countdown in Chicago: UAD 3.6, AI, and Rates Going Up? MBA 2026 Recap – October 11-14, 2026

By Jim Morrison

Excerpts: he Mortgage Bankers Association Annual is always one of the best places to find out what is coming for the industry.

This year in Chicago, one topic was on almost every agenda: UAD 3.6. With the mandate only weeks away, lenders, GSEs, AMCs, and technology providers spent the week comparing notes on what is working, what isn’t, and what happens next. Add a market that still hasn’t turned the corner, a lot of conversation about AI, and a former President on the main stage, and it made for a busy few days.

Here are the sessions that matter most for lenders and appraisers. On UAD 3.6, Williamson confirmed November 2nd is still the date, but lenders that need more time can request an exception. About 25,000 UAD 3.6 appraisals have been submitted so far, roughly 10% of October volume.

Readiness Check: A Countdown to UAD 3.6

Low volume has been the biggest readiness gap. Some appraisers have been running test files on their own homes because the orders haven’t come in yet. Downing said appraisers typically see efficiency gains after three to five reports and are back on par with UAD 2.6 after about ten.

Review teams are learning too. Scarpa said his reviewers had never seen a 3.6 report and are training on the software alongside appraisers….

AI came up in almost every room. The largest lenders are leading the investment, and some are building custom models to help with review. Scarpa shared a story from another lender where a loan was nearly closed before they discovered the house was condemned and the photos had been generated by AI. Lenders now need to verify that images haven’t been altered, and appraisers need to protect the integrity of their own work.

To read more, Click Here

My comments: In the past, I went to several of the MBA National conferences as a reporter. I hung out in the reporters room with free lunch and snacks and had dinner with other reporters. It was definitely worthwhile attending as an appraiser to see what the speakers say.

————————————————————-

The Full Measure: October 2026 Housing Market Update

By Kevin Hecht, Appraiser and Economist

The rate is the headline. The spread is the story.

October brought a sharper version of the challenge that has defined the housing market all year: buyers are still interested, but payments are setting a hard limit on what many can buy.

Sales haven’t stopped, and prices haven’t moved in one national direction. Yet higher financing costs are giving buyers more leverage, increasing the importance of concessions, and making sellers and builders work harder to meet the market.

Topics include:

• The Mortgage Rate Is More Than a Treasury Yield

• The Fed Held, but Mortgage Rates Follow a Different Market

• The Economy Is Providing Support, But Not a Free Pass

• Existing Homes: More Choice, More Negotiation

• New Construction Has Its Own Price Signal

• Policy May Help at the Margin, But It Does Not Reset Today’s Market

For appraisers, the headline is not simply that the 30-year mortgage rate remains above 7%. The more useful question is why a mortgage rate can remain elevated even when the 10-year Treasury yield is lower.

The Appraiser’s Assignment

The market rewards an approach that is both current and specific.

• Review the financing terms and concessions, not just the sale price.

• Track whether competing listings are accumulating, expiring, or selling after reductions.

• Separate a price cut from a rate buydown.

• Identify whether new construction is competing directly with the subject or simply sharing the same broad geography.

• The appraiser’s job is not to force a national rate story onto a neighborhood. It is to determine how that neighborhood is responding to the financing environment using the best available evidence as of the effective date.

The national message is clear: the economy still offers support, but mortgage pricing is tightening the market’s filter. The local conclusion will depend on which properties still pass through it.

My comments: READ THIS ARTICLE! This is the only real estate market comments I read every month because it is written by an appraiser/economist for appraisers. You have probably had people (and clients) ask you about the topics above because you are an appraiser.

I took a economics class as preparation for my MBA classes. I had been appraising for 5 years. I was a much better appraiser after taking just the economics class. After I got my MBA I was an even better appraiser.

To read more, Click Here

—————————————————————-
The Ghost in the Machine: How Tech Quietly Sabotages Appraisers

By Desiree Mehbod

The real estate appraisal industry is being quietly rewritten by corporate tech platforms that automate blacklisting and manipulate home values behind the scenes.

Excerpts: For anyone working on the ground in the appraisal industry today, the real estate market does not feel like a fair playing field. It feels like an automated ecosystem designed to squeeze out local expertise in favor of corporate volume. While outsiders look at recent data and express shock, those of us in the trenches know the truth: bias, exploitation, and automated blacklisting are literally hardcoded into the platforms we are forced to use every day. BookAppraisals

To understand how broken things have gotten, you only have to look at what happened to a seasoned independent appraiser out West. After years of building direct relationships with lenders, his entire workflow evaporated into thin air over a matter of days. For six grueling months, his phone stopped ringing, and no new appraisal requests came through. He reached out to a trusted lender he had done business with for years, only to receive a shocking answer: “We have been sending you work orders for months, but you never responded. We thought you were ghosting us, so we removed you from our panel.”

What actually happened was not a lack of interest or an economic downturn. It was deliberate, systemic sabotage.

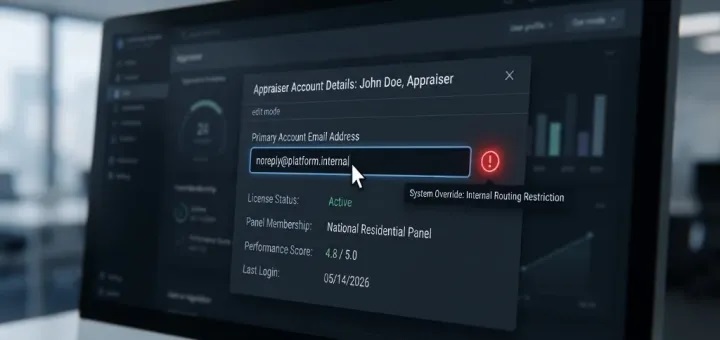
The appraiser had grown tired of receiving a nonstop, daily barrage of automated AMC bid spam flooding his inbox. When he pushed back against the platform handling the communications, an employee at the appraisal tech platform retaliated by quietly changing his account’s primary email contact to an internal “noreply” address. Because the system never sent out a bounced notification, lenders genuinely believed he was ignoring them. A single unlicensed tech employee effectively deactivated a small business with a few clicks, and it took a random, autopopulated form months later for the appraiser to discover the truth.

This is not just a horror story about bad tech support. It is a window into the unchecked power that tech platforms and Appraisal Management Companies (AMCs) hold over our livelihoods.

The software running this industry is built to control and discipline independent appraisers. Take the concept of appraiser grading metrics.

Appraisers are under the illusion that their performance ratings are private between them and an individual client. In reality, bad star ratings or panel removals from a single vindictive AMC are secretly shared across wider platform networks, like Mercury via the VMP suite. It creates a permanent, hidden anchor that ruins future work opportunities with other clients, with no shelf life expiration date and zero opportunity for a fair rebuttal.

This infrastructure directly explains the numbers people are starting to notice. A recent National Mortgage Professional article highlighted a stat showing that AMC appraisals are more likely to match a home’s contract price exactly, hitting it at 26.41% compared to 22.67% for non-AMC appraisals. To a data scientist, that might look like a statistical anomaly. To an independent appraiser, it is just Tuesday. See below for more information on the National Mortgage Professional Article see below.

To read more of the article above and read the appraiser comments,

Click Here.

My comments: I remember when AMCs took over appraisal management after the 2008 housing crash. A hot appraisal topic was how to be taken off the AMCs “do not use list”. Before AMCS took over lenders managed their own appraisal lists, often for overflow from their staff appraisers. Reportedly they shared their l “Do not Use” lists.

===========================================================

Appraisers face stagnant pay and rising costs as AMCs defend their fees and new technology reshapes the industry

From National Mortgage News

TOPICS:

  • Where The Appraisal Fee Goes
  • How AMCs Became The Status Quo
  • The Bidding Process
  • A New Appraisal Format, An Old Fight Over Fees
  • Who Manages The Work?
  • Outsourcing The Work Doesn’t Outsource the Responsibility
  • What Does The Research Say About Quality?

A few quotes:

“Appraisal management companies — although they’ve been around for many, many years — have morphed into this cottage industry.”

Marc Savitt, president of NAIHP and former NAMB president

—————————————————————–

“Appraisers are just getting nickeled and dimed, and we have no way to fight back.”

Joshua Tucker, chairman and co-founder of the

Appraisal Regulation Compliance Council

To read this article, Click Here

My comments: One appraiser’s AMCs story and comprehensive analysis of Where The Appraisal Fee Goes.HOW TO USE THE NUMBERS BELOW. Appraisals are ordered after the loan application. These numbers tell you the future for the next few weeks. For more information on how they are compiled, click here.

Note: I publish a graph of this data every month in my paid monthly newsletter, Appraisal Today. For more information or get a FREE sample go to www.appraisaltoday.com/order Or call 510-865-8041, MTW, 7 AM to noon, Pacific time.

My comments: Rates are going up and down in 2026 and probably in 2027 but no one knows for sure.

Mortgage Applications Decrease in Latest MBA Weekly Survey

WASHINGTON, D.C. (November 4, 2026) — Mortgage applications decreased 1.2 percent from one week earlier, according to data from the Mortgage Bankers Association’s (MBA) Weekly Mortgage Applications Survey for the week ending October 30, 2026.

The Market Composite Index, a measure of mortgage loan application volume, decreased 1.2 percent on a seasonally adjusted basis from one week earlier.  On an unadjusted basis, the Index decreased 2 percent compared with the previous week.  The Refinance Index increased 0.1 percent from the previous week and was 60 percent lower than the same week one year ago. The seasonally adjusted Purchase Index decreased 2 percent from one week earlier. The unadjusted Purchase Index decreased 4 percent compared with the previous week and was 19 percent lower than the same week one year ago.

“Mortgage rates drifted down to their lowest level since September 2026 last week in the wake of the Federal Reserve’s decision to hold on additional rate hikes at its October meeting,” said Mike Fratantoni, MBA’s SVP and Chief Economist. “While the 30-year rate declined to 7.3 percent, activity is still quite slow, with purchase application volume down for the week and refinance volume effectively flat at a very low level. As we have highlighted in recent weeks, more borrowers are choosing ARMs in this environment to lower their initial payments, with the ARM share at its highest level since September 2025.”

The refinance share of mortgage activity increased to 39.8 percent of total applications from 38.9 percent the previous week. The adjustable-rate mortgage (ARM) share of activity increased to 11.4 percent of total applications.

The FHA share of total applications decreased to 16.0 percent from 16.6 percent the week prior. The VA share of total applications increased to 11.2 percent from 11.0 percent the week prior. The USDA share of total applications increased to 0.6 percent from 0.5 percent the week prior.

The average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances ($832,750 or less) decreased to 7.30 percent from 7.37 percent, with points decreasing to 0.75 from 0.76 (including the origination fee) for 80 percent loan-to-value ratio (LTV) loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages with jumbo loan balances (greater than $832,750) decreased to 7.20 percent from 7.28 percent, with points decreasing to 0.48 from 0.64 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The average contract interest rate for 30-year fixed-rate mortgages backed by the FHA decreased to 7.02 percent from 7.12 percent, with points remaining unchanged at 1.07 (including the origination fee) for 80 percent LTV loans.  The effective rate decreased from last week.

The average contract interest rate for 15-year fixed-rate mortgages increased to 6.76 percent from 6.70 percent, with points increasing to 0.98 from 0.85 (including the origination fee) for 80 percent LTV loans. The effective rate increased from last week.

The average contract interest rate for 5/1 ARMs decreased to 6.29 percent from 6.41 percent, with points decreasing to 1.00 from 1.20 (including the origination fee) for 80 percent LTV loans. The effective rate decreased from last week.

The survey covers U.S. closed-end residential mortgage applications originated through retail and consumer direct channels. The survey has been conducted weekly since 1990. Respondents include mortgage bankers, commercial banks, thrifts, and credit unions. Base period and value for all indexes is March 16, 1990=100.

———————————————–

Ann O’Rourke, MAI, SRA, MBA

Appraiser and Publisher Appraisal Today

1826 Clement Ave. Suite 203 Alameda, CA 94501

Phone: 510-865-8041

Email:  ann@appraisaltoday.com

Online: www.appraisaltoday.com
Former Appraiser Goes to Prison

Newz: Former Appraiser Goes to Prison, Board Says AMC Violated Appraiser Independence

July 10, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Who Said I Agreed To Be An Expert?
  • Former Florida Resident Sentenced to 20 Years in Federal Prison for Appraisal Fraud
  • Whimsical Storybook Cottage Built With Salvaged Wood From Old Boxcars Lists for Just $250K
  • The Board Has Spoken, and AMCs Should Pay Attention
  • MY AD: UAD 3.6 and the “Tablet” Question By Doug Smith, SRA
  • UAD 3.6 and the Future of Residential Appraising By Tony Pistilli
  • The Full Measure: Midyear 2026 Economic Update for Appraisers By Kevin Hecht
  • MBA STATS: Mortgage applications decreased 2.2 percent from one week earlier

———————————————

Former Florida Resident Sentenced to 20 Years in Federal Prison for Appraisal Fraud

Excerpts from DOJ Press Release

Tampa, FL – Armando Martinez (51, Plano, TX) has been sentenced by Chief U.S. District Judge Amos Mazzant, III, of the United States District Court for the Eastern District of Texas to 20 years in federal prison for bank fraud. Martinez previously pleaded guilty. U.S. Attorney Gregory W. Kehoe made the announcement.

According to court documents filed with the United States District Court for the Middle District of Florida, Martinez, who had his Florida Appraiser’s license revoked, orchestrated and executed a bank fraud scheme directed at multiple financial institutions by taking over the identity and license number of a legitimate licensed appraiser.

Martinez then purportedly conducted onsite appraisals for dozens of properties in Florida. In reality, Martinez paid others to go to the properties and take pictures for appraisals he completed. He then sent the appraisals to the victim lenders, using his computer after having fled the United States to the Dominican Republic.

Based on the false and fraudulent appraisals, the financial institutions were fraudulently induced to approve and fund mortgage loans and pay Martinez appraisal fees. As a result of Martinez’s appraisal fraud, more than $65 million in mortgages are impaired or defective. These mortgages were either guaranteed by the Federal Housing Administration or purchased and guaranteed by Fannie Mae and Freddie Mac.

Dave Towne Comments: Another ethically twisted former appraiser is going to be experiencing “three hots and a cot” for the next 20 years, assuming the full sentence is served.

It never ceases to amaze me how some very bad people in our profession think they can keep the ‘wool pulled over the eyes’ of financial institutions, and the funders or guarantors of those mortgage loans.

In this case, the former appraiser had his licenses in Florida and Texas REVOKED in 2020. But then stole the identity of another unsuspecting appraiser, fled the US, hired ‘go-fers’ to get Florida subject and comp photos and data, then wrote, signed and submitted fraudulent appraisals after the revocation date.

The other sickening part of this, which is not mentioned, is that the ‘go-fers’ the convicted appraiser hired probably were akin to “gig workers” with limited education or understanding of what they were actually doing to assist the mortgage frauds activity.

To subscribe to Dave Towne’s emails, send an email to dtowne@fidalgo.net requesting to be added to his email list. I have subscribed for many years. He lives in Mt. Vernon, WA

To read the full Press Release, Click Here

Read more!! →

Appraisal Construction Progress Reports

Newz: Curiosity and AI, Construction Progress Reports

April 24, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Construction Progress Reports: Don’t Get Hammered
  • The Human Appraiser as a Macroeconomic Stabilizer By Kevin Hecht
  • Spectacular Glass Cabin Located Mere Steps From the Beach Lists for Less Than $175K
  • Appraisal Bias Training Now Required in Most States [2026]
  • MY AD: Review of Appraiser’s Guide to the New URAR Class
  • Curiosity in the Age of AI By Brent Owen
  • AI in real estate. Chat GPT can’t smell the 10 cats in the house By Ryan Lundquist
  • MBA: Mortgage applications increased 7.9 percent from one week earlier

———————————————————————–

Read more!! →

Appraiser Obsolescence?

Newz: Appraiser Obsolescence, ASB – Use of Technology in an Appraisal or Review

April 10, 2026

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Subpoena Threat Over a 10-Year-Old Appraisal
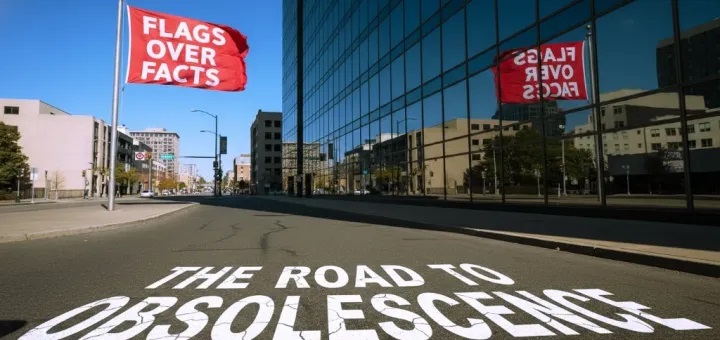
  • Flags Over Facts: The Road to Obsolescence By Desiree Mehbod
  • Mayfield Ranch: The $4.5 Million Texas Estate on 100 Acres That Looks Like It’s Been Standing for Centuries
  • April Fools Day and Other Important Dates in Appraisal History
  • MY AD: How to Cut Business Expenses
  • March 2026 Housing Market Updates for Appraisers By Kevin Hecht
  • ASB Proposed New Advisory Opinion 41, Use of Technology in an Appraisal or Appraisal Review Assignment
  • MBA: Mortgage applications decreased 0.8 percent from one week earlier


——————————————————–

Flags Over Facts: The Road to Obsolescence

By Desiree Mehbod

Excerpts: For years, appraisers have been warning that the mortgage industry was slowly engineering us out of the process. We were told we were paranoid. Resistant to change. Stuck in the past. Then the newest Mortgage Credit Executive Order arrived, and the appraisal section opened with a single line that confirmed everything we’ve been saying: expand AVMs, desktops, hybrids, and AI. That’s the priority. Everything else in that section is just polite filler wrapped around a strategy to shrink the role of the human appraiser until we’re little more than a signature at the bottom of a dataset.

And that strategy becomes even clearer when you look at what’s happening behind the scenes. While UAD 3.6 is not fully active yet, the structure being built around it makes the intention impossible to miss. The new system demands an avalanche of hyper‑granular data that has nothing to do with how appraisers actually determine value. Room‑by‑room material ratings, finish classifications, fixture‑level detail, micro‑condition scoring. It’s a level of data extraction designed for machines, not humans.

No buyer cares whether the guest bath faucet is “mid‑grade chrome” or “builder‑grade brushed nickel,” but the new dataset does. Not because it improves valuation, but because it feeds the models. UAD 3.6 turns every full appraisal into a data‑mining operation, with the appraiser acting as the human data‑collection device for a system that wants our expertise now so it can automate it later.

To read more, Click Here

My comments: Worth reading. Discusses VA, Road to Housing Act and other topics. Knowledgeable author – the founder of Appraisers Blogs.

Read more!! →

Appraisal Regulator Chaos

Newz: Appraisal Regulator Chaos , Cat and Raccoon Damages, Wildfire Risks

September 5, 2025

What’s in This Newsletter (In Order, Scroll Down)
NOTE: Scroll down to see Appraisal Regulator Chaos

  • LIA AD: Legal Request for Old Appraisal
  • The Kitty Litter Duplex: An Appraisal I Wish to Not Remember
  • $300K Maryland Home Is Overrun by Feral Cats and Raccoons
  • The Full Measure August 2025: Navigating Rates, Inventory, and Affordability
  • Appraisal Regulatory Chaos
  • The Town With No Bank: How Rural America Lost Its Mortgage Lifeline By Dallas T. Kiedrowski, MNAA
  • New Cotality Wildfire Risk Report finds more than 2.6 million homes are exposed to moderate or greater wildfire risk
  • Mortgage applications decreased 1.2 percent from one week earlier
    —————————————————————

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

————————————————-

———————————————————–

The Kitty Litter Duplex: An Appraisal I Wish to Not Remember

Excerpts: How one property’s furballs left an unforgettable impression on an apartment and an appraiser

Introduction

In the world of real estate, surprises abound. Industry professionals, especially appraisers, all expect the unexpected, but even the most seasoned professionals can stumble across situations that test the limits of their experience, composure, and their judgement. There are stories of haunted houses, collapsing ceilings, and outlandish tenant actions and decorative choices (Live, Laugh, Love), but the tale of the cat-soiled duplex stands out for its sheer yuck-factor. This is the story of what should be a routine property appraisal, which became cemented in my experience stories, due to its unfathomability and coated in an unmistakable, noxious layer of feline mischief.

The Setting: An Unimposing Duplex with a Dirty Little Secret…

The Appraisal Appointment: An Unforgettable First Impression

…I could only see the flooring in the opening and a few other spots around the living room from about a foot outside the threshold, the rest of the floor was completely caked with cat poop. The walls, ceiling, and windows were all enveloped by heavy spider webs in a variety of states, while some were fresh looking, others clearly blackened from a long life filled with dust, dirt, fur, and of course fecal matter. Also, you could see multiple patches of orange mold scattered throughout the walls and ceiling. I quickly replied I would not be going in there, because it was a danger to my health and safety, which somehow surprised her….

Financial and Health Implications: When Cleanliness Becomes a Value Killer

Hygiene, general maintenance, and property values parallel each other. This may be why we have condition codes for our appraisals. Just saying…. I made sure to thoroughly explain the situation and how the value was determined in the report. I did not want this rolling back downhill and getting me. Luckily, a very gracious Fresno Construction, was able to give me a quote very quickly, which came just over $100,000 for an estimate to redo the unit in its entirety.

Conclusion

The Kitty Litter Unit stands as a testament to both the resilience of a property and the unpredictability investors face. Especially in this case, since it was for an estate of a deceased former owner.

To read more, Click Here

My comments: I appraised a house for a relocation company – one story with 3 bedrooms. There were cats on every surface above the floor, such as dressers, – all staring at me of course. In the rear of the home was a very large cat enclosure. They were rescue cats, temporarily at the home. I did not ask the owner where the cats would go when she relocated – back to the shelter or with go with her.  I will never forget about all those cat eyes staring at me!

I had another relocation appraisal where the male cat had sprayed urine along several walls in the living room. I told the relocation company to replace the drywall.

Of course, I could fill up a book with dog stories. Such as two Dobermans that broke down the door of a trailer to get to me. I somehow made it to my car and I will never forget it. Or the small dogs who bit my ankles as I was trying to get through the front door (home was owned by an appraiser I knew). For both appraisals, I told my lender client to get another appraiser.

Read more!! →

12 APPRAISAL MYTHS

Newz: 12 Appraisal Myths, Appraisal Bias Lawsuit

August 8, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Legal Request for Old Appraisal
  • 12 Common Appraisal Myths/Misconceptions by Tom Horn
  • $750K Hobbit-Style Bunker in Tennessee Puts a Unique Spin on Underground Living
  • The Appraiser’s Market Compass: Navigating the Summer 2025 Housing Landscape By Kevin Hecht, Appraiser and Economist
  • Appraiser questions answered: Interview with Craig Capilla, Attorney
  • No, Appraisers Didn’t Cause America’s Racial Wealth Gap by Jeremy Bagott
  • Mortgage applications increased 3.1 percent from one week earlier

————————————————

————————————————–

12 Common Appraisal Myths/Misconceptions

By Tom Horn

Excerpts:

1. Appraisers Rely Primarily on Price Per Square Foot

This is probably the most common misunderstanding I run into.

Yes, price per square foot is one of many tools we use to analyze value—but it’s not the whole story.

2. Appraisals Are Just a Quick Comparison of Recent Sales

Some folks think appraisers pull the three most recent sales and call it a day.

In reality, it’s much more involved. We look at a wide range of comparable sales, analyze market trends, make adjustments for differences between properties, and apply professional judgment.

3. Appraisals and Home Inspections Are the Same

This is a big one for homeowners and buyers.

Home inspections focus on the condition and function of the property—things like the roof, HVAC, plumbing, and safety issues. The inspector is looking for problems.

Appraisals, on the other hand, are focused on value. We observe the overall condition, yes, but we don’t test systems or check for code compliance.

4. Automated Valuation Models (AVMs) Like Zillow Zestimates Are Equivalent to Appraisals

Zillow can be helpful for a ballpark estimate, but it’s not an appraisal.

AVMs use algorithms, public data, and sometimes outdated or incorrect info. They don’t know if your kitchen was remodeled last year or if the neighbor’s home was a distressed sale.

5. The Purpose of the Appraisal Changes the Value

This one trips people up sometimes.

They’ll ask, “What’s the value for a refinance?” or “How much is it worth for a divorce?” as if the answer changes depending on why we’re appraising it.

To read the details and all 12 reasons, Click Here

My comments: Read this blog post. It can help you keep out of hassles and problems when appraising. When you get asked these questions you will know how to respond.  Written for real estate agents, buyers, sellers and many other people but excellent tips for appraisers.

————————————————————————————–

$750K Hobbit-Style Bunker in Tennessee Puts a Unique Spin on Underground Living

Excerpts: 3 bedrooms, 3 baths, 3,024 sq.ft., built in 2010, 38.84 acre lot

When you think of a bunker, you probably don’t imagine a three-bedroom abode that’s brimming with modernity—which is just one of the reasons that a newly listed dwelling in Tennessee comes as a surprise.

Tucked into the hillside like a doomsday bunker, this Bethel Springs residence was originally built in 2010, yet it boasts a historic Hobbit-style feel akin to the quaint homes depicted in J.R.R. Tolkien’s picturesque Shire.

But much like Tolkien’s books, this home should not be judged by its cover.

Despite its bunker-esque setting and Hobbit-inspired exterior, inside the dwelling is a modern marvel, having been thoughtfully remodeled by its current owners to include an open floor plan and design-forward finishes like granite countertops and luxury vinyl plank flooring.

To read more plus photos, Click Here

To read the listing with 50 photos, Click Here

Read more!! →

Changes to FHA Appraisal Requirements

Newz: FHA Appraisal Changes, Fannie Measurement Standards Update

July 4, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA AD: Unreasonable Subpoena Request
  • HUD Announces Changes to FHA Appraisal Requirements
  • The Rock House In Larkspur CO Is Back On The Market for $1,000,000
  • Baghdad Bob of Freddie Mac Merits Mention As Mideast Erupts
  • The Full Measure – June 25, 2025 By Kevin Hecht, Appraiser and Economist
  • Fannie: Standardizing Property Measuring Guidelines
  • MBA: Mortgage applications increased 2.7 percent from one week earlier

———————————————————————————

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

———————————————————-

——————————————–

HUD Announces Changes to FHA Appraisal Requirements

Excerpts: There are four significant appraisal-related revisions to Section II. D. of the Handbook.

  1. Subject and comparable photograph requirements have been revised….
  2. The appraiser is no longer required to state the remaining economic life of the dwelling in the appraisal report.
  3. In situations in which the subject is located in an increasing or decreasing market, the appraiser is no longer required to include an absorption analysis, a minimum of two sales that closed within 90 days of the effective date, and two active listings or pending sales.
  4. For Section 223(e) mortgages, the appraiser is no longer required to include an estimate of remaining physical life for the subject property improvements.

It is important to note that the originating lender is the client, not HUD/FHA, and as such, the lender may still require some or all the above items.

To read more, Click Here

To read the full document, Mortgagee Letter 2025-18, Click Here

My comments: Read the full article above and the original Morgagee Letter (Link above) for more details if you do FHA appraisals.

————————————————————————–

The Rock House In Larkspur CO Is Back On The Market for $1,000,000

Excerpts: 2 bedrooms, 2 baths, 2,432 sq.ft., 0.86 acre lot. Built in 2000.

The Larkspur Rock House is an iconic Flinstones style home, and now it can be yours for only $1,000,000. The rocks are maybe 200 million years old!!!Outdoor living spaces.

The Rock House is anything but ordinary—this striking, stucco-clad home is seamlessly built into a soaring red rock monolith, transforming nature’s artistry into a one-of-a-kind architectural statement.

The dramatic rock wall isn’t a backdrop—it’s the centerpiece, rising through all three levels and anchoring each floor in natural grandeur. Every space is visually and physically connected to the monolith at its core.

To read more, Click Here

To read the listing, Click Here

https://www.zillow.com/homedetails/6619-Apache-Pl-Larkspur-CO-80118/13497121_zpid/

Read more!! →

Pending Sales for Appraisers

Newz: PAVE Problems, Outdated Mortgage Regulations

May 30, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA ad: Should I Complete this Assignment?
  • Pending Sales May Be Your Secret Weapon To Accurate Listings and Appraisals
  • $3.69 Million ‘Tron’-Inspired Mansion With ’80s Speakeasy and Ferrari-Themed Office
  • The Full Measure: May 2025 Housing Market Recap for Appraisers
  • TEAPOTS Exposed: The PAVE Initiative’s Illusion of Justice
  • Outdated Mortgage Regulations
  • Mortgage applications decreased 1.2 percent from one week earlier

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

—————————————————————————

———————————————————————————–

Pending Sales May Be Your Secret Weapon To Accurate Listings and Appraisals

Excerpts: Bottom line: Pending sales show you what’s happening now and where prices are headed. Skip them, and you’re stuck looking at yesterday instead of today.

Closed Sales Lag—Pendings Lead

The Built‑In Delay

  • A March 1 contract might not close until late April. By then:
  • Rates could move 50–75 basis points.
  • A new round of housing inventory could hit the market.
  • Economic news—jobs reports and inflation scares can spook buyers.

Appraiser’s View: How We Use Pending Sales (Even When We’re Handcuffed to Closings)

Time adjustments

Compare contract prices to 30‑60‑day‑old closings to justify ± market‑trend tweaks. If pendings are 3 % higher, you can show upward pressure — great ammo for your list price.

Feature bracketing

No pool comps closed? A pool home pending $25 k higher becomes my clue. Helps you price premium features correctly.

To read more, Click Here

My comments: Good discussion of many aspects of using pendings. Written for real estate agents, but many good tips for appraisers. I always look at pendings, including the ratio of pendings to listings. I got some good ideas from this blog post.  I have been appraising for 50 years. I like learning something new!

—————————————————————————————-

$3.69 Million ‘Tron’-Inspired Mansion With ’80s Speakeasy and Ferrari-Themed Office

Excerpts: 3 bedrooms, 3.5 baths, 4,853 sq.ft., 8,509 sq.ft. lot

Futuristic, three-bedroom mansion that was inspired by the hit 2010 sci-fi movie “Tron: Legacy” has made a high-speed return to the market in Dallas, where it is listed for $3.69 million.

The decked-out dwelling, which also boasts an auto showroom in the living room and a Ferrari-themed home office, has been driven right to the top of the week’s most popular home’s list, after pulling in a huge amount of interest from buyers thanks to its very unique aesthetic.

Opulence abounds in every room of the property, which is spread across 4,853 square feet and includes a 1980s speakeasy with “turquoise tufted walls,” as well as a dramatic two-story living room with soaring ceilings.

To see the listing with 40 photos and a virtual tour, Click Here

My comments: See the wild interior photos with Ferraris and many unusual features!

Read more!! →

Surplus vs. Excess Land for Appraisers

Newz: Surplus vs. Excess Land, Interest Rate Drop? GSE Oversight?

May 2, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA ad: Am I Still on the ‘Do Not Use’ List?
  • Surplus Land vs. Excess Land: What Appraisers Needs to Know
  • 5 Mind-Boggling Optical Illusion Houses That Have To Be Seen To Be Believed
  • Fed officials offer differing signals on timing of potential interest rate cuts
  • Fed seen cutting policy rate by a full percentage point this year
  • The Balancing Act: How Appraisers Can Navigate Supply Shortages, Interest Rates, and Tariffs
  • A Cry from the Appraisal Trenches: The Fall of GSE Oversight
  • Mortgage applications decreased 4.2 percent from one week earlier

Surplus vs. Excess Land for Appraisals

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news


———————————————————

Surplus Land vs. Excess Land: What Appraisers Needs to Know

By Kevin Hecht

Excerpts: Land valuation is a fundamental aspect of real estate appraisal, influencing property transactions, development decisions, and investment strategies. A key part of the process involves distinguishing between the land that supports the property’s current use and any additional land that may—or may not—have independent value.

Commonly, a square footage adjustment is made based on lot size differences among comparable properties without one key distinction – whether the difference in land is surplus or excess land. This fails to consider whether the extra land has value independent of the subject property.

Surplus land and excess land are often confused. Surplus land is land which adds no value independently of the property being appraised. Excess land, on the other hand, has value because it can be divided and sold separately. These distinct differences must be accounted for in an appraisal.

Here we will discuss what constitute excess and surplus land, common methods used to identify each, and why it matters….

Methods for Identifying Surplus vs. Excess Land

Residential appraisers commonly make a dollar per square foot adjustment for differences in lot size among comparable properties without distinguishing whether the land is surplus or excess. The problem with this approach is that it fails to consider highest and best use where excess land—land that can be independently sold or valued—creates a premium.

This question cannot be answered without evaluating zoning and legal restrictions of the property.

For example, just because a property is large enough to support a second structure, zoning may prohibit multiple residences on a single lot or there may be legal restrictions in terms of land coverage and minimum square footage requirements. If this were the case, it would be considered surplus land.

When determining if land is excess land, appraisers must consider legal permissibility, physical possibility, financial feasibility, and profitability.

To read more, Click Here

My comments: Read this blog post. Residential appraisers can easily make a mistake on this topic and get into trouble.

—————————————————————————————-

5 Mind-Boggling Optical Illusion Houses That Have To Be Seen To Be Believed

Excerpts: Photo above info:

2. 8198 Uphill Rd, Joshua Tree, CA

Price: $17,950,000

The Invisible House: This mirrored mansion is the brainchild of film producer Chris Hanley and Frank Gehry collaborator Tomas Osinski, who designed the home to seemingly vanish into its desert surroundings.

At first glance, you might not notice the 5,470-square-foot residence staring back at you. Nestled on 67.5 acres, the shimmering structure was created with the intent of connecting its residents with the desert through the mirrored glass exterior. The three-bedroom estate’s interior is just as astonishing featuring retractable glass walls; a 100-foot, heated indoor swimming pool; and a 224-square-foot, white wall designed for movie screenings.

Whether you are looking for a home that quite literally disappears into the Arizona desert or one that mirrors its landscape in the Hamptons, these works of jaw-dropping art not only offer a captivating design but a remarkable setting.

From California to New York, we found five optical illusion abodes that will leave you wondering if they are playing tricks on your eyes.

To read more, Click Here

My comments: Click on the addresses for the listing. I have written about some of these before. I am fascinated by these types of homes. Now you can see 5 of them in one link. My favorite is the home in the photo above.

Read more!! →

Appraisers and Firearms

Newz: Appraisers and Firearms,Future of Home Finance and GSEs, Q1 2025 Fannie Mae Appraiser Update – New URAR

April 4, 2025

What’s in This Newsletter (In Order, Scroll Down)

  • LIA ad: A Family Feud and Intended Use
  • Experiences with Firearms as an Appraiser: When Tenants Behave Unexpectedly in “Their Area”
  • Billionaire Opendoor Founder’s Three-Winged ‘Propeller Home’ Hits the Market for $40 Million
  • Appraisal Institute Scandal – Widespread Fraud Uncovered
  • Housing Market Shows Early Signs of Spring By Kevin Hecht, SRA
  • Reshaping Home Finance: The Future of Fannie Mae, Freddie Mac, and U.S. Mortgage Policy By Rob Chrisman
  • Originator jobs; Stated income loans; DOGE shifts its attention; Fannie lawsuit; clear path for rates By Rob Chrisman
  • Q1 2025 Fannie Mae Appraiser Update! – New UAD Sample Reports and Ratings, Time Adjustments
  • Mortgage applications decreased 1.6 percent from one week earlier


Click here to subscribe to our FREE weekly appraiser email newsletter and get the latest appraisal news

——————————————————————————–

————————————-

Experiences with Firearms as an Appraiser: When Tenants Behave Unexpectedly in “Their Area”

Excerpts: Appraisers often find themselves in a wide variety of settings and situations. I mean, we are entering people’s homes, somewhere that most people see as their comfort zones and a place they are not open to having a stranger poke around in. We as professionals understand this and usually try to make it as quick and painless as possible. There are those moments where it turns into a “memorable experience” and homeowners or tenants feel like they must make it known we are not welcome.

I personally am batting .1000 this year on multi-family properties, where tenants have felt it was necessary for me to get the message, by brandishing a firearm. I will share the following two situations, how I personally managed it, explain why I do not personally carry a concealed firearm, and ask you readers to tell me if this is common or for similar memorable experiences.

For more information and to read the appraiser comments, Click Here

My comments: My first appraisal-related job was with the Monterey (California) County Assessor’s office. It was transitioning to computerized valuation. I was a temporary “appraiser assistant” hired to go to properties to see if the county appraisal records needed updating.

In those days (mid-1970s), properties were reappraised regularly to increase the assessments and property taxes were increased.

I knocked on the door and was met with a man carrying a shotgun. He said: Go away assessor! I don’t remember the city, but it was not in a rural area. I left and told my supervisor to find someone else to do the inspection.

I have never owned a firearm and would never carry one. No one I knew owned a firearm except for my husband, who had firearm training when he was teaching horticulture at a state prison. I would not allow a firearm in our house but still keep a baseball bat by my front door “just in case”.

But, recreational firing at a target was on my “bucket list”. An appraiser friend took me to a local firing range. I tried handguns, rifles and shotguns. Some worked like machine guns with many bullets fired at one time. I really liked it the best. Next time I go to Las Vegas I will try out real machine guns. Trying to hit a target did not appeal to me. Ya never know until you try!

Of course, I have had many encounters with dogs. One was when I was appraising the house of an appraiser I knew. I was met with small dogs biting my ankles. When the owner put the dogs away I continued with the appraisal. Another time, in a rural area, 3 large Dobermans broke down the door of a mobile home and ran toward me. I managed to get in my car. I told the lender to get another appraiser.

When markets crashed I did a lot of foreclosure appraisals. I made a lot of noise opening the door and loudly saying I was an appraiser for the lender and needed to come inside. I never had a problem. But some appraisers requested that a police officer accompany them when the home looked “sketchy” to them from the outside.

Read more!! →